The Week Ahead 4-8 August: US tech, BoE interest rate decision

A ‘strange serenity’ is how I have heard markets in the US described this week - which has concluded with a step up in Donald Trump’s global tariff regime. ‘Punch drunk’ is another description, which seems apt considering it has been four months since ‘liberation day’ - a period of time when the word ’tariff’ has never been far from the business headlines.
The S&P 500 is down marginally in the last five days, but it hasn’t really faltered compared to the movement that week in April when the president first launched his tariff hand grenade. In fact, the index is up more than 27% from those April lows and is, once again, close to all time highs.
As of this week, we now have two companies with a market capitalisation of over $4trn. NVIDIA (NSQ:NVDA) and Microsoft (NSQ:MSFT) now account for almost 15% of the total market. Throw Apple (NSQ:AAPL) into the list and the three largest companies in the S&P 500 now make up more than a fifth of the total index. That’s not a particularly healthy state of affairs.
But then it’s hard to argue with the fact that numbers from the US tech giants to have announced results this week have been spectacular. In the three months to June, Microsoft sales were 18% higher at $76.4bn, with operating income rising even faster. Apple revenues rose 10% to a whopping $94bn in the third quarter, with particularly impressive growth coming from the iPhone - which turned 18 at the end of June.
For Apple investors the tariff threat hangs heavier than it does with some of its peers. Despite expectation-beating numbers, investor response was somewhat muted during after-hours trading on Thursday. Amazon shares also faltered in response to a weaker than expected outlook, which is largely tariff-based.
The strange upside to Trump’s mind boggling policies is that it has forced markets (and market watchers) to be far more idiosyncratic. Companies are being analysed for their individual merits far more so than they have been in recent times. That should be a welcome relief for private investors, for whom the seemingly never-ending growth of tracker funds has become hard to compete with.
Closer to home, the FTSE has been similarly nonchalant about wild US policies. The FTSE 100, where the largest and most internationally diverse businesses live, was down marginally on Friday and for the week, but remains close to the 9,100 point level which marks all time highs.
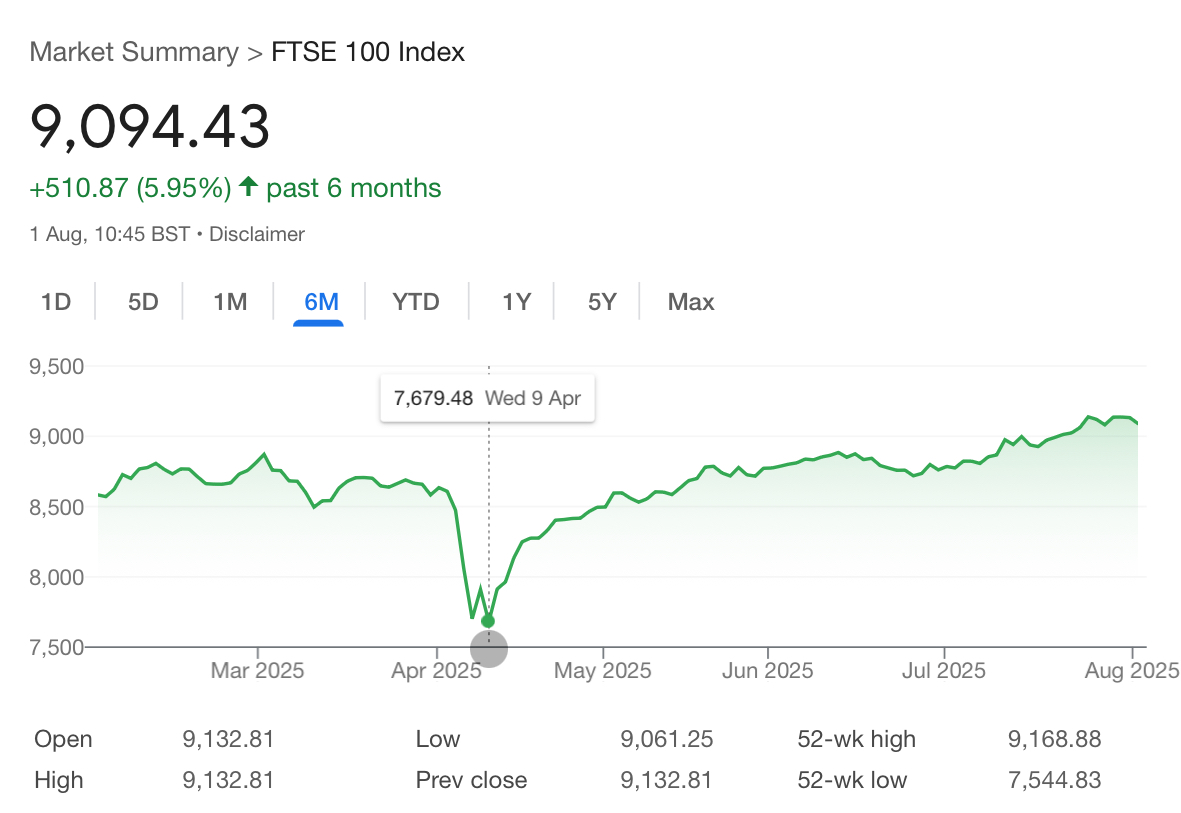
New highs on the horizon, or has the peak been reached?
The interesting thing about the current slew of financial results announcements (from both sides of the pond) is the outlook for the rest of the year. And here there is definitely a sense of hesitation.
None more so than from Next (LON:NXT) - which issued a brilliant trading update for the 13 weeks ending in July, but warned that the same pace of growth might be difficult to maintain.
Next full price sales were a whopping 10.5% higher than the same period of the previous year, which was substantially ahead of the previous 6.5% guidance. The company has pointed to the weather and unexpected challenges of a ’major competitor’ (read: Marks & Spencer which spent more than a month without an online site following a malware attack) as the reasons for this outperformance.
But management - ever the masters at managing expectations - have also said that the second half might be tougher. Guidance for the remainder of the year has been maintained at 1.9% UK sales growth, the primary reason for that is a relatively gloomy outlook for the economy.
We expect UK employment opportunities to continue to diminish as we enter the second half, with the effects of April's National Insurance changes continuing to filter through into the economy as the year progresses. We believe that this will increasingly dampen consumer spending as the year progresses.
Next won’t be the only company to struggle if these predictions come to pass, but it is one of the only companies to have set out the challenges quite so clearly. With that in mind, I am not particularly hopeful that companies which have had a bad first half will have the capacity to turn things around in the second.
The Week Ahead
It’s still busy in both the UK and US next week with another big batch of companies set to announce financial results.
But the big news will come on Thursday when we’ll get the latest interest rate decision from the Bank of England. Investors were hoping for a rate cut from the current 4.25%, but weaker economic figures in recent weeks have put those expectations into some doubt. July’s higher-than-expected inflation figures caused some economists to say it would be “irresponsible” to cut the base rate in August’s meeting. All eyes will be on the Bank of England on Thursday.
Economic Calendar
Monday 4 |
||
07:30 |
Switzerland |
Inflation rate |
15:00 |
US |
Factory orders |
Tuesday 5 |
||
13:30 |
US |
Balance of trade |
15:00 |
US |
Services PMI |
Wednesday 6 |
||
10:00 |
Eurozone |
Retail sales |
12:00 |
US |
30yr mortgage rate |
Thursday 7 |
||
07:00 |
Germany |
Industrial production |
07:00 |
UK |
Halifax house price index |
12:00 |
UK |
BoE monetary policy report and interest rate decision |
Companies Reporting
UK Trading Updates and AGMs |
UK Financial Results |
International Financial Results |
|
Monday 4 |
Duke Capital (DUKE) Zenova Group (ZED) |
Kosmos Energy (KOS) |
Palantir Technologies (PLTR) Idexx Laboratories (IDXX) |
Tuesday 5 |
CML Microsystems (CML) Galantas Gold (GAL) Northern Venture Trust (NVT) Syncona Limited (SYNC) |
Fresnillo (FRES) GlobalData (DATA) InterContinental Hotels Group (IHG) International Workplace Group (IWG) Keller Group (KLR) Serica Energy (SQZ) Sig (SHI) Smith & Nephew (SN.) TP ICAP (TCAP) Travis Perkins (TPK) Diageo (DGE) Naked Wines (WINE) |
Caterpillar (CAT) Advanced Micro Devices (AMD) Amgen (AMGN) Pfizer (PFE) Yum Brands (YUM) Zoetis (ZTS) Snap (SNAP) |
Wednesday 6 |
Georgina Energy (GEX) OptiBiotix Health (OPTI) Paypoint (PAY) Pri0r1ty Intelligence Group (PR1) Telecom Plus (TEP) |
3i Group (III) 4imprint (FOUR) Coca-Cola HBC AG (CCH) Georgia Capital (CGEO) Glencore (GLEN) Ibstock (IBST) Lancashire Holdings (LRE) Legal & General Group (LGEN) Quilter (QLT) TP ICAP (TCAP) Tritax Big Box REIT (BBOX) Vesuvius (VSVS) |
McDonalds (MCD) Walt Disney (DIS) Uber (UBER) Airbnb (ABNB) |
Thursday 7 |
Caffyns (CFYN) Investec (INVP) Marks Electrical (MRK) Northern 3 VCT (NTN) UKR Product Group (UKR) Volex (VLX) |
Burford Capital (BUR) Harbour Energy (HBR) Hikma Pharmaceuticals (HIK) Hutchmed (China) Limited (HCM) Mears Group (MER) Morgan Advanced Materials (MGAM) Serco Group (SRP) Spectris (SXS) |
Eli Lilly (LLY) Gilead Sciences (GILD) Constellation Energy (CEG) Expedia (EXPE) Warner Bros Discovery (DISCA) |
Friday 8 |
Stelrad Group (SRAD) TBC Bank Group (TBCG) The Renewables Infrastructure Group (TRIG) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Commentators say that the US economy will be hit by the tariffs in due course, and that some evidence is starting to show, but Trump will be doing his best to stop any objective analysis from organisations with responsibility for reporting data, that don't show his policies in the best light.
Nonsense.....
Adding to the above:
Zotefoams (LON:ZTF) interims 5th August. Last ten days chart/ SP activity doesn't look too good.
Vanquis Banking (LON:VANQ) interims 7th August. Had been sucked into the motor finance gloom despite little or no exposure.
ARK Innovation UCITS ETF USD Acc (LON:ARKK)
Understand UK motor finance is quite a big issue but over the pond be watchful. If tech falls then the market gets scared.
Friday was big imo. Not seller yet but Monday will be an 'inflection'.
A correction is due (unless you on the losing end).
Boeing Co (NYQ:BA)
See a pattern yet. If not then go specsavers.
TP Icap (LON:TCAP) reporting on both Tuesday and Wednesday? TP ICAP `TBC` I think.
TP Icap (LON:TCAP)
Wednesday according to the company's website.
One of the more interesting events could be the reaction first thing Monday morning to today’s after-market judgement by the Supreme Court on car finance. Interested spectator that I am. I hold S&U.
Yes, good spot!
Very useful. thanks
Agree that great to have a heads up.
Palantir Technologies (NSQ:PLTR) and Advanced Micro Devices (NSQ:AMD) of interest .
Maybe Serco (LON:SRP) worth a look.
Very useful information, thank you Megan. I'm looking forward to next week now.