The Week Ahead (7th-11th July) - Big Beautiful Bill

Hello and welcome to this week’s edition of the Week Ahead.
US markets have been closed today (Friday), but I can see on the spread betting platforms that the Dow Jones is changing hands at around 44,600, while the S & P is around 6,240, each down c. 0.5% today.
This is after the passage through the House of Representatives of the hotly-contested One Big Beautiful Bill Act (its official title!)
The consequences of this bill are heavy for domestic US politics and for US industry, for example including a range of tax cuts and major new commitments to defence spending, while clean energy tax credits are phased out.
But the consequences of the bill outside of the US - such as the UK - may well turn out to be insignificant.
For example, the bill raises the debt ceiling by $5 trillion (the ceiling was previously set at $36 trillion). In theory, you might imagine that this is negative for the dollar against other currencies. But the debt ceiling has already been raised dozens of times, to the point now where it’s difficult to imagine that it will ever have a practical effect on the ability of the US government to borrow.
Dollar weakness has been a theme all year, since before the “OBBA” became a political football. Year-to-date, GBP/USD has increased 9% to 1.36.
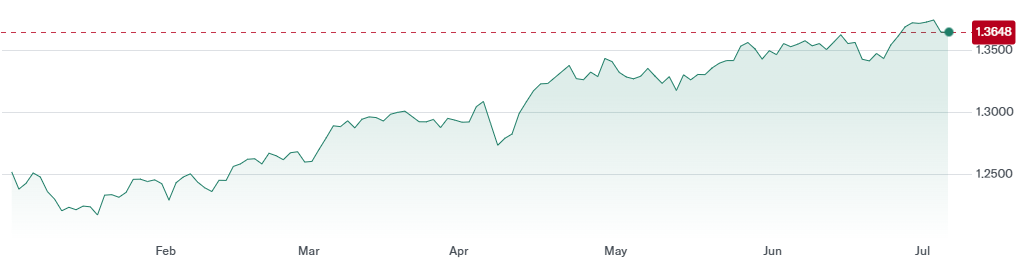
GBP/USD. Source: finance.yahoo.com
Closer to home, there was some controversy around the position of the Chancellor mid-week. The 10-year gilt yield rose to 4.67%, but has since eased back below 4.6% after Sir Keir Starmer made it clear to the media that she has his “full support”. While the 10-year yield remains a little higher than it was before the controversy, it is well within the range at which it has traded year-to-date (4.4% - 4.9%).
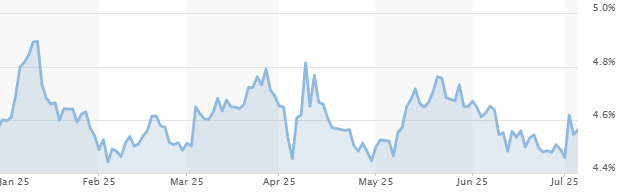
UK 10-Year Gilt. Source: MarketWatch.com
Meanwhile, as we head into the dog days of summer, company news may become a little quieter - this is evident in the schedule below. Have a great weekend!
Economic Calendar
| Date | Time (BST) | Country | Event |
|---|---|---|---|
7 July | 07:00 AM | UK | Halifax House Price Index |
7 July | 10:00 AM | EU | Retail Sales |
7 July | 08:00 PM | US | Consumer Credit (US) |
8 July | 01:00 AM | UK | Retail Sales |
9 July | 12:00 PM | US | MBA Mortgage Applications |
9 July | 03:30 PM | US | Crude Oil Inventories |
10 July | 01:00 AM | UK | RICS Housing Market Survey |
10 July | 01:30 PM | US | Initial Jobless Claims |
11 July | 07:00 AM | UK | Gross Domestic Product |
11 July | 07:00 AM | EU | Consumer Price Index |
Companies Reporting
| Day | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 7 July | Sirius Real Estate (SRE) 1Spatial Holdings (SPA) | Vanquis Banking (VANQ) | |
Tuesday 8 July | Celebrus Technologies (CLBS) Solid State (SOLI) DSW Capital (DSW) Optima Health (OPT) Synectics (SNX) | ||
Wednesday 9 July | Airtel Africa (AAF) LondonMetric (LMP) National Grid (NG.) Palace Capital (PCA) Ariana Resources (AAF) Worldwide Healthcare Trust (WWH) Young & Co’s (YNGA) | Jet2 (JET2) Renold (RNO) System1 (SYS1) Zigup (ZIG) | |
Thursday 10 July | BT (BT.) DCC (DCC) Dr. Martens (DOCS) Infinity Energy Systems (IES) Land Securities (LAND) Pets at Home (PETS) Powerhouse Energy (PHE) Severn Trent (SVT) Strix (KETL) Vipera (VIP) Vistry (VTY) | Trifast (TRI) | Progressive ($PGR) Fast Retailing Co. ($FRCOY) |
Friday 11 July |
| PageGroup (PAGE) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
I wonder about the potential upside for some UK companies, e.g. Solid State (LON:SOLI) (I hold), which has a diversified portfolio that may be in the sweet spot of supply to the US defence industry and is a potential beneficiary through the tax allowances of the OBBBA for its increase in US manufacturing capacity.
Hi, I am new to stockopaedia finding all the information very useful can I ask when you send out the week ahead? Is it possible to point out which stocks are likely to report ahead of expectations? Then I can focus my attention on those stocks thanks
Everything is ok...until it isn't.
If the US can continue to sell debt at reasonable rates, the merry go round can continue. But if the music stops, the Fed will have to buy these bonds, i.e. money printing on a grand scale. Massive inflation, dollar slump and depression.
In the UK, Reeves is toast. Labour will happily revert to borrow and spend.
There is no unlimited pool of money that investors can put into additional government debt. At some point there will be a bond strike. It is not a question of 'if' but 'when'.
Personally i think investing in gold, silver and their miners is the best option. The fact that these have rocketed in the last 6 months indicates that others with deeper pockets than mine are thinking along the same lines.
Vanquis Banking (LON:VANQ) interims 7th August not July.
No comments?. Suppose its America and TDS - both a mistake if want to make money.
Stocko just put an Apple (NSQ:AAPL) alert email in my inbox. And it looks very nice as a possible breakout from a lower base.
So what is going on with this 2.3t company. Lots of negative press over China, iphone sales, tariffs blah blah but Mr Share Price says something afoot, and worth a look.
I'm in their ecosystem so biased, new phone every 3 years (recycled to the grandkids), iMac have the 'oldun' (still good, like Grandpa) and the new one (oddly not as good - screen smaller).
To take a photograph (the best phone camera by far - could buy it and beat a £1000 camera anyday - and do other stuff (phone calls who would know). I photo buildings for professional purposes and good enough and in the pocket.
My employer, as seems common uses cheaper Samsung phones with Android systems (reminiscent of Microsoft early days with sudden wipeouts etc). The frustration of trades doing their job and wasting time on IT is massive.
Maybe Apple would be no better but they don't play in that space.
The elephant in the ether is their internet search and AI offerings (Siri/Safari) both getting better but the reputation (IP) is not there - that is the growth catalyst - strong, safe, does what it says on the tin - rebuild a brand.
That will be huge catalyst - the talk is now of trillion dollar companies when a while ago a billion would be quite nice - lol.
Reading the 'news' often throws you off the scent. But actually this looks a fantastic company and maybe "on sale". The Siri/AI thing is clearly their catalyst and will win or lose on that hill.