The Week Ahead (8 – 12 Sep): Gold, Inflation, Adobe, Warpaint, Gamma Communications

A rather boring week for index investors. Despite some volatility during the week, the major indices are largely flat. However, the spot gold price has broken out to new all-time highs during the week, resurrecting investor interest in all things shiny:
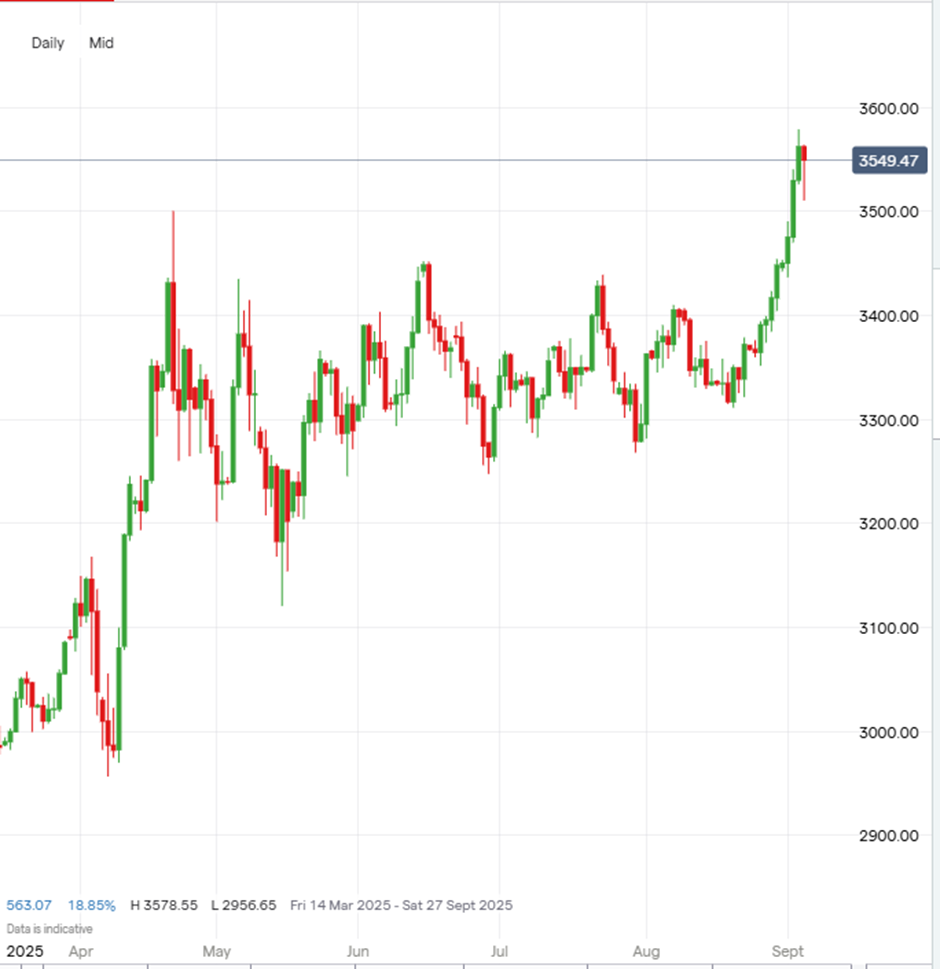
Here's what we can look forward to next week:
Economic Calendar
Monday 8th Sep |
||
07:00 |
Germany |
Balance of Trade Industrial Production |
15:30 |
United States |
Consumer Credit |
Tuesday 9th Sep |
||
Wednesday 10th Sep |
||
02:30 |
China |
Inflation Rate |
12:00 13:30 15:00 15:30 |
United States |
MBA Mortgage Applications Producer Price Index Wholesale Inventories Crude Oil Stocks |
Thursday 11th Sep |
||
00:01 |
UK |
RICS Housing Market Survey |
13:15 |
Euro Area |
ECB Rate Decision |
13:30 |
Germany |
Current Account |
13:30 |
United States |
Inflation CPI Initial Jobless Claims Continuing Claims |
19:00 |
United States |
Budget Statement |
Friday 12th Sep |
||
06:00 |
Germany |
CPI Inflation |
07:00 |
UK |
GDP Index of Services Industrial Production Balance of Trade Manufacturing Production |
Inflation figures for China and the US will dominate this week's economic news. In the US, inflation is forecast to be flat:
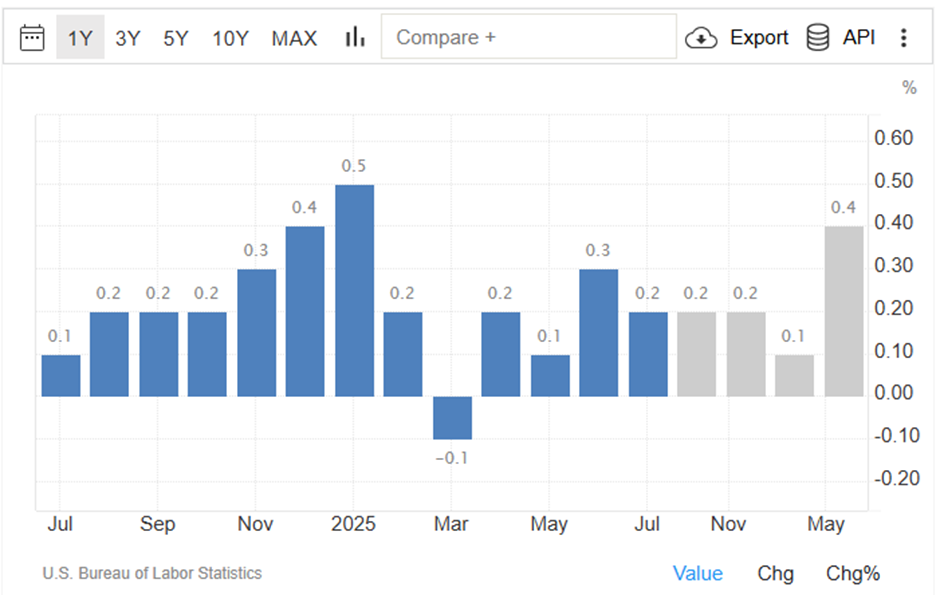
[Graph: Trading economics]
However, the tariff impact is a big unknown here. If this comes in unexpectedly hot due to tariff price rises working their way through the supply chain, this may impact the ability for the Fed to cut interest rates.
In China, we have the opposite problem. Inflation figures have been weak for much of 2025. Forecasts are for inflation to be flat, before rising to more normal levels at the end of the year:
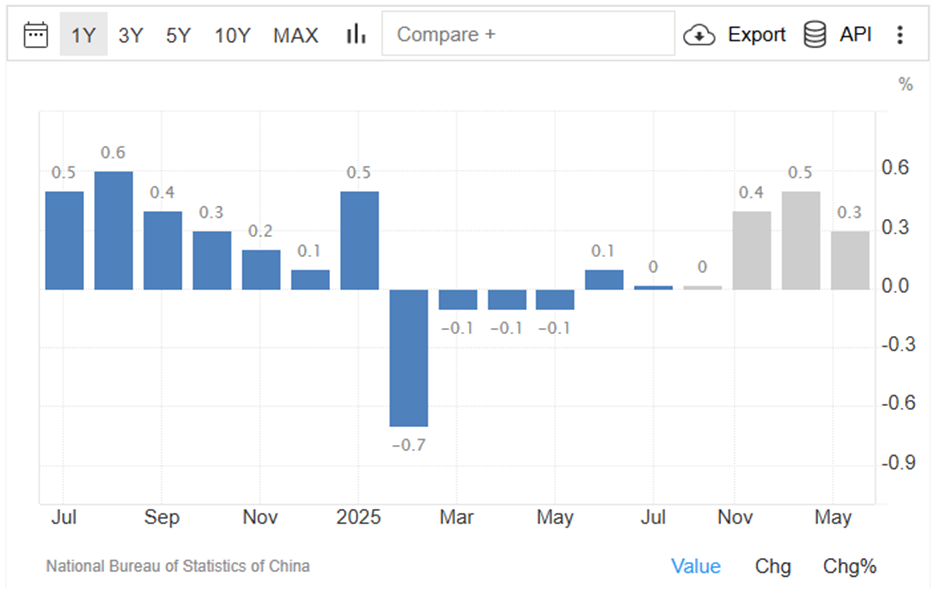
[Graph: Trading economics]
The risk here is deflation, and again, tariffs are a worry. If these push China into a deflationary spiral, it would be detrimental to global GDP growth.
In the UK, we get GDP figures on Friday with figures for July 2025. The forecast for Q3 is relatively weak at just 0.2%, down from 0.3% in Q2:
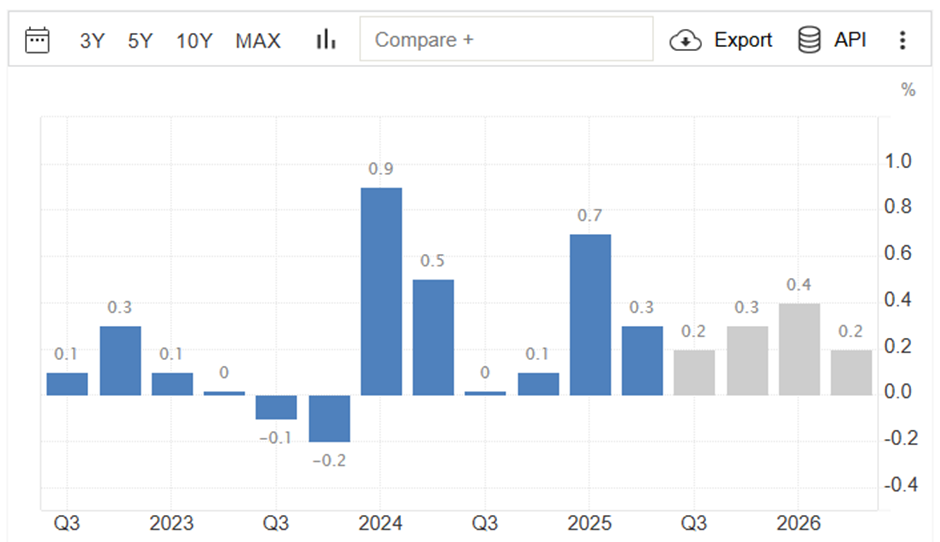
[Graph: Trading economics]
The July figures will indicate how likely this is, given the market worries around the lack of growth and the impact this may have on tax rises in the Autumn Budget.
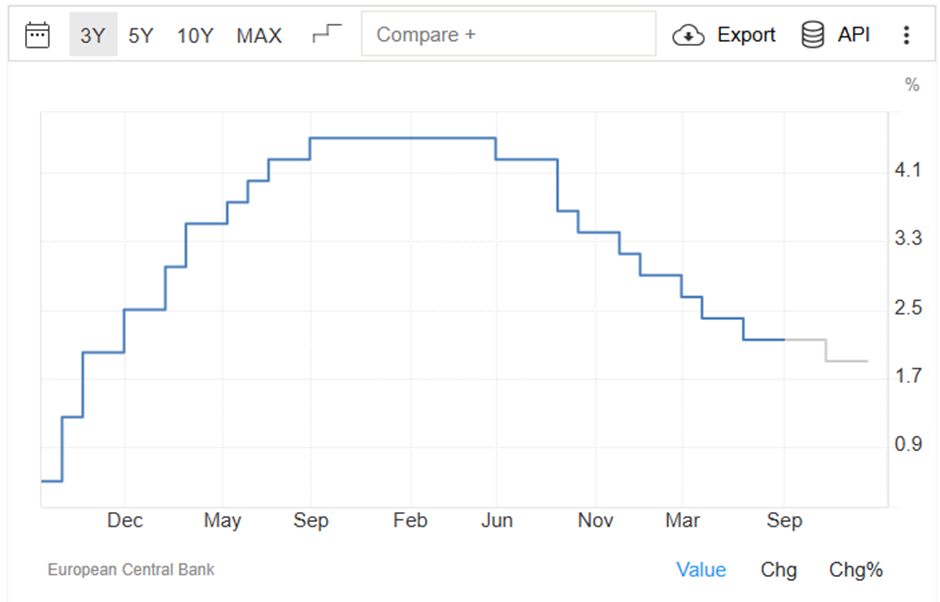
In Europe, we get the ECB interest rate decision. Forecasts are for this to be held at 2%:
[Graph: Trading economics]
At the last meeting in July, they said:
The incoming information is broadly in line with the Governing Council's previous assessment of the inflation outlook. Domestic price pressures have continued to ease, with wages growing more slowly. Partly reflecting the Governing Council's past interest rate cuts, the economy has so far proven resilient overall in a challenging global environment. At the same time, the environment remains exceptionally uncertain, especially because of trade disputes.
So the decision here is unlikely to be surprising, and if it is, it will be for a further small cut in rates.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 8 Sep |
The Works (AGM) |
Concurrent Technologies (Interims) Gaming Realms (Interims) Norman Broadbent (Interims) Sigmaroc (Interims) Trellus Health (Interims) |
Casey's General Stores (Q2) |
Tuesday 9 Sep |
Northern Bear (AGM) |
Accesso Technology (Interims) Computacenter (Interims) Dunelm (Finals) Flowtech Fluidpower (Interims) Gamma Communications (Interims) Getbusy (Interims) James Fisher & Sons (Interims) Likewise (Interims) Luceco (Interims) Midwich Group (Interims) Pci-pal (Finals) UK Oil & Gas (Interims) |
Oxford Industries (Q2) |
Wednesday 10 Sep |
Procook (AGM) Dekel Agri (AGM) |
Artisanal Spirits (Interims) Central Asia Metals (Interims) Finesta (Interims) Gym Group (Interims) Nexteq (Interims) Property Franchise Group (Interims) Social Housing REIT (Interims) Tooru (Interims) Warpaint (Interims) |
Adobe (Q3) Inditex (Interims) Kroger (Q2) |
Thursday 11 Sep |
Solid State (AGM) Trifast (AGM) |
Distribution Finance (Interims) Lord Group (Interims) Oakley (Interims) Playtech (Interims) RTW Biotech (Interims) Samuel Heath (Interims) |
|
Friday 12 Sep |
Adobe (NSQ:ADBE)
Unusually for a US large cap, Adobe's share price hasn't been performing well over the last couple of years, and is down around 50% from its peak:
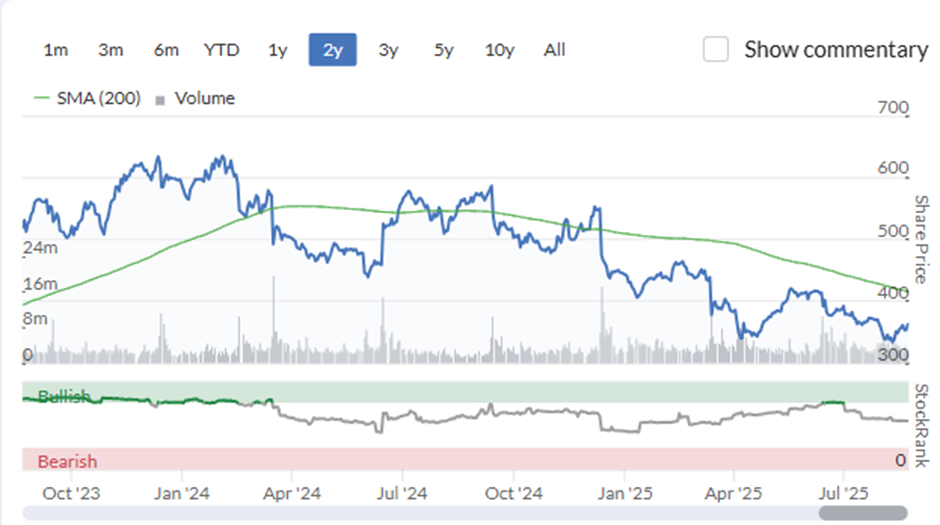
Yet the revenue continues to grow:
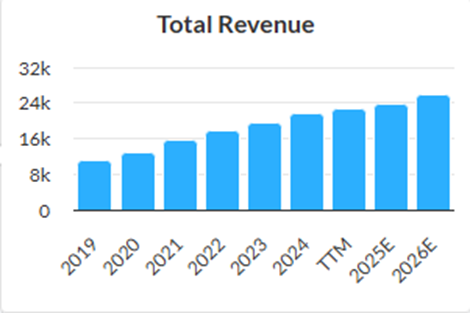
The Stock Report calculates 14% revenue CAGR, and with modest operational gearing, 17.4% EPS CAGR. Forward earnings are expected to trend above this rate:
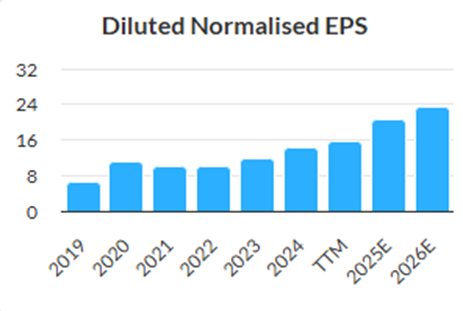
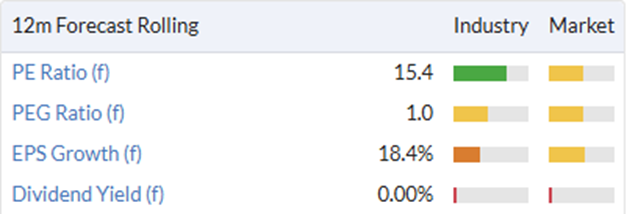
In light of this, the P/E looks relatively good value:
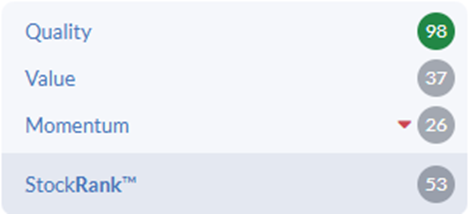
The overall Value Rank is not particularly impressive:
But this is an extremely capital-light business, and earnings actually lag a growing free cash flow:
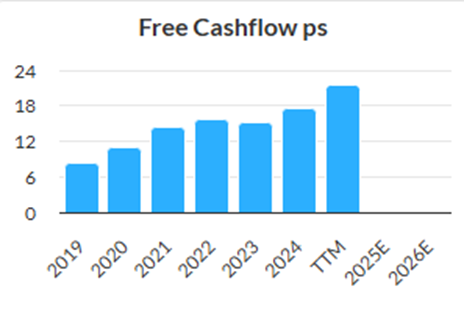

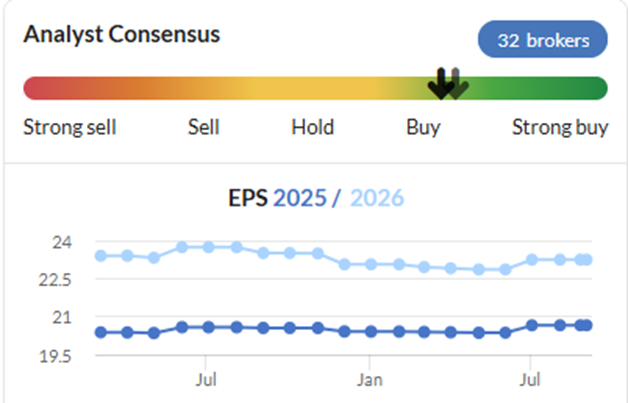
The dividend is zero as the company has prefered to buyback shares with that cash flow rather than pay dividends. Of course, the story here is that the market expects the company's flagship products, such as Photoshop, to be disrupted by AI. However, this has yet to be reflected in brokers' forecasts, which have not really shifted over the last 18 months:
In terms of results, the company has consistently beaten forecasts over the last year:
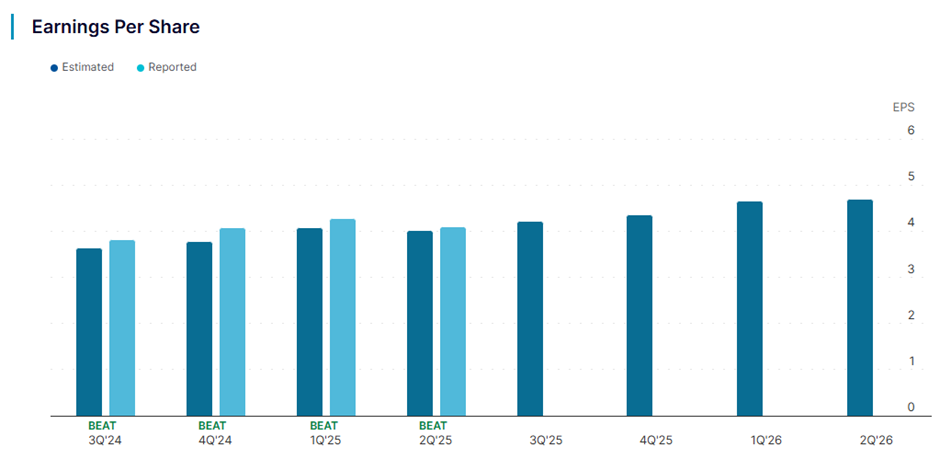
[Source: NASDAQ]
When the company reports Q3 earnings on Thursday, any further beat will make the company look exceptional value. Especially to investors, like myself, who think that AI productivity gains are equally likely to accrue to companies adapting existing strong products and extensive customer relationships, as to new start-ups.
UK Companies
Warpaint London (LON:W7L)
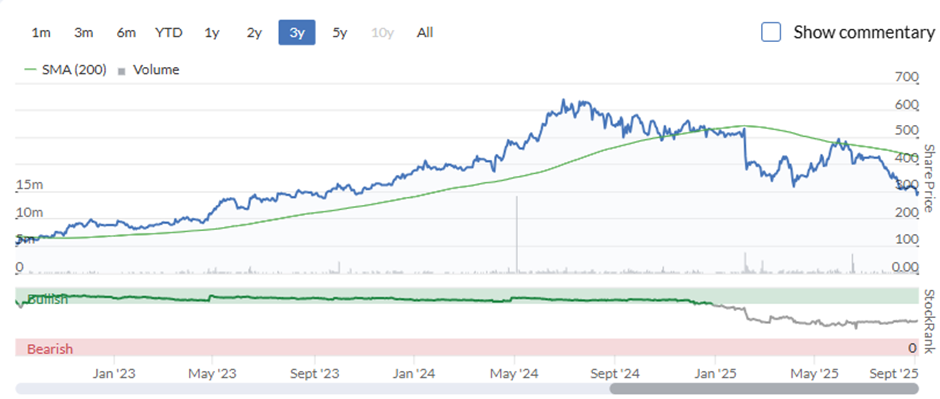
I expect the Warpaint interims on Wednesday to be among some of the most closely followed results in the subscriber community. Substantial revenue and EPS growth over the last few years led to a sixfold increase in the share price between the end of 2022 and mid-2024. This is during a time when most UK companies struggled. However, over the last year, the share price has halved, and it has been notable how weak the price has been in the run-up to these results, dropping below £3:
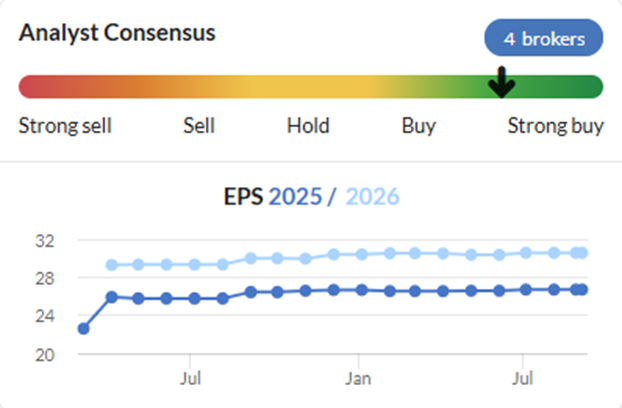
There has been no real change to broker EPS forecasts during this time:
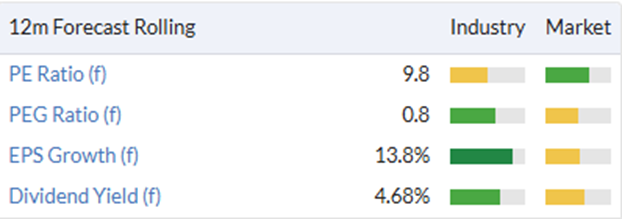
Meaning that the stock now looks relatively cheap on forward earnings:
However, the real question is, will they hit them? And here there has to be some doubt. The Stockopedia consensus is for 18.6% revenue growth and 12.4% EPS growth. When the company announced their 2024 results in April, they said that:
Excluding the contribution from Brand Architekts (from 12 February 2025), Group sales up 7% in Q1 2025 compared to Q1 2024
This is obviously far below the run-rate required to hit their FY forecast. In the June AGM statement, they said:
The Group continues to trade robustly with sales for the six months to 30 June 2025 expected to be in the range of £50 million to £52 million (six months to 30 June 2024: £45.9 million), including an approximate £5 million contribution from Brand Architekts.
And it was clear that this was below what they originally planned, saying:
The Group's revenue in Q2 has, as expected, been impacted by a slowdown in its US business, which remains a modest proportion of Group sales (2024: 8.5%), following the imposition of higher tariffs.
At 8.5% of sales, the US is still a relatively small part of the business, so I'm not sure this is the full story. However, they also reassured investors that they would hit FY forecasts:
Even more so than previous years, the Group expects sales for FY25 to be heavily second half weighted. This is due to the large number of planned product roll outs to additional stores in H2 as previously announced, together with a significant Christmas order book. There continues to be substantial growth opportunities for Warpaint and the Group is very well positioned to achieve further growth, with additional improvement in margins. Brand Architekts, acquired in February 2025, is now fully integrated into the Group and is providing additional and exciting growth opportunities. The board therefore remains confident that the Group will meet market expectations for the year ending 31 December 2025.
Brokers reduced revenue expectations in response but kept EPS forecasts the same based on higher margins. For example, Shore said:
Whilst our sales expectations are cautiously lowered, we confidently leave profit forecasts unchanged reflecting the strong margin progress already outlined above, with our model now pointing to a c.270bp gross margin expansion, which we believe is prudent relative to the current run rate. At the EBITDA level, we now look for a flat YoY margin, against the prior expectation of a c140bp dilution from BA.
So, there seems to be a lot riding on the upcoming results. The H1 revenue figure is already known; the unknown is whether they will reiterate FY guidance for both revenue and profits based on the continued expectation of an unusually strong H2. If they guide in line again and provide strong H2 trading figures so far to back that up, then we can expect a relief rally. However, if there is a profits warning, or the recent sales figures are unconvincing, then we can expect a significant sell-off. Warpaint remains an investor favourite, and any disappointment will not be taken lightly. My own guess is that they will miss revenue but make the EPS target based on higher margins. I'm not sure I'm brave enough to take a position ahead of these results, though.
Gamma Communications (LON:GAMA)
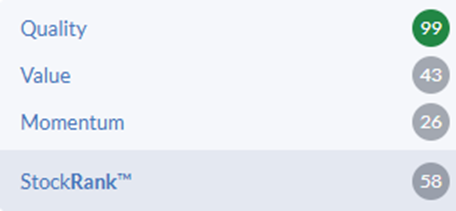
Gamma Communications is one of the highest quality-ranked stocks in the UK market:
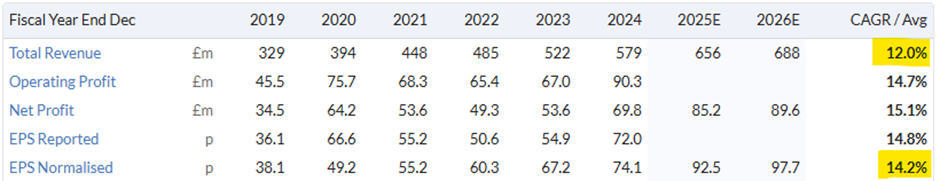
And you can see why with strong sales growth:
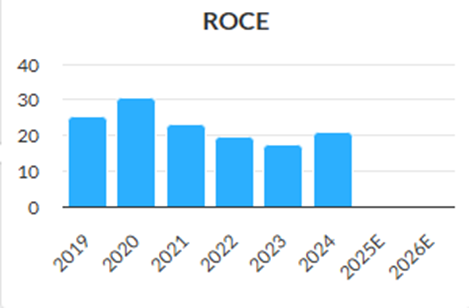
At a ROCE consistently above their cost of capital:
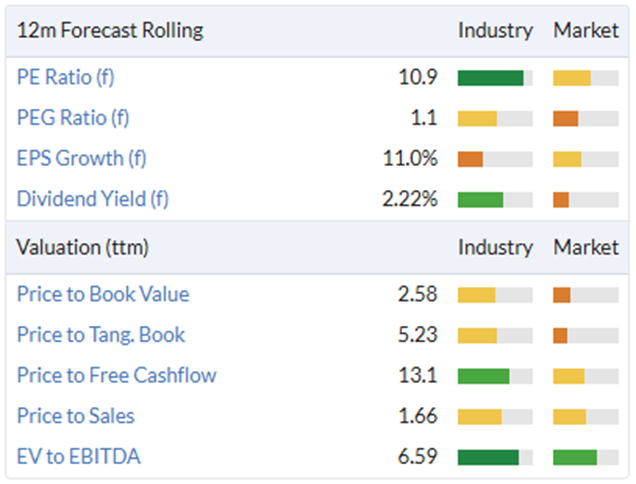
They are pretty cheaply rated, at least based on forward earnings:
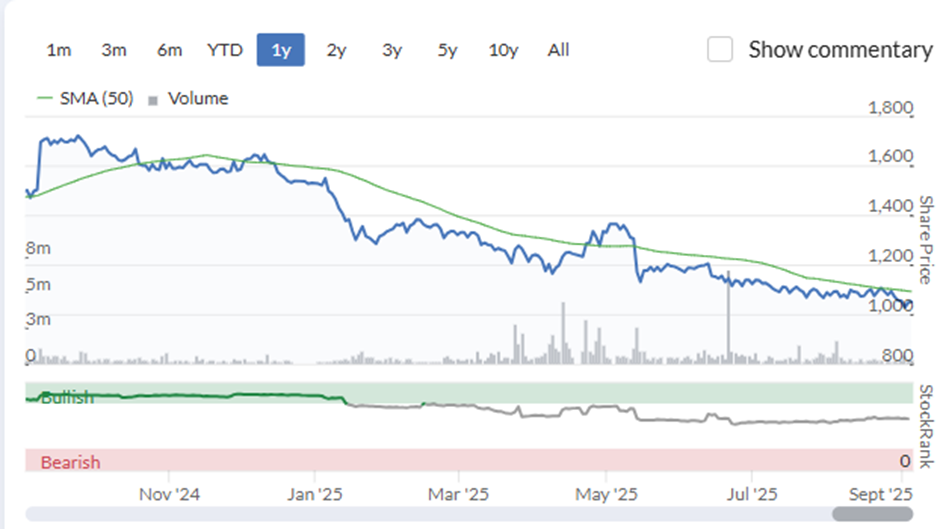
However, perhaps the market doesn't have much confidence that they will meet these given the recent share price performance:
Forecasts have been a little variable:
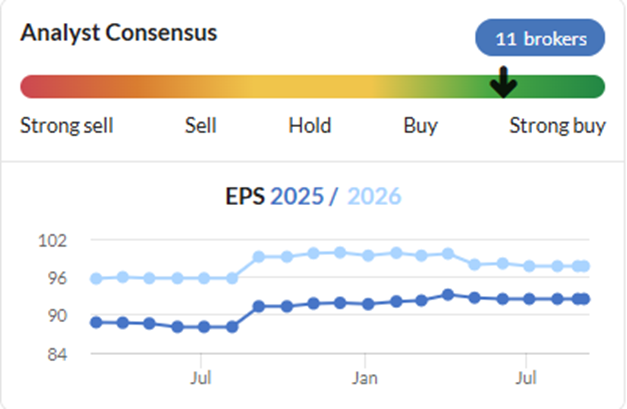
However, they are still above where they were 18 months ago. Part of this weakness may also be their move from AIM to the main market, which will have forced some IHT funds to sell. However, this effect should now be over. They provided a trading update with their AGM in May:
Based on our trading and cost actions in 2025 to date, the Board expects Adjusted EBITDA and Adjusted EPS (fully diluted) for the year ending 31 December 2025 to be within the range of latest market forecasts.
Which they helpfully give as:
Company compiled range is based on known sell side analyst estimates. The ranges are Adjusted EBITDA £139.4m - £146.0m and Adjusted EPS (fully diluted) 89.9p - 94.8p.
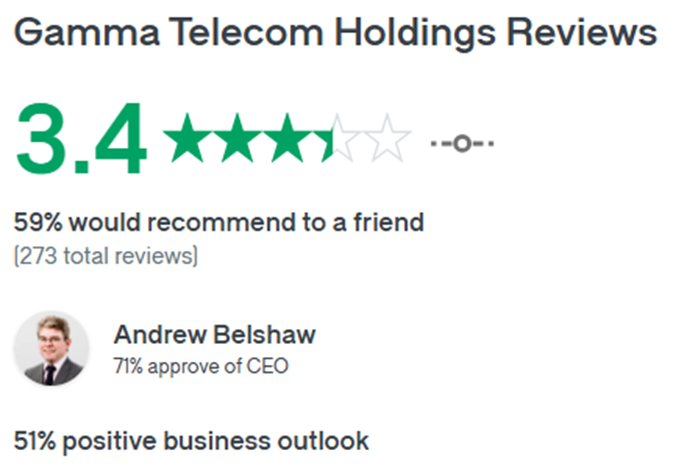
So there are unlikely to be any big surprises on Monday, and it is possible we'll see a relief rally. The only thing that gives me pause for thought here is how bad some of the Glassdoor reviews are:
Including this particularly scathing one:
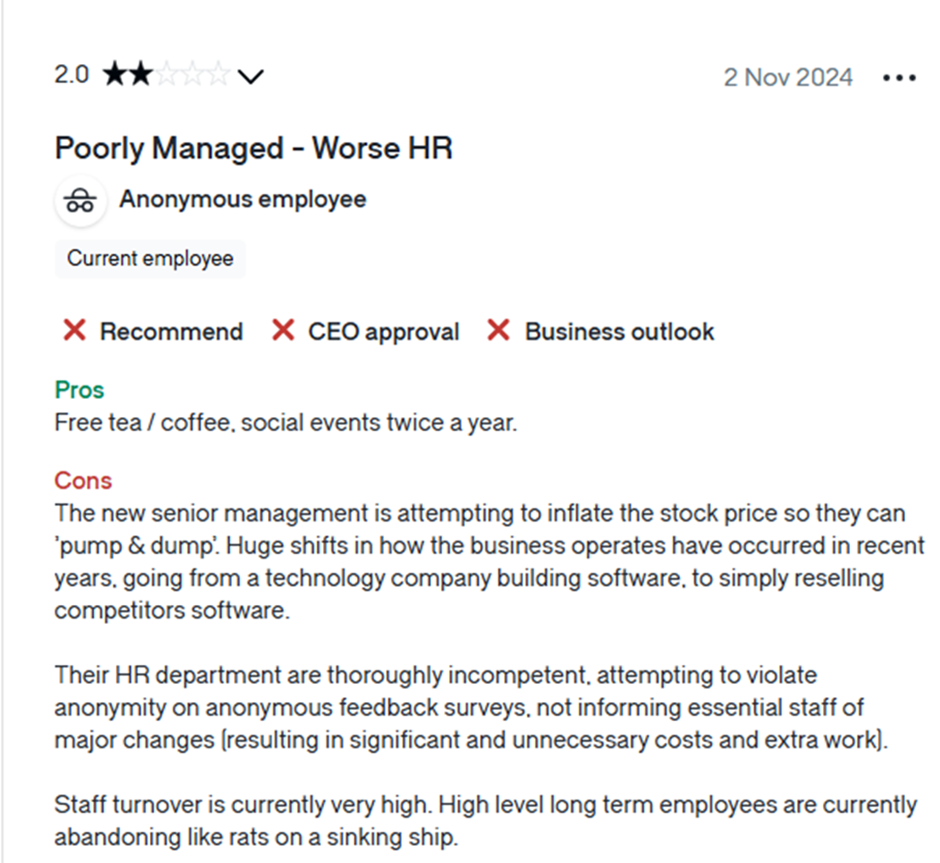
These may indicate long-term issues in company culture. Although the chances of these problems coming to the fore in next week's results seem remote.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Mark, I would just make one comment about Glassdoor. In order to read some of the comments on Gamma Communications I had to sign up and was not able to read comments until I had left a review of my experience with my employer. I am retired, so the review I wrote was completely fictional, some comments just a string of jumbled letters. So I think I would add a health warning to anonymous reviews. One I read in particular talked about management trying to pump and dump to get the share price up - a strange comment for an employee to write but perhaps not so strange if someone shorting the share was looking for ways of supporting their position, I obviously don't know. However, I have not seen any evidence to suggest that this particular management have tried to pump and dump shares.
Adobe (NSQ:ADBE)
I'm not sure AI is the real threat. Alienating your own customer base might be, though, if you discover your product isn't quite as essential as you thought and your moat runs dry.....
How material it has become I'm not quite sure, but there is growing resentment amongst some portions of the adobe user base. Adobe moved to annual subscriptions and increased their prices quite aggressively and people are beginning to push back.
Certainly from a photography/photoshop/lightroom perspective there are an increasing number of freeware/open source alternatives that are now sufficiently sophisticated to meet the needs of amateurs and enthusiasts. Photopea can even work with psd files (the photoshop file format).
Of course the commercial market has yet to embrace GIMP/Darktable etc, but there are "pay once" products out there like CaptureOne which are reportedly quite good.
Yes, Photoshop and Lightroom are probably still better, but perhaps not better enough to justify the price differential. I suspect Adobe may be living off inertia - if you are a busy commercial outfit the hassle of changing outweighs the cost advantage and it helps to have a common standard between firms, but as younger employees with more freeware experience move through the ranks that might change (or it may not, I'm not entirely sure). People now happily use Google Sheets in addition to Excel.
For editing film clips, audio and special effects just have a play with what you can do in the free version of Blackmagic's DaVinci Resolve. You really do have to be very advanced to consider paying for Adobe Premiere Pro (and Adobe may regret letting BlackMagic corner the amateur market, because amateurs become pros!)
Mark - thanks, this is a useful weekly article but it would be helpful if it contained a more comprehensive list of companies reporting. I don't know what source you are using but it is missing Mobico on 9th Sept and Anpario on 10th Sept to name just two that I hold. Frontier Developments is likely to report on 11th too, although not yet confirmed.
I have noticed omissions most weeks, even though companies have provided written confirmation of results release dates in RNS statements.
Hi Sparkler,
It would be great if we could always have a comprehensive list, but even using multiple sources, we often miss some, or when I check the list some are just wrong. I can guarantee that I am even more frustrated than you about this. If anyone has a source for this info they consider fairly foolproof then I'm all ears.
I think in the absence of better sources, the team at Stocko will work on having the ability to search their data from Refinitive, which would have caught some like the ones you mention, but may not be foolproof either.
And similar to when we miss news on the DSMR, feel free to add them here in the comments so they get spotted by readers.
Thanks,
Mark
The dates on Stocko. are often incorrect. Phoenix group (LON:PHNX) interims are out today not next Monday.
The UK market is frustrating, the US is much more structured.
Thanks, Mark. I have to confess that I don't know of any totally accurate sources. Maybe Stocko readers can help with errors and omissions each weak?