Thoughts on Asset Investing (or How I learned to Embrace Uncertainty)

The Purest Form of Value Investing
Net Asset Value (NAV) investing is probably the purest form of value investing. You find a company owning net assets which are in some obvious way worth at least X, and you pay considerably less than X to buy them. The discount is the opportunity, the larger the better, and the asset backing provides assurance of a very low risk of eventual loss.
Net Current Asset Value (NCAV) investing is more extreme: you consider the value of current assets only, allowing no value for PPE and other long-term assets, and continue to subtract all liabilities, both current and non-current, to estimate the net worth of equity.
These investment strategies fulfill the basic principles of value investing: they rely primarily on quantitative and objective evidence, not on subjective views or esoteric forecasts, and they take a safety-first approach to avoid incurring losses. On the assumption that the net worth of the company’s equity will not decline precipitously (this can sometimes be a heroic assumption), and that your entry price is at a sufficiently steep discount to the NAV, there is reasonable assurance that you should be able to “get your money back” with this kind of investment. The idea is that the company should at least be able to distribute something which is not very far from its liquidation value to investors, after taking into account exceptional liquidation costs and the operating losses which it occurs prior to liquidating.
Bitter Experience
Since my personal portfolio got properly underway in late 2012/ early 2013, I have made no less than nine NAV investments. Many other investments have been made which have been partly justified by NAV considerations, and partly justified for other reasons, but nine have been primarily justified by the discount to NAV.
Looking back on three years of data, despite good overall portfolio performance, I must admit that my NAV investing has been a financial failure up to this point. In hindsight, I underestimated the NAV discounts which were justified by the particulars of the companies in which I invested. In aggregate, NAV investing has not returned any profits for me whatsoever.
One thing I will say about NAV investing, though, is that it was a baptism by fire in terms of learning about all of the various ways in which a company can be poor quality. These include: conglomerate structures, obsolescent and failed business models, unreliable asset valuations, foreign control, intransigent management, unfavourable shareholder structures and the presence of off-balance-sheet liabilities.
Conclusion
My conclusion after three years and nine attempts is that NAV investing is not for me. I still retain one pure-play NAV investment for now (Northamber (NAR.L)), and all of my current and prospective investments are considered in the light of their asset backing. However, as Paul Scott rightly points out, a pure-play NAV investment is “dead money” until the catalyst takes place which realises value for shareholders. If you get a catalyst within a year or two, you can earn a great return. If the catalyst takes 3-5 years, the return is likely to be much less exciting. If it takes longer than 5 years, you could very easily find that you have underperformed the market index. The table below provides a reality check of annualised returns sorted by total return and years to realisation:
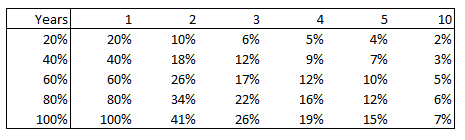
In summary, waiting for the NAV discount to close can be a thankless task (particularly if, like me, you underestimated the problems with the companies in which you invested). You need a good reason to believe that the catalyst is imminent, because waiting longer than three years will seriously affect your investment performance.
Comparisons with Fixed Income
There is more that can be argued against this form of investing as a matter of principle, for those of us with long time horizons and with the risk tolerance for business operations.
If you have a long time horizon (five years or longer, say), then does it really make sense to invest in a security which will only be successful if it matures in 2 or 3 years? You would hardly consider a two-year bond to be a highly attractive proposition as a cornerstone of your portfolio.
Furthermore, if you have the stomach to take on equity risk, then why would you allow your upside to be capped? If you are comfortable with equity risk, you would probably not be satisfied by the purchase of a discount bond for your portfolio. But it is rare for an NAV investment to be worth substantially more than net equity value.
The point is that NAV investing has much more in common with fixed income than with normal equity investing: it has a limited lifespan (the length of time until the catalyst), and the upside is usually capped (by the discount to NAV).
There is nothing wrong with that per se, but if you have the stomach for equity investing, then why compete with the more risk-averse and shorter-time horizon investors who are instinctively attracted to NAV investing?
I don’t regret my experience with NAV investing, but the experience has taught me to embrace equity risk, and that means not doing very much NAV investing in the future.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?