Time to buy great businesses at fair prices
Quality investing has been on a roller coaster ride over the last couple of decades. Coming out of the financial crisis in 2008/2009, value stocks performed well as investors realised that a strong recovery was underway and many stocks were cheap. However, by around 2014, quality compounders started to become the talk of the investing community, as well as the idea of "never sell" investments: those that were so good they would just keep generating above-average returns forever. However, as is so often the case in investing, popularity led to overenthusiasm, and investors couldn't distinguish short-term momentum from true long-term fundamental outperformance.
Many quality companies came out of the COVID blip ok and performed well into 2021. However, the inflationary period caused by post-COVID stimulus and the invasion of Ukraine led to a rise in global rates, and many previous stock market darlings struggled. In recent years, these trends have been exacerbated by AI disruption and another inflationary war. Many investors who built long careers of successful returns investing in Quality stocks, such as Terry Smith or Nick Train, were derailed by these shifts.
Perhaps the clearest embodiment of this cycle in the UK was the Buffettology Fund, started by Keith Ashworth-Lord in 2011. The fund built an exceptional track record from 2011 through 2021, roughly tripling investors' money and beating its benchmark by a wide margin, ranking near the top of its sector for most of that decade. However, in 2022, the fund lost 23% against a 9% sector decline, and the performance has been lacklustre ever since. The fund has underperformed the sector on a 1-, 3-, and 5-year basis and its size has fallen from around £1.5bn in 2021 to around a sixth of that today, reflecting both the weak performance and redemptions.
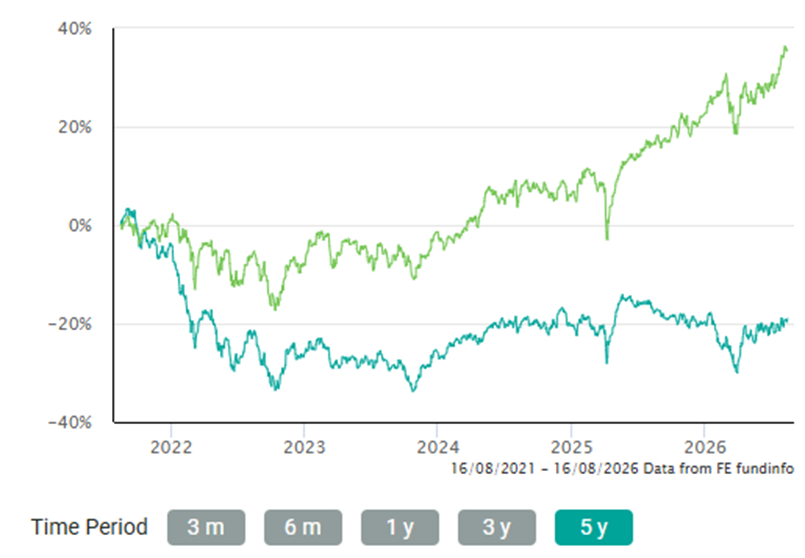
[Chart: Trustnet]
Stockopedia Quality Rank
The recent lack of performance amongst Quality stocks is also visible in the Stockopedia Stock Ranks. This chart shows the two-year returns of the different deciles sorted by Quality Rank:
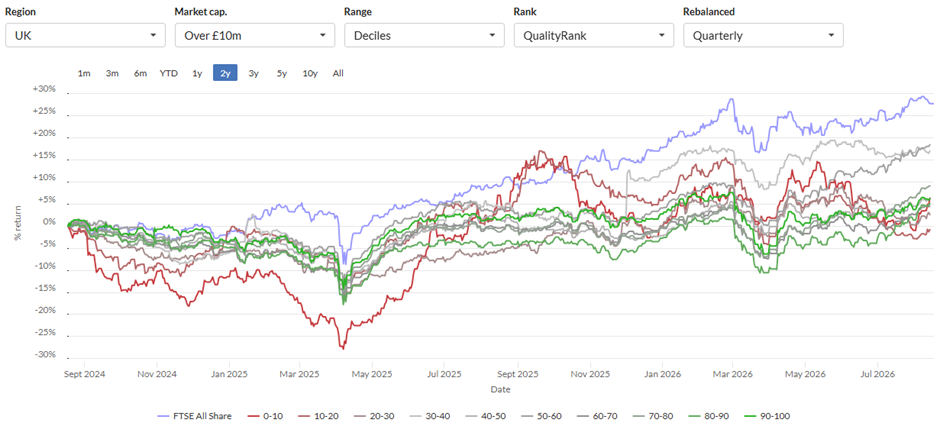
The first thing that stands out is that all deciles have underperformed the wider market because large caps have outperformed, meaning any equal-weighted portfolio would struggle. However, the most notable point is the clustering of performance within the Quality deciles over the last two years. The Stockopedia Quality Rank simply hasn't given a strong signal recently.
This is in contrast to the clear positive dispersion between the returns to highest Quality and lowest Quality sets of stocks over the last 10 years:
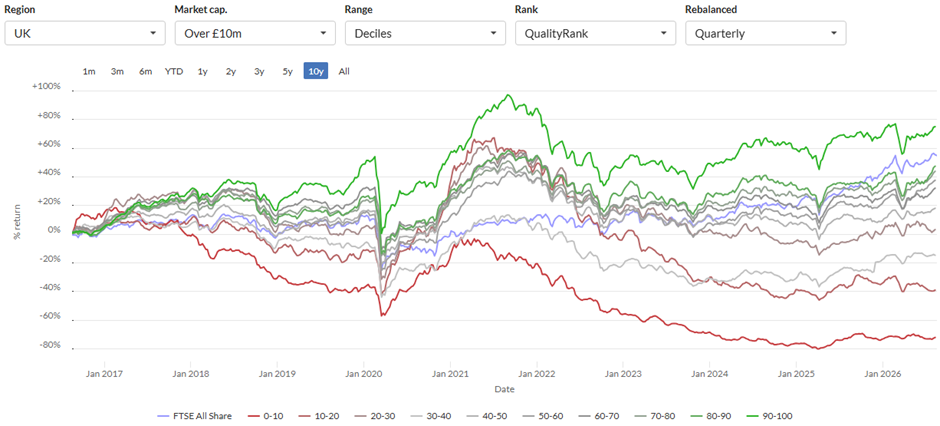
While no one knows for certain when Quality stocks will start to be favoured again, a multi-year period of underperformance suggests we may be closer to that point of reversal than we have been recently.
Quality Jumpers
Another sign that it may be time to focus on Quality is Ed's recent finding that the best-performing Super Stocks in his Stock Rank jumpers data were those that saw a significant short-term improvement in their Quality Ranks:
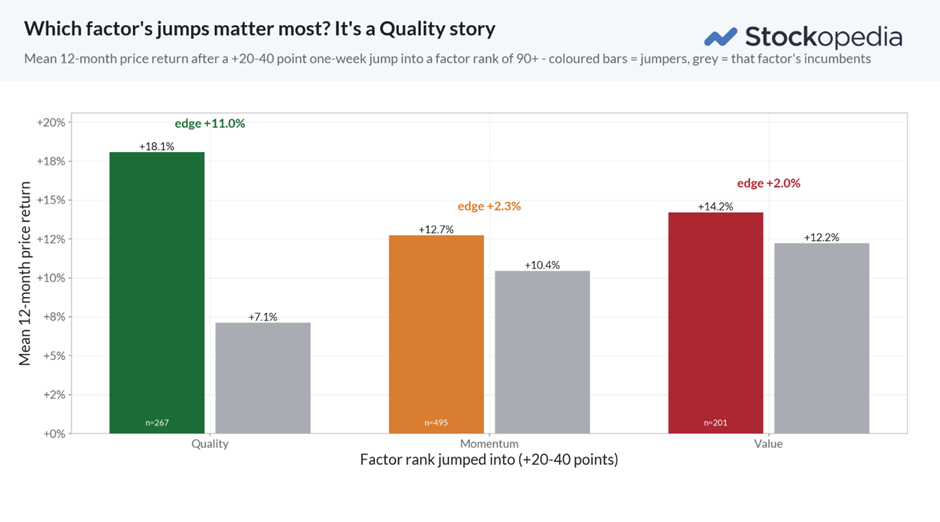
Investors who spot companies with improving quality metrics, in an environment where quality is increasingly valued, may generate great returns.
A Quality Framework
When considering Quality Stocks, my thinking is influenced not just by some of the well-known UK fund managers already mentioned, but by the GOATs, Warren Buffett and Charlie Munger. (I'm sure I'm not alone in this!!) Plus, Christopher Mayer's writings in the excellent 100-baggers book stand out among the published literature.
The fundamentals of this strategy boil down to the fact that trading businesses that generate very high long-term returns to equity holders tend to have the following characteristics:
- Moat: Not every company benefits from having a great idea or product. Too often, competitors enter, and the returns get shared among many. Great companies need a way to keep competitors out, known as a sustainable competitive advantage. This can take many forms: a secret recipe, technical know-how, patent protection, brands or network effects. The result is often known as a "moat" in investing circles – a protective barrier that competitors struggle to breach.
- Runway: In the studies of high-return stocks, almost all get there by generating high sales growth. They have products or services that are in increasing demand. However, you can have some great companies, but if their market is already saturated, they have little room to grow. Their moat gives them little advantage.
- Operating Leverage: High sales growth is good, but returns really improve when the bottom line grows faster than the top line. This typically happens when the cost base is relatively fixed, so increasing sales drop mainly into profits.
- Cheap: Finally, if investors can identify these types of stocks early enough that they aren't already paying a very high multiple, they benefit further as the market starts to spot and price in the growth potential and the multiple re-rates.
I think of the moat, operational leverage and cheapness factors as levers. The best returns come from being able to pull most or all of these simultaneously. Runway is harder to define, but thinking about it helps you avoid a stock with great metrics that can't take advantage of them by growing its sales.
Screening for potential high-return stocks
The good news is that we can screen for three of these MROC factors:
- Moat: Consistently high returns on invested capital or equity tend to mark out companies with a strong competitive advantage. Because these figures tend to be mean-reverting and depend heavily on profit, investors should look beyond a single good year and find companies that show consistently high returns on capital, or, better yet, high and increasing returns on capital. Invetsors need to be wary of certain types of businesses when using these metrics. People businesses can often have high returns on capital, but the real assets are the people, and they aren't on the balance sheet! Similarly, extractive industries tend to be cyclical, so a high return on capital is more likely to indicate a commodity boom than a sustainable competitive advantage.
- Operating Leverage: One of the most controversial findings of the 100-baggers book is that investors should look for high-gross-margin stocks with low net margins. The idea is that the profit potential of such a business may be obscured to many investors by the low current net margin. However, if sales growth materialises, the high gross margin on a relatively fixed cost base would drive a rapid improvement in profits.
- Cheap: The valuation multiples investors are willing to pay may be higher than a pure value strategy. We are after great businesses at a fair price, after all. However, we should still have some limit so that we have the potential for multiple expansion to drive higher returns than profit growth alone.
Sadly, I haven't found a way to screen for Runway, so this needs to be more of a manual sense check post-screen.
Screen Criteria
Here is how I have attempted to screen for these types of stocks:
Moat:

I've not specifically screened out people businesses, as that is hard to do without false positives, but this should be a manual check.
Operating Leverage:

Cheap:

Size:
We tend to restrict ourselves to writing about stocks above £10m market cap on Stockopedia for liquidity reasons. I also think it makes sense to exclude mega-caps, as their growth potential is clearly constrained. A cut-off of about £2bn market cap is arbitrary but feels about right.
Screen Results
The screen currently generates 12 results:
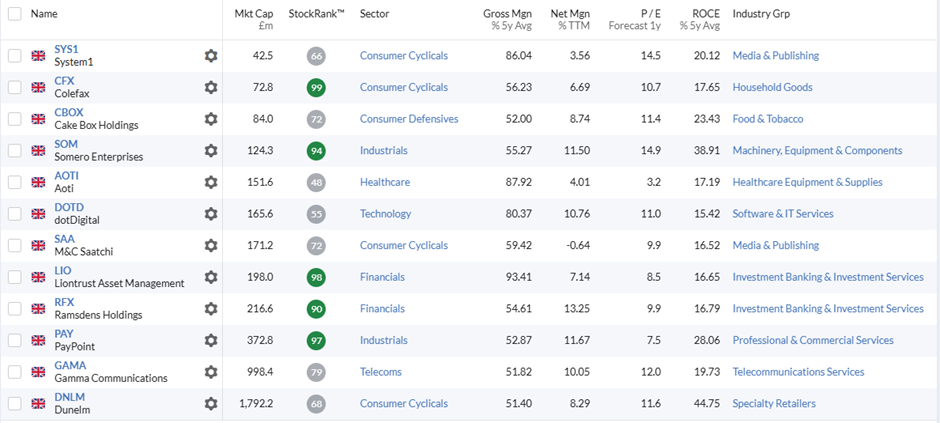
Interestingly, the screen highlights three companies that are currently attractive to acquirers. Ramsdens Holdings (LON:RFX) has an agreed takeover, so we can ignore it. Gamma Communications (LON:GAMA) is also in takeover discussions but has no firm offer, so it's still worth considering. System1 (LON:SYS1) has an offer in place from major holder Brave Bison, but the board has rejected it.
The list
Here's a quick introduction to the stocks:
System1 (LON:SYS1)
This company, which assesses the effectiveness of marketing campaigns, grew very rapidly for a while. However, the costs of developing new products, combined with marketing industry weakness, led to a couple of severe profit warnings and the share price collapsing:
Since then, the founder swapped his shares for a holding in Brave Bison, which has since made an offer in shares and cash for the rest. The board has rejected this, so it is likely to remain independent.
Brokers are now forecasting a big recovery in 2027, and given the bid defence, the board will be under pressure to deliver:
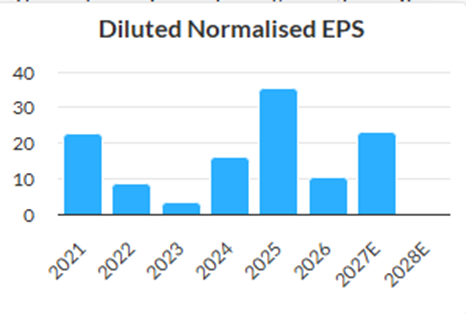
The rather patchy delivery makes EPS much more volatile than shareholders would ideally like to see. However, the high gross margin means it wouldn't take much sales growth for this to look very cheap again from the current levels.
Colefax (LON:CFX)
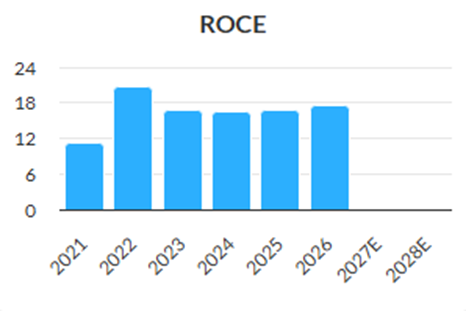
This company has performed remarkably well in current market conditions for a designer and distributor of furnishing fabrics and wallpapers. The returns on capital suggest that its designs provide a moat:
However, growth has been steady but rather lacklustre:
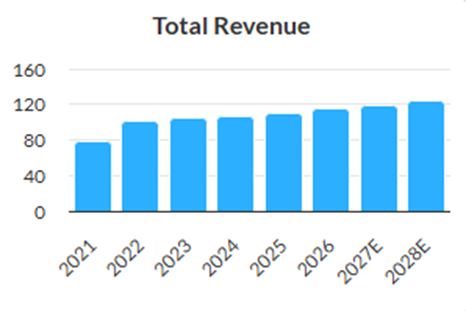
It has a rather quirky capital allocation policy, paying minimal dividends and then occasionally doing low-premium tender offers. There are not great signs that they can deploy additional capital to accelerate earnings growth.
One could argue that this remains undervalued, but I'm not convinced this is the type of high-return company we are looking for.
Cake Box Holdings (LON:CBOX)
While it may have declined in recent years, the ROCE on this celebration cake producer remains above its cost of capital:
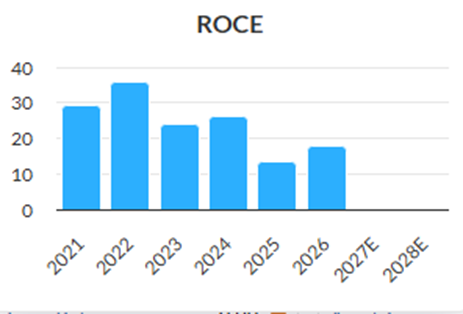
My instinct says that their market may lack Runway. After all, how many cakes can a nation increasingly taking weight-loss jabs consume?! However, at 22%, the revenue CAGR is strong and shows little sign of slowing down if brokers' forecasts are to be believed:
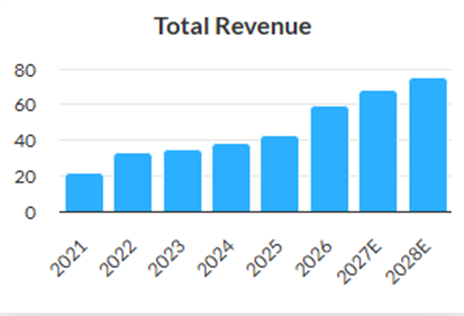
So far, there is a lack of operational gearing, meaning the EPS CAGR is a much less impressive 9%. So the case for being a high return stock probably hinges as much on the ability to keep costs under control as on the overall runway potential.
Aoti (LON:AOTI)
This is a relatively new float I haven't come across before. The revenue CAGR looks strong at over 30%, but I'm just not convinced by the forecast figures from this wound-care technology provider:
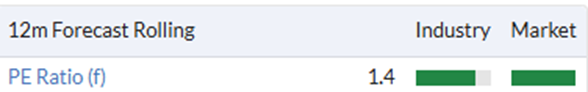
Looking at the note from their broker, Panmure Liberum, I see they have $2.7m PBT pencilled in for FY26E, versus $3.1m for FY25A. This confirms my suspicions. They are not cheap.
Somero Enterprises (LON:SOM)
Having followed this company for many years, I find its ROCE hugely impressive. While this was lower last year, it was largely a function of a weak year and will bounce with stronger future profitability:
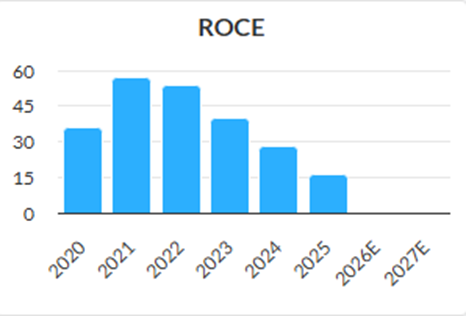
However, my on-the-ground research leads me to believe the moat is largely brand, rather than any technical advantage. Indeed, I think they may now be too far behind the curve in Europe on factors such as battery power and metric sizing for this to be a key market again.
Their various innovations over the years have failed to gain any significant traction compared to their core North American Boom screed sales, which means revenue has been flat to declining:
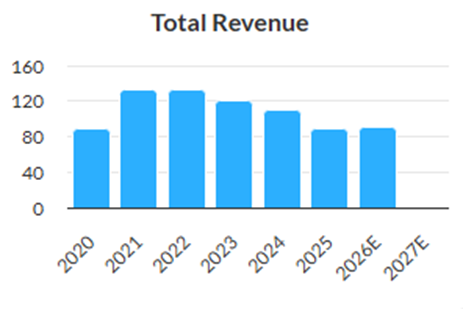
While there may well be some sales recovery yet to come at this point in the cycle, I just don't see this growing sales or being able to deploy additional capital at historically high rates in order to be anything other than a recovery trade.
dotDigital (LON:DOTD)
Of this list, this is the one I hold personally, having picked up a position after it appeared on a screen I created looking for cheap growing companies. I subsequently wrote a Stock Pitch on the company to check what I may be missing.
The ROCE is following a worrying trend:
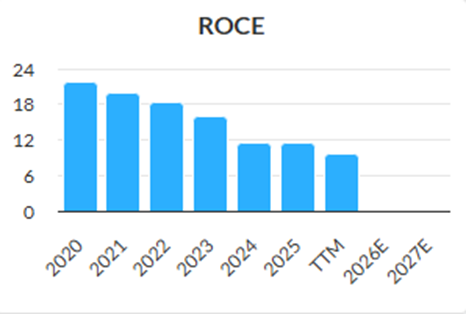
However, this is largely due to acquistion accounting, where goodwill is sitting on the balance sheet, and the earnings from the fast-growing companies they are acquiring, with stated cross-selling opportunities, are yet to be seen in the numbers.
Revenue growth is reasonable at 12% CAGR. However, acquisitions have played their part in that:
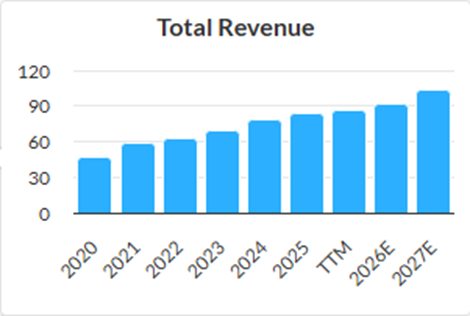
I don't think there is any lack of Runway for their direct marketing tools; the bigger concern is how big their moat is versus competitors' products.
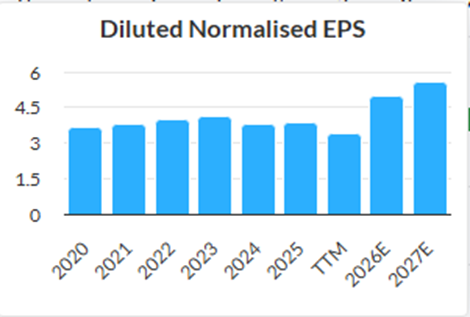
A lack of operational gearing is also a concern, but one that will probably be assuaged if they can deliver on current broker forecasts:
M&C Saatchi (LON:SAA)
While the ROCE is reasonable in the good years, there is significant inconsistency between years:
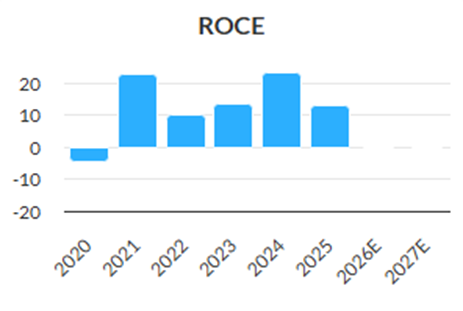
Overall the numbers aren't great, especially as this has some aspects of a people business. And neither revenue nor EPS shows any real growth over the medium term.
The forward multiple is relatively modest, but perhaps not stand out for the sector:
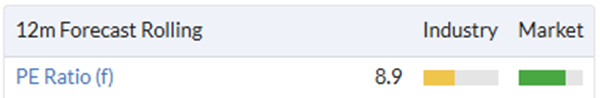
This may make it a good recovery play, and I know it has fans among some well-regarded value investors. However, on the surface this doesn't look like the kind of quality compunder we are looking for.
Liontrust Asset Management (LON:LIO)
This is exactly the sort of quasi-people business where ROCE doesn't really measure moat. They undoubtedly have a well-known brand, but this hasn't stopped them from facing large redemptions like the rest of the UK fund management industry. This may yet prove to be a great recovery play, but it isn't the sort of quality compounder we are looking for.
PayPoint (LON:PAY)
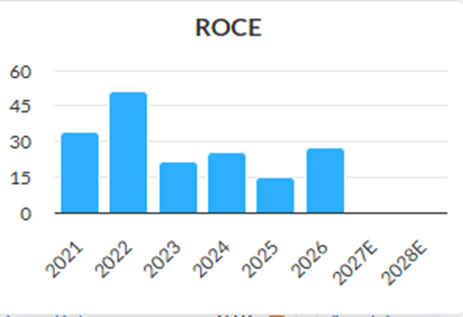
In most years, Paypoint has a high ROCE:
However, EPS has been somewhat variable:
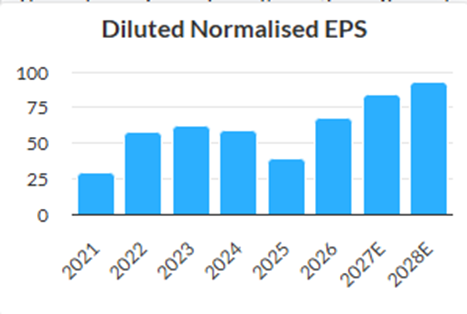
EPS is forecast to grow strongly going forward, which puts the company on a modest forward P/E.
This is a recent Stock Rank jumper:
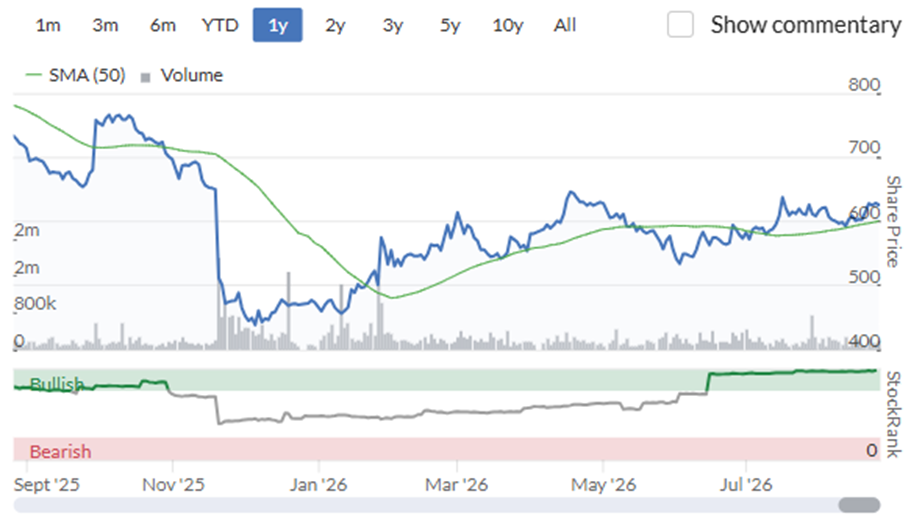
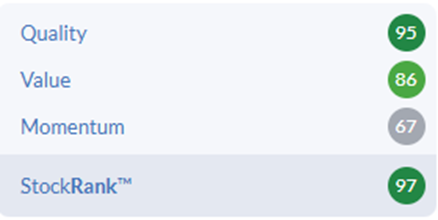
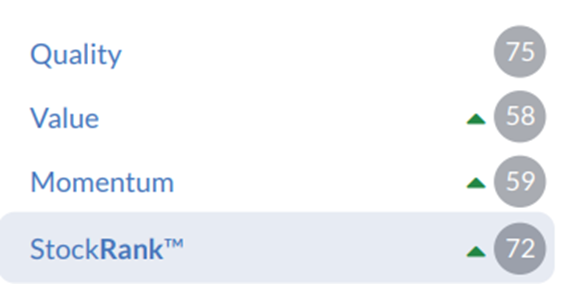
And driven by a jump in the Quality Rank, which Ed showed to be the strongest historical signal:
Today:
June 7th:
In the past, I'd say this company struggles with the Runway available to it. After all, payment terminals in corner shops are likely to be a saturated market. However, the company has successfully diversified into wider EPOS systems, as well as parcels and open banking. This last area has strong growth potential.
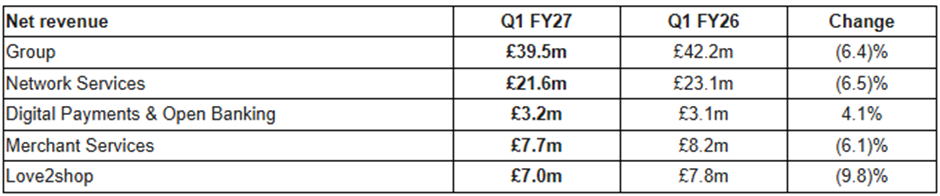
However, I am also cautious about the company's short-term outlook. In their recent Q1 results announcement, they said they were " on track to meet market expectations for FY27". The problem is that the numbers show Open Banking remains a small, low-growth part of the business, while everything else declined significantly. These figures may presage a profits warning to come:
Gamma Communications (LON:GAMA)
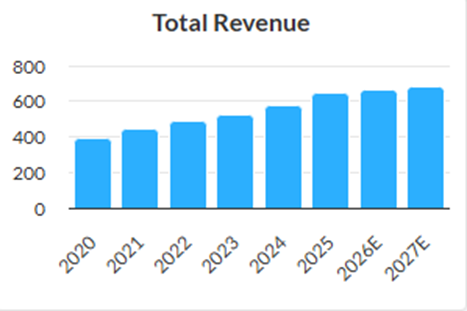
Gama has shown decent revenue growth in the past, although aided by acquisitions:
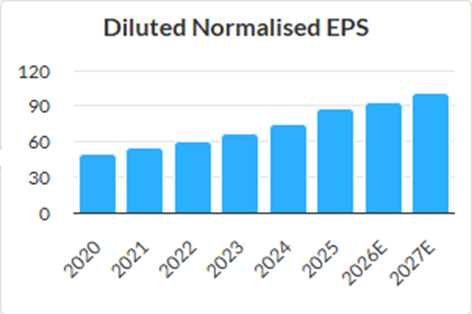
And some modest operational gearing:
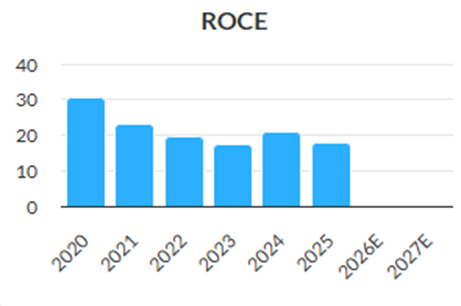
Their ROCE is consistently above their cost of capital too:
The challenge is that revenue growth is forecast to be quite lacklustre in the next couple of years. If this is a blip caused by market conditions, this could be a great time to buy this sort of business for the long term. The biggest risk may be that if there is enough evidence of a recovery, the private equity bidder will benefit from that return to form, not shareholders.
Dunelm (LON:DNLM)
Dunelm's returns on capital are simply great:
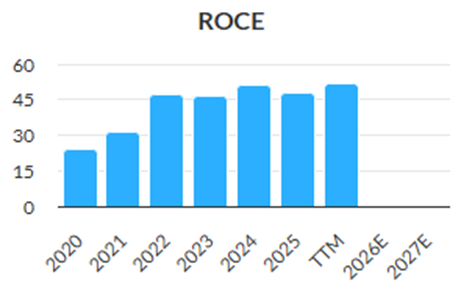
Historically, they have managed to generate some decent revenue growth:
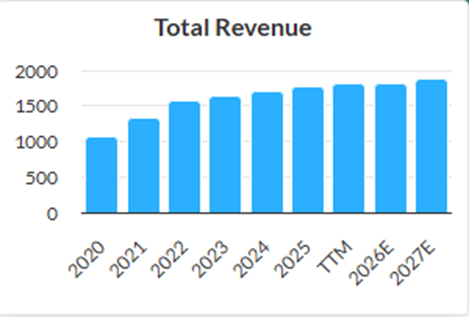
And with some modest operational gearing.
However, all that growth was from 2020-2023:
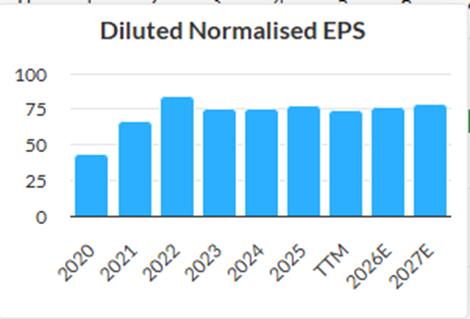
EPS has gone nowhere since, and it's not forecast to improve anytime soon. There are some very genuine reasons to think this is temporary, though. Homeware sales are linked to housing transactions, and the UK housing market has been particularly weak over the last few years.
Retail is a competitive market, and gains will only come at the expense of others. However, this doesn't mean there isn't scope to grow. It may just be a long wait for housing market sentiment to help.
Screening is, of course, a blunt tool. Let me know in the comments which of these you think may be quality compounders and why.
Similarly, if you think you have a company that meets the Moat, Runway, Operational Leverage, and Cheap criteria that I've missed then let me know.
[Disclosure: Mark owns shares in dotDigital (LON:DOTD)]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Mark, really interesting and informative article. Thank you. Has resulted me in spending time delving into some of the companies identified.
When I read the headline of this article I thought it might be focused on some of the world leading US tech stocks that have been massively de-rated recently, due to the supposed threat of AI disruption.
Salesforce,. (NYQ:CRM) rose 23% yesterday after results, trading on a P/E ratio of only 13 - super cheap based on its current growth rate and quality factors.
Atlassian (NSQ:TEAM) has doubled in a month or so having dropped to a similar multiple at one point. I've also made a good return on Expedia,. (NSQ:EXPE) .
Autodesk,. (NSQ:ADSK) is on my shortlist.
In the UK I think London Stock Exchange (LON:LSEG), Experian (LON:EXPN) and Rightmove (LON:RMV) could be interesting. But their current growth rates are lower than many of the US options.
I'm shopping in the US mostly, at the moment. The UK market is unfortunately becoming a much smaller and more stagnant pool than it was 10-15 years ago, due to the endless takeovers and overseas re-listings of decent businesses... and the complete lack of IPOs to replenish the market.
When I read the headline of this article I thought it might be focused on some of the world leading US tec
why would you presume that - this is a mostly a uk facing site to the extent that the us company data is paid for added extra that most subscribers probably dont access.
not sure if its simply some sly dig here or your expectation not matching the reality of what the site is and does and that is clealry its mostly uk facing stuff?
i get it about us opportunities existing - no one is saying that there are not good if not better us opportunities though when they are simply concentrating on uk data - its simply clearly a focus on the uk market and that should not be unexpected on this site.
Hi rmillaree & Chris B
Those who are interested can always make a copy of the screen and expand it to global stocks with a single click. If I move the upper market cap limit to say £20bn to reflect the higher global scale, then I get 155 posibble companies.
Interestingly, places like Japan and the Nordics look to be over-represented and the US under-represented compared to the proportion of global capital. This matches much of the high-return literature that suggests that the most followed markets such as the US don't tend to be the best hunting grounds.
I have no expertise in Japanese stocks, though. So I'll leave you to do the introductory scan on the potential of these!
Uk totally awful now. Going to exit completely soon I think
Very interesting read. As often happens the screens don't necessarily throw up the best opportunities. In terms of quality at an attractive price I'd be more inclined to look at the likes of LSEG, RELX, EXPN (yes these are all Nick Train shares but look goos value to me) or perhaps even AZN.
Hi Mark, why is the Net Mgn TTM < 15% rather than greater than 15%? I would have expected you would want to screen for businesses with a high net and gross margin?
Hi Daniel,
I agree this is counter-intuitive, but is exactly what the research into very high-return stocks shows.
Sales growth in a company with currently high gross margins and low net margins will generate much higher EPS growth (assuming the gross margin on additional sales remians high and there is a relatvely fixed SG&A base).
Take this highly simplified example:
If you can find a company with a 60% GM, 10% EBIT margin that doubles sales on a fixed SG&A then EBIT will go up sevenfold (and with multiple expansion you could probably do 10-20x in the stock. However, join for aanother doubling where the net margin is 35% then you's only do 3x on EBIT and maybe 5x on the share price.
Both are great returns and require you spotting a compnay that has the ability to generate rapid sales growth. However, in the first case you'll get materially better returns.
HTH
Great thread Mark - top stuff
Very impressive and balanced analysis Mark and a stark contrast to the posts on some other websites.
Thanks Mark. Really interesting and particularly useful to get a contrary view on colefax ( Colefax (LON:CFX) . With a stock rank of 99, a recent jump in the quality rank ( +12 over last 30 days) which followed end of July results confirming a third ‘ ahead of expectations’ announcement this year ,and qualification for three long screens, I recently took a position. The company suggest that the main risk going forward is any major correction in the US stock market as their main luxury US market is dependent on continuing strength there. I note that the share is also quite illiquid with quite large spreads. I have red many predictions of impending doom for the U S market in recent years. Until there is strong evidence of that starting to happen I think that a position in Colefax (LON:CFX) is a good investment.
Hi jimrog64,
I don't think it's necessarily a bad investment. They are clearly managing to generate some good bottom line figures, and are not expensive. Just that there isn't clear signs of the ability to grow revenue strongly, which is the missing piece for generating high long-term returns. Perhaps they'll surprise me to the upside. However, broker forecasts are not particularly encouraging in this respect and are still for EPS to decline slightly despite recent upgrades. As such I struggle to conclude its a great MROC stock, even though it may be a good Momentum play in the short/medium-term.
Good luck with it!
It is an interesting and painful irony in investing that a genuine edge or factor that gives outperformance needs to experience periods of underperformance for it to continue. The reason that brilliant long term investors can and do get humbled on a regular basis.
In contrast something that always works will be arbitraged away because everyone will pile into it.
This is just a fancy way of saying that nothing is risk free.
The key of course is to work out if that style is in a period of outperformance or underperformance. Very important but also very difficult to do.
My general opinion is that we are going through a period of transition. This would favour a low risk attitude. I personally think commodities and basic industries will do well along with value propositions. Some quality attributes should also shine.
Thanks for that analysis Mark. For one who is new to investing and cannot read a balance sheet I find this very helpful. I'm always looking for simple uncomplicated systems to look for potential growth stocks while they are cheap. I will certainly use your MROC system in my searches. I also find Stockopedia essential in my quest to grow my small amount of capital. Many Thanks.
A good read Mark with sadly few gems in the sluice box, if any. It does however remind me that a significant portion of my recent returns have been derived from takeovers. Thanks for your efforts. I hold CFX, DNLM, DOTD,RFX.
Wonderful work that focusses attention on 'likely lads'. All I need now is a leap of faith!
Thank you Mark, great article and in conjunction with Ed's 'jump' article/screen this dovetails nicely.
Just a thought as I was reading, to capture 'runway' what are your thoughts to use positive eps growth over a 3/5 year period as a screen?
I note your use of PER to capture cheap stocks, would the use of PEG (say less than 1.5) in addition to PER add value to the screen objectives or just muddy the waters?
Thanks flashing blade.
It could be a way of screening. However, I prefer to think of runway as a less quantitive factor. While past growth may be an indicator of runway, it is probably better to think what the potential of each company is rather than restrict the list. If the screen was generating 100+ results, I'd almost certainly want to include some kind of extra screen factor, but with 12 I think a manual check is acceptable.
Interstingly, the PEG for most of these companies is less than one. However, the problem with PEG is that there are so many different versions, and it is more susceptible to a one-off strong year, or a variance between historical normalised figures and forward broker adjusted figures. If I take a simple PEG TTM < 1 instead of P/E <15, I actually get a very similar list with a few exceptions.
What about Spectra Systems (LON:SPSY)
I think it has a lot of positive qualities, and I hold. Indeed, it only falls down on the net margin part of this screen:
I think this probably limits the operational gearing aspect of the business somewhat. But if they can actually deliver the promised growth (especially if they win a major polymer bank note printing contract) they will do very well regardless.
I tried doing kind of similar screen a while ago considering Rafi metrics and volatility, worked ok so far
Also a screen like this to try and id companies with moats. Nb both screens iterated with AI