TP ICAP: cheap, harshly punished, and the setup is improving

I've watched TP Icap (LON:TCAP) from a distance for a year or so without ever buying it. It’s fair to say I’ve missed some strong returns as an observer, but that doesn’t mean I’ve missed the opportunity entirely.
It’s an excellent quant stock – a StockRank of 93, with a Momentum score of 93 and Value score of 73. It’s also a strong proposition from a qualitative perspective. Adjusted EBIT hit a record £196 million in H1, rate uncertainty and a possible energy volume recovery are tailwinds, and the shares have pulled back from their highs.
The Pitch
TP ICAP is the world's largest interdealer broker, sitting between banks and asset managers in over-the-counter markets and taking a clip on the trade.
It also owns Parameta Solutions, a high-margin data business, and Liquidnet – which lets large institutional investors (like mutual funds and pension funds) buy and sell stocks and bonds in large blocks, anonymously.
For me, the thesis is a simple one.
The shares trade on 8.9x forward earnings with a 6% yield covered 1.85x, and estimates for both 2026 and 2027 have risen over three months.
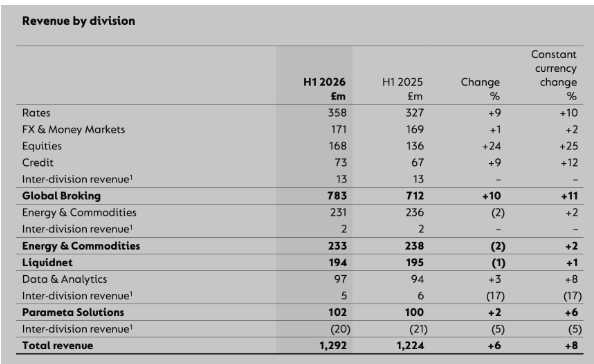
Global Broking – 61% of revenue and two-thirds of divisional profit – grew profit 22% on 11% revenue growth, and elevated interest rate uncertainty keeps those volumes coming.
And Energy & Commodities, the division that was blamed for the sell-off, is 18% of revenue and contributed £12 million of profit against £27 million a year ago. The impact may be overblown.
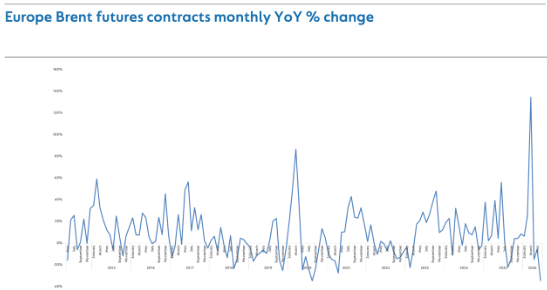
Source: TP ICAP H1 Results (ICE Futures Europe, historical volumes futures contracts)
The Big Picture
TP ICAP isn't just a volatility play; it's a volume play. The two usually move together -- but they can come apart, and this half they did.
The same Middle East conflict hit the business twice, in opposite directions. Global Broking, in rates and FX, needs price uncertainty. It got plenty. Revenue grew 11% and profit 22%, which the company credits to execution and cost discipline alongside supportive market conditions.
Energy & Commodities needs physical oil moving in order to have something to hedge. The company's wording: oil futures volumes “reduced significantly following disruption to physical oil flows as a result of the conflict”.
Two things drive this from here, and they are independent of each other – that’s my take anyway.
The first is the Fed. Kevin Warsh took over in May and has moved to scrap forward guidance in favour of pure data dependence, and focusing on the number on the left side of the decimal point (2%, 3%, etc., rather than basis points).
Strip out the signalling and the market has to price policy off the data itself – that should mean more repricing, more hedging, and more volume, in turn driving up TP ICAP’s volumes and fees.
The dot plot is drifting up, Trump wants it down, and that tension has to be traded. That is Global Broking's core market and 61% of group revenue.
The second is oil, and it’s less certain.
The Energy & Commodities division needs cargoes moving, and, perhaps overly optimistically, I believe it’s only a matter of time. In the Gulf, both sides look to be tiring – one low on missiles, the other low on cash -- but two reopenings have already failed this year.
Going Deeper
Group revenue rose 8% to £1.29 billion in the half and adjusted EBIT 9% to a record £196 million, with the margin edging up to 15.2%.
Chief executive Nicolas Breteau credited Global Broking's 22% profit growth to “the strength of our franchise and the operating leverage we have built”. That phrase is the one to test, because it is the whole investment case.
The operating leverage is real: Global Broking revenue rose 11% and profit 22%, lifting the margin from 18.4% to 20.3%. Front office costs grew in line with revenue -- brokers are paid on production -- but management and support costs were held flat. Growth was broad-based across Rates, Equities and Credit rather than one specific desk, and broker productivity rose 7%.
This is the division that matters: Global Broking is 61% of group revenue and, before corporate costs, about two-thirds of divisional profit. Whatever happens elsewhere, this is the business you are buying.
The cost programme landed a year early. Management now expect at least £50 million of annualised savings by the end of 2026 against a 2027 target, “exceeding our savings target and achieving it a year ahead of schedule”.
Energy & Commodities is a drag that should lift: Margins fell from 11.3% to 5.2%, taking profit from £27 million to £12 million. Some of that is the oil volume story and should return with normal physical flows. But the company is clear that the margin also “reflects this ongoing investment” in new freight, agriculture and nuclear fuels desks, and guides to improvement “over the medium term”. This looks like an area for a recovery.
Credit is the growth push: TP ICAP launched RealQ in June, a credit trading and data platform built from its own dealer data and buy-side network, and bought Vantage Capital Markets to widen its equities and credit reach across Asia, Europe and the US.
Valuation
8.9x forward earnings, PEG of 1.1: Worth noting that this is on adjusted earnings. Reported EPS was 24.2p in 2025 against 30.4p normalised, and another £80 million of significant items is guided for 2026. On reported numbers you are paying closer to 12x, which is by no means expensive.
A 6% yield, covered 1.85x: The cover is what has changed. In 2017 the payout was covered just 0.66x, having been frozen at 16.9p for six years, and it was cut outright in 2020. Today's dividend isn’t larger in pence terms but is far better funded, under a policy of returning 50% of adjusted earnings.
Buybacks are compressing the count: £110 million so far in 2026, some £660 million returned since 2023, and the average share count down 2% year on year.
Treat the balance sheet metrics with care: The screens show net cash of £5.0 billion and an enterprise value of minus £2.65 billion, which sits awkwardly beside book value of £2.0 billion. Interdealer brokers run vast matched principal and settlement books, and the data, I presume, reads the asset side as corporate cash.
What The Brokers Say
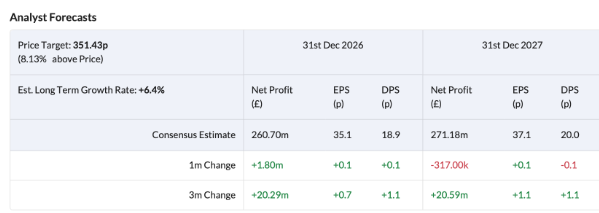
Six brokers cover the stock with a consensus target of 351p, about 8% above the price. Add the 6% yield and that is a mid-teens total return -- respectable rather than thrilling.
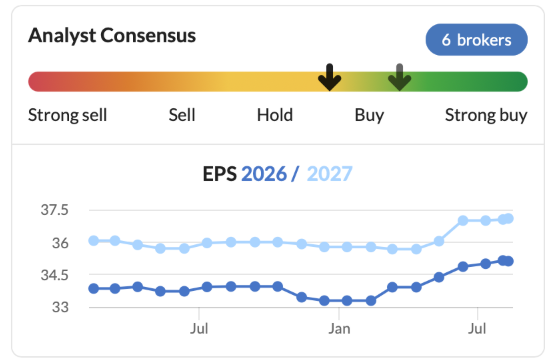
Estimates have moved up 0.7p for 2026 and 1.1p for 2027 over three months, though most of that came earlier in the window, so I would not assume it all reflects the August numbers.
Personally, I believe the environment may result in outperformance in the coming quarters. Let’s see.
The Bear Case
So why does a business with rising earnings and a record first half sit on 8.9x?
The multiple flatters. That 8.9x is on adjusted earnings. Reported earnings are a lot lower – 14.3p in the half against 19.3p adjusted – because the company strips out restructuring, legal and acquisition charges as “significant items.” There's £80 million of them guided for 2026. On reported numbers you're paying closer to 12x, and the market pays on reported.
There's very little visibility: Outside Parameta not much of the revenue is contracted, and the balance sheet is hard to model. Investors discount what they can't forecast.
The oil recovery may not come: Energy & Commodities carries £44 million of management and support costs, so a revenue wobble has a large impact on the divisional margin – which is exactly what happened. I’m expecting things to improve here based on my understanding of the geopolitics, but that might not happen.
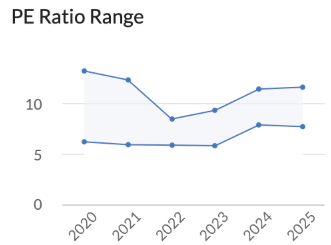
The stock is never expensive: There’s no precedent for a re-rating – the business hasn’t traded on much higher multiples.
The Bottom Line
TP ICAP is cheap, on rising forecasts, and pays 6% covered nearly twice. It has beaten its cost target a year early and is steadily retiring stock. Earnings are expected to continue improving throughout the medium term, with the stock trading at 8.7x earnings for 2027.
I see the broader macroeconomic conditions as being supportive and increasing levels of rate uncertainty could see the business beat expectations in the second half of the year. What’s more, the recent pullback – albeit modest – sharpens the attractiveness of the entry point.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
An interesting stock but I don't think the market will rerate the voice earnings - for years we listened to Michael Spencer tell us how voice would not last and now we are left shareholders in Tullets - so yes the earnings ebb and flow with runs in underlying securities and volatility spikes And a recovery in oil/mining may well offer upside to the earnings. The real upside I guess is what is hidden behind voice and is the information services business the real upside. I haven't got to the bottom of that yet and haven't really heard a strong view on Stocko. Just looking at the headline PE and thinking it looks cheap isn't the answer for me ...although it may well get you to the right answer. So I need to do a little more digging and see what hidden value I can find - I can buy Rio Tinto (LON:RIO) Glencore (LON:GLEN) or BP (LON:BP.) for mining and oil recovery.... so I would like to find a more attractive growth angle that sits inside. Should more metals find themselves on exchange this would no doubt also be positive for TP Icap (LON:TCAP) but Id prefer something more material before adding myself to the patient holders list.
Thank you Dr Fox for an excellent piece of analysis on an under-researched firm.
I started buying TCAP around c. 200p on valuation grounds so currently sitting on a healthy profit. What has persuaded me to stay invested is the business transformation that they are successfully executing.
This involves a move from purely voice-broking to the creation and roll-out of a series of trading platforms such as Fusion, Liquidnet (incorporating Neptune) and as you mention RealQ. This will I believe build deeper and stickier client relationships and thus a strategically stronger market position and improvement in margins and quality of earnings. This will, I anticipate, become reflected in a higher multiple being placed on their growing earnings.
My investment thesis isn't currently reflected in the mediocre Brokers consensus share price target of 351p +8%.
Although, Deutsche Bank initiated coverage in June with a ‘buy’ and a 415p +28% price target. I haven't access to their note but were reported on ShareScope to have said TCAP is "more than a cyclical broker" and cited the digital transformation and higher-margin subscription-led data assets. So, perhaps perceptions are starting to change.
I attribute the c. 22p share price fall on the results to disappointment that it appears that the Parameter float is on permanent hold. They'll need to get it growing in order to attain the lofty valuations that have been attributed to this division. So, I think the hot money has exited.
My own spt is 432p with the 6% yield and further buy-backs under-pinning my position.
excellent write-up Dr Fox..
Have been a holder for a few years now ( sub 175p purchase)...its getting tempting for a top up.
An excellent article. Owned it previously, but sadly sold as I lost patience with the Parameta sale being pushed back. Wish I hadn’t sold though, as I want to buy in again and hold as a ‘buy and forget’ type of stock
A good, well-balanced article on TP Icap (LON:TCAP) , I hold in my income portfolio and have done since the beginning of 2024. It has provided both a good income along with capital growth along with a useful hedge against rising volatility levels.
Thank you; a very useful analysis. My modest holding is based on value but also the possibility Parameta might be sold off at a multiple of the present rating which you don’t mention. Oh, and also portfolio diversification - I try to stay within my lowly pay grade, and it is complex.
your comments echo mine Crusty -
shout for your article Dr Fox - its q really top notch commentary that has really added to my understanding of the company - all i know is that this is company i wont ever understand fully how it makes its crust - you have highlighted one area to keep an eye out for - exceptional type items they can be a drain if the end number bottom line is less than the underlying figure - main thing i like where that is the case is honesty and transparency ref presentation - nothing worse than company that finds a new different set of exceptional items each year that one didnt expect. So thats an area to keep a close watch on.