Tribal Group: a Super Stock jumping beyond legacy contract drag

Ed recently wrote an article examining the performance of companies whose Stock Rank jumped to become Super Stocks. The results were impressive. The average share that jumped 10 to 20 points to a StockRank of 90 or above went on to return about +15.9% over the following twelve months, against +10.7% for the shares that were already in the cohort. This means that we should take these kinds of jumps seriously. However, I am always a little sceptical when the jumps are momentum-driven. It seems to me that when price momentum is not backed by fundamentals, the share price is at risk of a reversal (as evidenced by recent anecdotal examples, such as RWS Holdings (LON:RWS)).
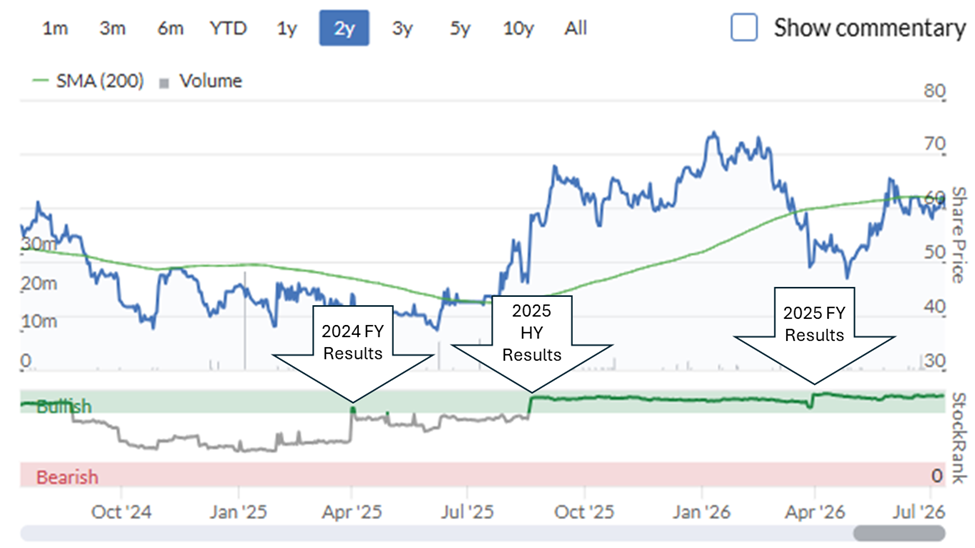
What interests me about Tribal (LON:TRB) 's inclusion on the Stock Rank jumpers list is that results being published have been behind each of the three recent jumps, not just price action:
In my opinion, this makes the stock worthy of further investigation, and our shorter Stock Pitch format is the ideal way to get started.
[Disclosure: At the time of publication, the author does not hold a position in Tribal Group.]
The Pitch
Tribal (LON:TRB) is an AIM-listed provider of software and services to education institutions globally, supplying cloud-based student information systems and related services to universities, colleges and vocational training providers. Incorporated in 2000 and publicly listed since 2001, the Sheffield-based group employs over 900 people and operates through two segments:
- Student Information Systems (SIS): The group's flagship product, SITS:Vision, covers everything from admissions to student records and course administration. This is the bulk of the business, and management has been steadily migrating customers from on-premise licences towards subscription and cloud arrangements, known as SITS Cloud or Tribal Cloud v3. Additional modules allow universities to manage aspects of their administration, such as Admissions, or Visas and Immigration. Cloud migration has increased the recurring proportion of core SIS revenue to approximately 86% in FY25.
- Etio: The group's international and vocational-education services arm, contributing £18.6m of FY25 revenue, up 9% year-on-year, helped by strategic changes made back in FY24. It carries a more flexible cost base than SIS, which matters given a modest exposure to Middle East-linked revenue.
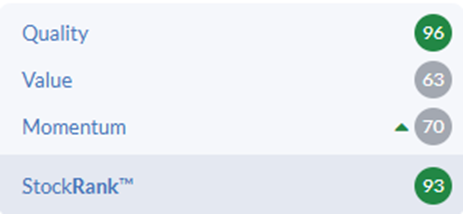
The Stockopedia algorithms rate this a Super Stock with a StockRank of 93, built on an excellent Quality Rank of 96, and a strong Momentum Rank of 71. The Value Rank of 62 is less impressive, reflecting a double-digit price-to-book ratio and a flat forward EPS growth estimate on a mid-teens multiple.
However, there are reasons to think the underlying valuation picture may be better than the headline suggests. While total revenue in FY25 was only up 2.8% to £92.5m, annual recurring revenue grew considerably faster at +14% in constant currency to £65.0m. This was driven by winning new customers, such as London South Bank University and Durham University, as well as a strong year for the group's vocational education offering. Adjusted EBITDA rose 8% in constant currency to £17.5m, while free cash flow more than doubled from £6.1m to £15.3m. Net cash came in at £11.4m at year-end (excluding £0.96m of lease liabilities) or around 8% of the market cap.
The Big Picture
Several features mark Tribal out as a company to consider further:
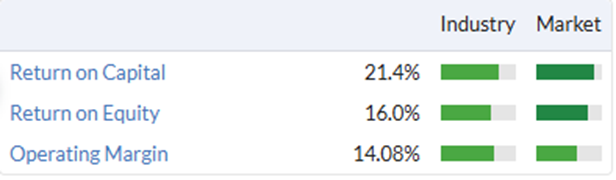
- Compounding, high-return metrics: Most recently, the company reported a Return on Capital of 21.4% and Return on Equity of 16.0%, both comfortably ahead of the industry and market averages, alongside a 14.1% operating margin.
- Legacy book becoming immaterial: Non-core revenue, largely consisting of ageing licensing deals, is being run off and has shrunk from around £10m per annum five years ago to just £2.1m in FY25. Core ARR has compounded steadily to reach £62.9m over the same period.
- AI as a tailwind, not a threat: Tribal is a specialist system-of-record provider whose decades of embedded business logic make it an unlikely casualty of AI disruption. Recent customer conversations are said to point towards accelerated cloud migration so that SITS can become the central data hub for student lifecycle analytics. Tribal Cloud could be a beneficiary of the AI shift rather than a risk to its business. With roughly 70 existing customers yet to purchase Tribal Cloud, there is £20m of ARR opportunity from the existing customer base if they can be persuaded to migrate.
Going Deeper
Several factors suggest a brighter future for the business:
- The cloud funnel: Of the 14% constant-currency ARR growth in FY25, roughly £2.7m comes from cross-selling, £2.6m to HEFS (Higher Education Full-Service - a comprehensive software subscription and delivery model) licence fees, and £1.8m to new customer wins, against only £0.9m of churn. HEFS licensing matters strategically as well as financially, since it creates a clear pathway for existing customers to move on to Tribal Cloud and SITS-as-a-service over time.
- The legacy drag abates: The major headwind comes from the conclusion of a legacy Australian TAFE (Technical and Further Education) contract, expected to cost around £3-4m in revenue in FY27. Tribal is actively transitioning these Australian vocational and higher education customers away from legacy platforms to its modern, cloud-native Software-as-a-Service (SaaS) platform, Tribal Edge. However, some churn and a drop in short-term revenue is expected during the transition. Beyond that point, there will be little legacy revenue remaining, and headline revenue growth will optically improve. Forecasts for Core SIS revenue growth have been conservatively modelled at just +2% in FY26, rising to +5% in FY27, leaving scope for upside if Tribal Cloud conversions, module upsells, or new customer wins are delivered.
- The capex-to-opex switch: Capital expenditure per share has fallen from around 5.2p in FY22 to 1.9p in FY25 as more product development spend is now run through the P&L as opex rather than capitalised. That has weighed on reported EBITDA growth and on near-term EPS forecasts. However, it means cash generation is running ahead of the profit and loss account, making the valuation look better on cash flow measures (although FY25 cash generation is also aided by working capital flows):

- Net cash gives longevity: Net cash is forecast to keep building through FY26 and FY27, even as the modest dividend increases. On their small remaining debt, interest cover stands at 18.6x, and gross gearing is just 1.6%, leaving room to keep returning cash to shareholders through the temporary consolidation stage in 2027.
- Strong shareholder register:
The top four holders own 62% of the company:
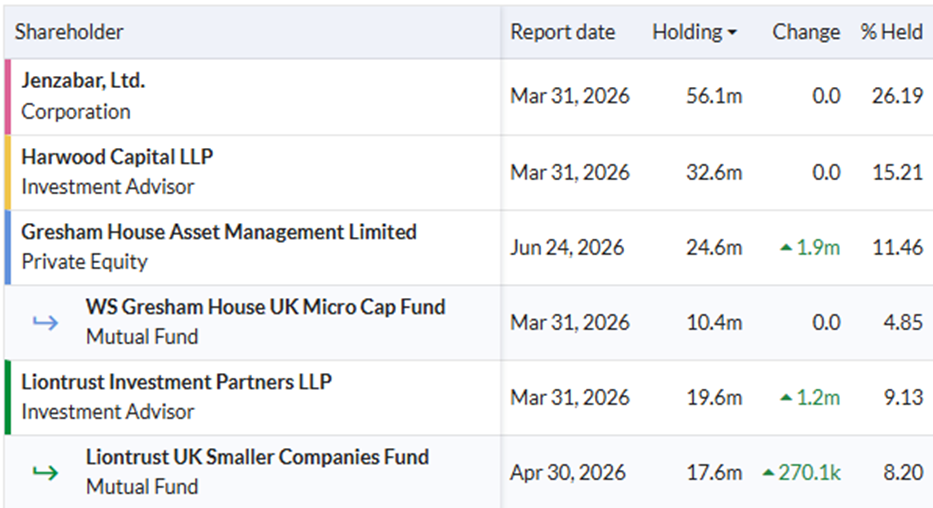
Jenzabar is a US-based company that specialises in technology solutions for higher education institutions similar to Tribal. In late 2023, another higher education technology provider, Ellucian, made a 74p all-cash bid for Tribal. Tribal's board unanimously recommended the acquisition. However, Jenzabar stepped in to halt it and bought up blocks of Tribal shares on the open market, effectively ending the proposed scheme of arrangement. Jenzabar stated during the dispute that it did not intend to make its own firm offer to purchase Tribal outright. However, if a valuation anomaly remains for too long, they may fancy their chances.
The well-regarded Harwood is the second-largest holder and is well-known for pushing management teams to create shareholder value. Even Liontrust, embattled by fund redemptions, has been willing to add to its position in the company recently.
What The Brokers Say
Singer rates the stock a Buy with a 12-month price target of 87.0p, implying upside of well over 40% from the current 60p share price. Their note, published in March, argued that FY25 results came in slightly better than upgraded guidance, with EBITDA 3% ahead, and that the shift to HEFS licensing has built "a very strong foundation to drive continued wallet share growth" through Tribal Cloud sales. They highlighted an 8% forecast FY27 free cash flow yield as attractive in the context of a business increasingly returning cash to shareholders, while flagging that near-term EPS growth may be limited by legacy decline, particularly in FY27.
Tribal's NOMAD is Investec, and while we don't have access to their note, the headlines suggest that they are even more bullish on valuation and have a Price Target of 100p.
The Bear Case
The investment case is not without risks:
- FY27 is the real test: The conclusion of the legacy TAFE contract is expected to knock £3-4m off revenue specifically in FY27, meaning that consensus EPS falls for this year. The "growth resumes after FY27" thesis requires both the legacy roll-off to land as modelled and the new Tribal Cloud/cross-sell opportunities to convert on schedule.
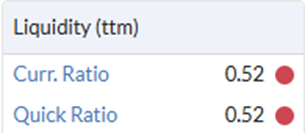
- Thin liquidity ratios: Both the current ratio and quick ratio stand at just 0.52x. That is a common feature of subscription software businesses funded by deferred revenue rather than a sign of distress. However, if revenue takes an unexpected dip, the combination of negative working capital and reduced revenue can lead to big cash outflows.
- Non-core revenue is still shrinking fast: Professional Services revenue fell 12% to £8.2m, and non-core software and services fell 20% to £6.8m in FY25. If new business conversion disappoints, this drag could persist beyond management's guided FY27 endpoint.
- Etio geographic risk: around £3-4m of Etio's revenue is linked to the Middle East, and while management has "prudently" forecast flat sales there given disruption risk that "has not materialised to date", a change in that environment would test the flexibility of Etio's cost base.
- Poor liquidity: For a £130m market cap company, trading is surprisingly thin, and the published spread can periodically exceed 5%. Individual investors should be able to trade within that spread, but liquidity may limit the position size investors are willing to have.
- Mixed customer reviews: User reviews of Tribal Group SITS paint a picture of a highly robust, broad-scope student information system that excels at lifecycle management but suffers from complex integration and dated usability. Aggregated scores across major enterprise tech directories average around 3.0 to 3.8 out of 5 stars.
The Bottom Line
Tribal Group looks like a high-quality, profitable niche software business that is currently working through the final stages of legacy contract run-offs. Non-core ARR has already shrunk to a small fraction of the group total; the FY27 TAFE contract conclusion appears to be the last significant headwind. Broker forecasts assume conservative core SIS growth, leaving room for upside from Tribal Cloud conversion, cross-selling, and new module sales.
The near-term earnings picture is uninspiring: EPS growth is forecast to be roughly flat this year and negative next. However, the cash story looks better than the earnings one. Free cash flow more than doubled in FY25, cash conversion approached 130%, and net cash is forecast to keep building even as capital expenditure needs continue to fall. An 8% forecast FY27 free cash flow yield looks good value for a business with genuinely sticky recurring revenue.
Investors may want to wait until there are signs that forecasts are proving conservative and the underlying trend is improving. However, those interested in the story probably shouldn't wait too long. Recent results have led to the shares being rated a Super Stock, as the Stock Rank jumped to an impressive 93:
An active shareholder base in a tightly held stock will push management to ensure that any dip in EPS as legacy contracts roll off is short-lived.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
I've been watching Tribal (LON:TRB), on and off, for a long time. I even had some of SITS shares at one point, before Tribal bought SITS up. I always felt that (SITS) might be a driver of Tribal's growth.
Ellucian is ten times the size of Jenzabar. The latter is privately held but zoominfo thinks its annual revenue is around $160m so not sure it could raise the financing to purchase the shares its doesn't own in Tribal (LON:TRB)
Looks like I should have bought more 3 months ago, when I actually sold at a loss. Patience and conviction needed as ever!