Triple Flag Precious Metals: Investment Briefing & Strategic Outlook (2025–2030)

Executive Overview
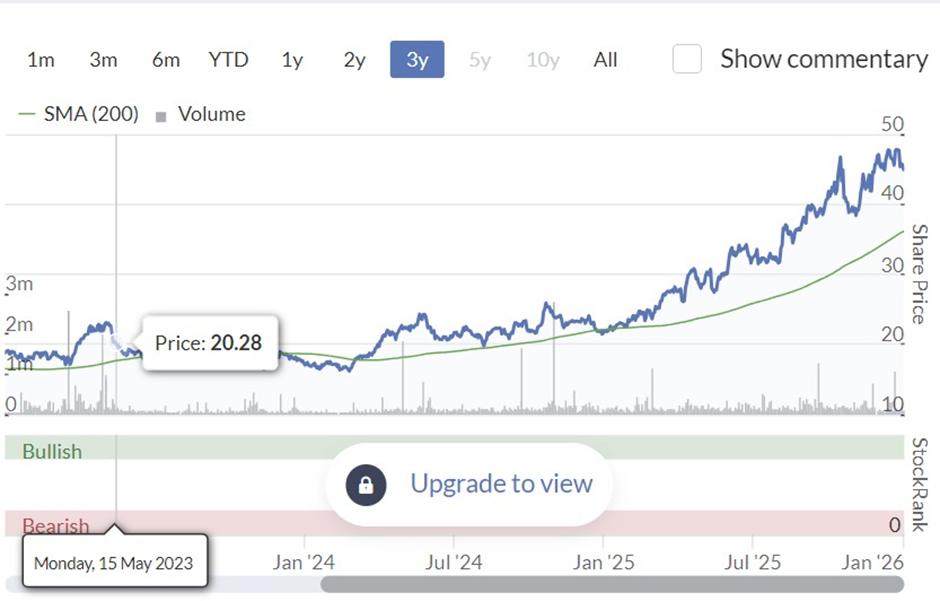
Triple Flag Precious Metals (TSX: TFPM; NYSE: TFPM) has delivered gains of 104% in 1 year and137% since listing on December 11th, 2019.
Triple Flag Precious Metals operates as a specialist provider of precious‑metal streaming and royalty financing, offering investors exposure to a diversified, long‑duration portfolio designed to generate resilient free cash flow. Its strategy is anchored in disciplined asset selection, strong optionality, sustainability considerations, and rigorous risk management. The organisation’s objective is to serve as a preferred capital partner to mining operators across commodity cycles, delivering tailored financing solutions supported by technical expertise, industry networks, and broader strategic capabilities.
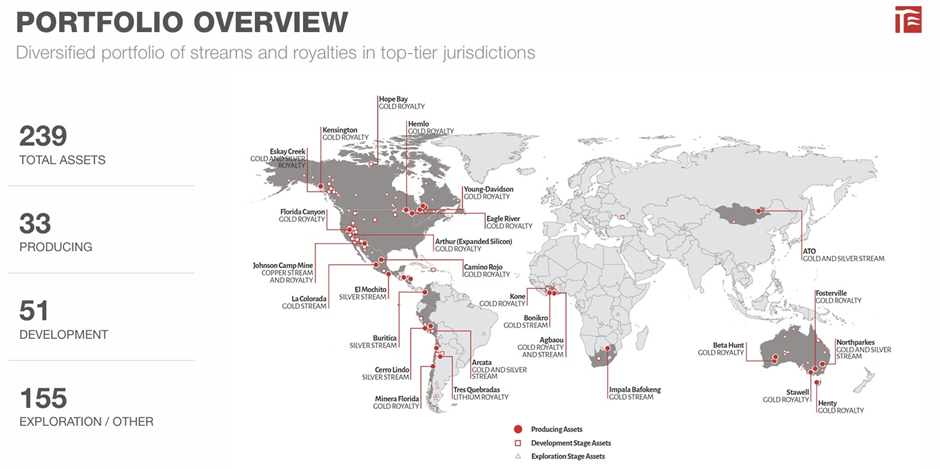
Since its establishment in 2016, it has achieved substantial growth, assembling a portfolio concentrated primarily in gold and silver assets across the Americas and Australia. The platform now encompasses 237 assets, including producing mines as well as development and exploration‑stage projects.
Corporate Development and Operational Updates:
- Operator upgrades (Evolution at Northparkes, Westgold at Beta Hunt, Kaiser at Henty) leading to improved execution capacity.
- Northparkes, a cornerstone asset contributing 39.2% of Triple Glag’s GEOs, offers significant exploration upside including from Major Tom and E51 targets +1,000 km2 tenement package.
- Multiple near‑term restarts (Arcata, Silvertip potential, Hope Bay long‑term).
- Lithium exposure added (Tres Quebradas) → diversification beyond precious metals.
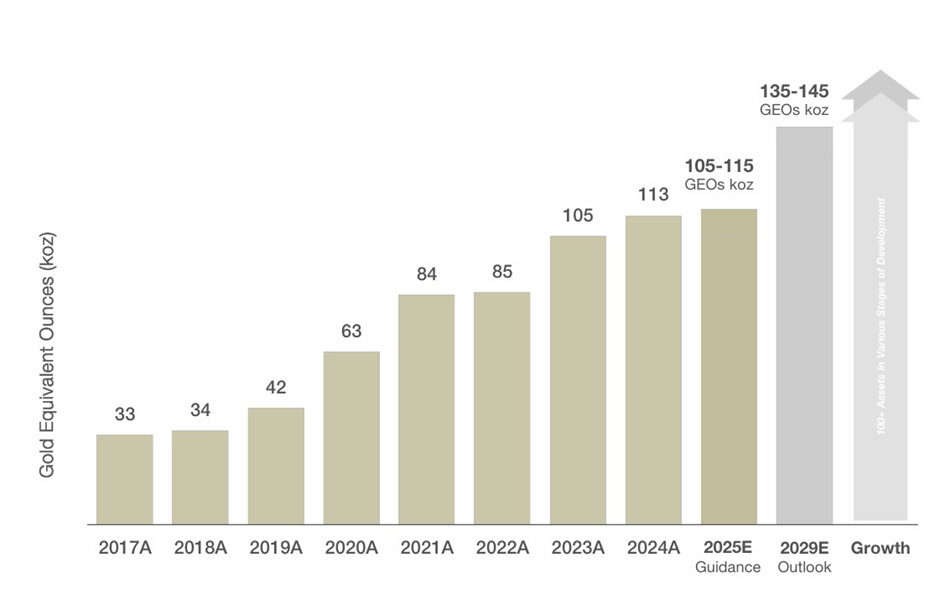
- GEO growth producing 112,623 GEOs in 2024, up from 105,087 in 2023.
- On target to deliver towards the upper end of guidance of 110 to 115,000 GEOs for 2025. 139,000 GEO forecast for 2029.
Triple Flag posted record Q3‑2025 results across its diversified royalty and streaming portfolio, underscoring the durability of its low‑risk business model. Recent additions, most notably the Expanded Silicon NSR acquired from Orogen, strengthen long‑term growth and deepen exposure to top‑tier jurisdictions. The development pipeline is genuinely transformative, with progress concentrated in high‑margin, royalty‑weighted assets located in the best operating environments and jurisdictions. Despite the stock’s strong performance, TFPM still screens as attractively valued with more than 20% upside to fair value, making any meaningful pullbacks compelling entry points.
With more than $1 billion in available liquidity and a deep pipeline of near‑term project catalysts, Triple Flag Precious Metals enters the next 12–24 months with exceptional operating leverage to both gold and silver.
Introduction
Triple Flag Precious Metals operates as a precious-metals streaming business with a significant royalty business. 80% of the total Gold Equivalent Ounces (GEOs) produced in the 3 months to September 30, 2025 were produced under the streaming contract model and 20% under the royalty contract model.
Triple Flag differs from Wheaton Precious Metals in that Wheaton is a pure streaming company whereas Triple Flag is both a streaming and a royalty company. For those unfamiliar with the terms:
Royalties: In a royalty structure, the asset owner commits to paying the royalty holder a defined share of revenue generated from production. These agreements provide exposure to commodity-linked cash flows without operational risk. Revenue‑based royalties typically fall into two categories: Net Smelter Return (NSR) royalties, which are calculated on the value of production after standard deductions such as transport, insurance, and processing charges; and Gross Revenue (GR) or Gross Overriding Royalties (GORR), which are applied to total sales revenue with minimal deductions. Together, these structures offer investors scalable, margin‑resilient participation in mine economics.
Stream: A streaming agreement provides the right to purchase a portion of a mine’s metal production in exchange for an upfront payment and a fixed ongoing price tied to delivery. Streams offer exposure to commodity upside, mine expansion, and exploration success, while maintaining minimal operating and capital cost risk. Unlike royalties, streams include an ongoing purchase payment, but the economic profile remains highly margin‑resilient. Streaming is typically applied to by‑product metals that are non‑core to the operator, enabling low‑cost financing while giving investors leveraged exposure to secondary metal production.
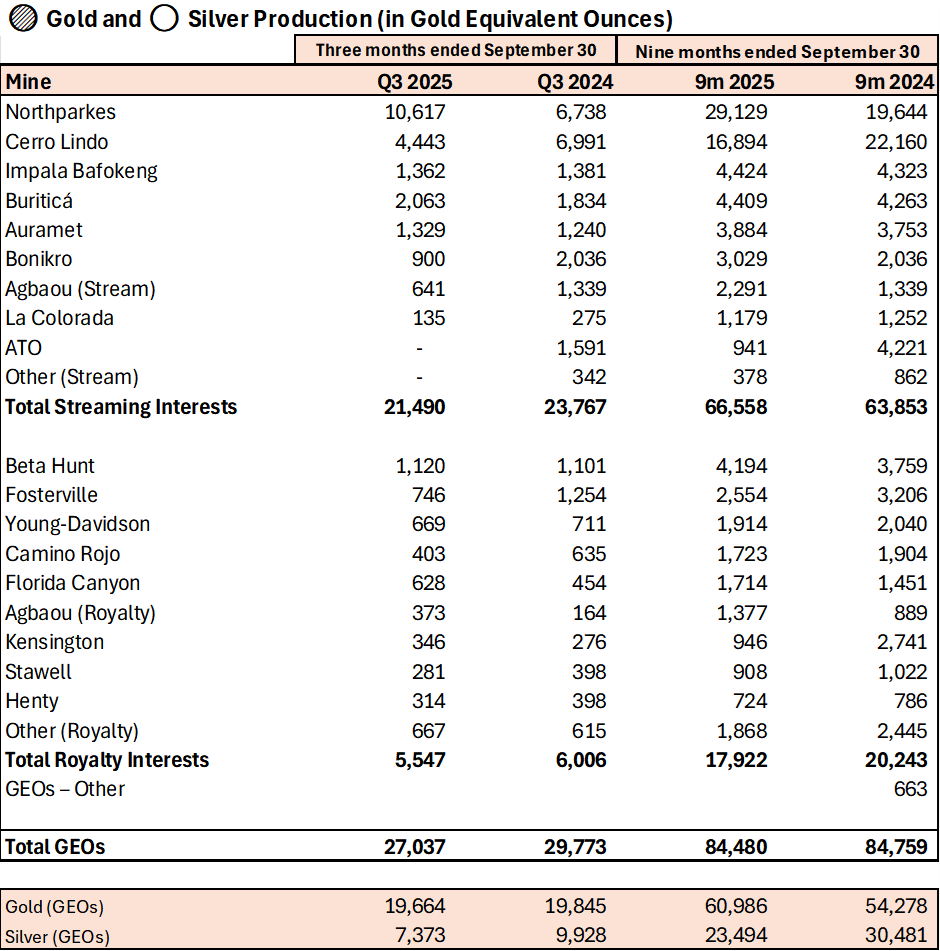
The portfolio is anchored by three major long‑life assets: Northparkes contributing 39.2% of total GEOs, Cerro Lindo 16.4%, and Buriticá 10.5%. Together, these three assets account for 66.1% of GEOs.
Triple Flag has grown rapidly since listing in 2019 and is on track to produce at the upper end of guidance of 105 to 115,000 GEO’s for 2025. For comparison, this makes Triple Flag slightly less than 20% of the size of Wheaton Precious Metals which is also held in the portfolio.
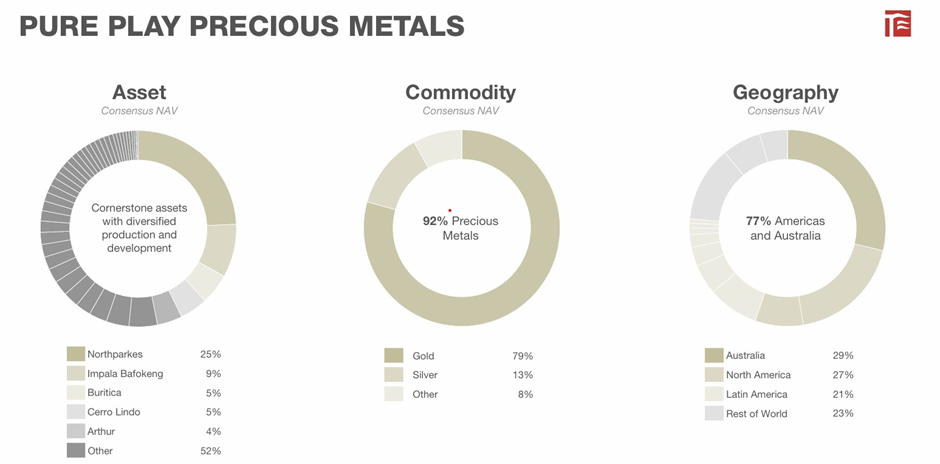
Triple Flag, like Wheaton Precious Metals, is anchored in tier‑one deposits across tier‑one jurisdictions, with 77% of its production coming from the Americas and Australia. Triple Flag provides meaningful jurisdictional diversification through its substantial Australian exposure, which accounts for 29% of total GEOs.
Operational Performance
Gold and Silver Portfolio
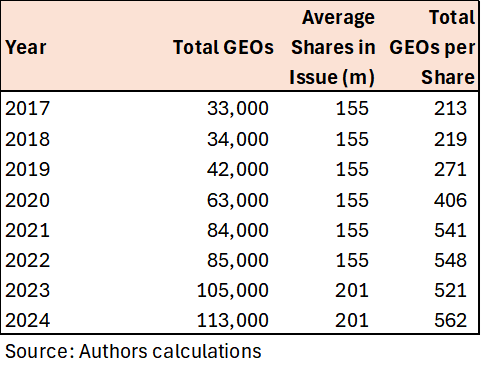
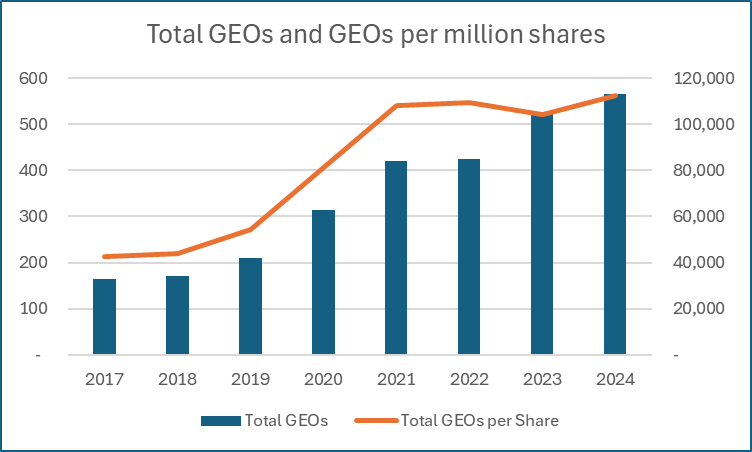
Based on Triple Flag’s 2024 annual report, cash flow is heavily concentrated in three core assets, with Northparkes contributing 39.2% of total GEOs, Cerro Lindo 16.4%, and Buriticá 10.5%. Together, these three assets account for 66.1% of GEOs, reflecting a concentration profile comparable to Wheaton Precious Metals. Triple Flag does not provide a split for previous years between gold and silver but have provided a graph of GEO progress over the past 8 years and guidance for 2025.
Key Operational & Development Updates 2025
Australia
Northparkes Gold & Silver Stream – 39.3% of total GEOs delivered
Under the stream agreement, the company is entitled to 54% of payable gold until 630,000 ounces have been delivered, after which the rate falls to 27%. It also receives 80% of payable silver until cumulative deliveries reach 9 million ounces, and 40% thereafter for the remainder of the mine life. Deliveries typically lag production by around two months. As of September 30, 2025, total deliveries under the agreement amounted to 90,767 ounces of gold and 1,197,102 ounces of silver.
For the third quarter of 2025, the company sold 9,699 ounces of gold and 69,630 ounces of silver, compared with 5,816 ounces of gold and 63,735 ounces of silver in the same period of the prior year. Gold‑equivalent ounces (GEOs) sold rose to 10,617 from 6,738, a 58% increase driven by higher deliveries.
For the nine months ended September 30, 2025, the company sold 26,885 ounces of gold and 180,885 ounces of silver, compared with 16,950 ounces of gold and 206,803 ounces of silver in the prior‑year period. GEOs sold increased to 29,129 from 19,644, representing 48% growth year over year.
Mining of the E31 and E31N open pits was completed in early 2025, with stockpiled higher‑grade ore expected to support deliveries through the year. Development of the E48 sub‑level cave began in July 2024, with production starting in the second half of 2025 and ramp‑up expected through 2026. A pre‑feasibility study completed in early 2025 confirmed a gold grade of 0.39 g/t for the E48 SLC, which is now being incorporated into the broader life‑of‑mine plan.
Initial production from the E22 orebody is anticipated during Evolution’s fiscal year ending June 30, 2029, pending completion of economic studies and board approval, with a previously reported reserve grade of 0.37 g/t gold.
Fosterville (2% NSR)
- Ongoing optimization to sustain ~175,000 oz/yr production profile.
- Continued underground exploration targeting high‑grade zones (Eagle, Swan, Harrier).
Beta Hunt (3.25% GR + NSR)
- Westgold completed acquisition of Karora (Aug 2024).
- Mine expansion to 2.0 Mtpa underway (second decline + ventilation upgrades).
- Fletcher Zone maiden resource (June 2025) doubled the gold resource base.
Stawell (3.65% NSR)
- Additional 2.65% NSR acquired in 2023; now full 3.65% coverage on all production.
- Stable underground operations; mill refurbishment completed earlier.
Henty (3% GR)
- Ownership change: Kaiser Reef acquired the mine in May 2025.
- High‑grade underground mine with renewed exploration focus.
Latin America
Cerro Lindo Silver Stream – 16.4% of total GEOs delivered
Under its stream agreement with Nexa, the company receives 65% of payable silver from the Cerro Lindo mine until cumulative deliveries reach 19.5 million ounces, after which the rate drops to 25%. Deliveries typically lag production by up to four months. As of September 30, 2025, total silver delivered under the agreement amounted to 18.2 million ounces, and the company expects the step‑down to 25% to begin in 2026.
For the third quarter of 2025, the company sold 372,698 ounces of silver, down from 576,744 ounces in the prior‑year period. Gold‑equivalent ounces (GEOs) sold declined to 4,443 from 6,991, reflecting lower deliveries and a higher gold‑to‑silver price ratio.
For the nine months ended September 30, 2025, the company sold 1,539,963 ounces of silver, compared with 1,845,843 ounces in the same period of the prior year. GEOs sold decreased to 16,894 from 22,160, driven by reduced deliveries and the impact of a higher gold‑to‑silver price ratio.
Buriticá Silver Stream – 7.6% of total GEOs delivered
Under the stream agreement, the company receives 100% of payable silver for the life of the asset, calculated using a fixed silver‑to‑gold ratio of 1.84, with no step‑down in rates. As of September 30, 2025, total silver delivered under the agreement reached 2.3 million ounces.
In the third quarter of 2025, the company sold 174,020 ounces of silver, up from 155,414 ounces in the prior‑year period. Gold‑equivalent ounces (GEOs) sold increased to 2,063 from 1,834. For the nine‑month period, silver sales totaled 389,485 ounces, compared with 357,113 ounces in the prior year, with GEOs rising to 4,409 from 4,263.
Operationally, Buriticá continued to perform steadily despite the ongoing presence of illegal miners. The operator maintained active engagement with local communities and national authorities, including the National Police of Colombia. During the third quarter of 2025, Zijin Mining Group completed the spin‑off of its overseas gold assets into a new subsidiary, Zijin Gold International Company Limited, with Buriticá designated as a cornerstone asset.
Camino Rojo (2% NSR on oxides)
- Orla guiding 110–120 koz Au production for 2025.
- Royalty applies to all oxide material except Fresnillo layback zone.
La Colorada (Gold Stream)
- 1,800 tpd combined oxide + sulfide processing.
- Stream covers 100% of gold at $650/oz ongoing payment.
Rest of World
Impala Bafokeng (Gold Stream)
- Large PGM complex; Triple Flag receives 70% of payable gold until thresholds met.
- Strong reserve base and long mine life.
ATO (Gold & Silver Stream)
- Mongolia-based; steady production with expansion potential.
Financial Strength
Record Cash Flow & Revenue
Triple Flag Precious Metals is back on track with operating and net profits and operating margins at sector norms following the acquisition of Maverix Metals in 2023 which temporarily destroyed margins and profit due to accounting write-offs detailed below.
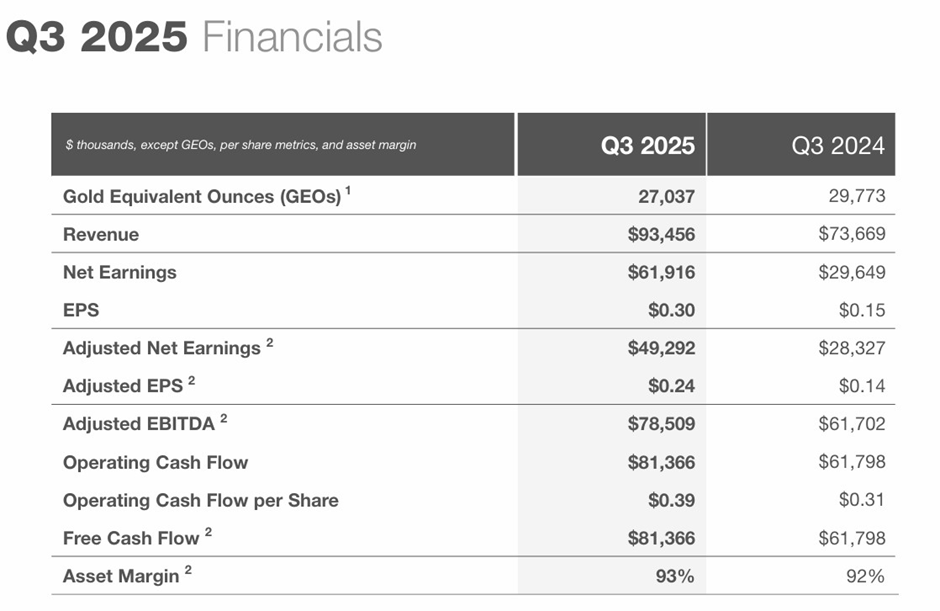
Unlike many miners and some royalty and streaming companies, Triple Flag Precious Metals continues to grow per‑share metrics without significant dilution — a key differentiator in the sector.
Triple Flag Precious Metals has delivered steady growth in revenue and profits while maintaining industry‑leading operating margins. However, as a comparatively young company, it lacks the long operating track record of established peers such as Franco‑Nevada (TSE: FNV) and Wheaton Precious Metals (TSE: WPM).
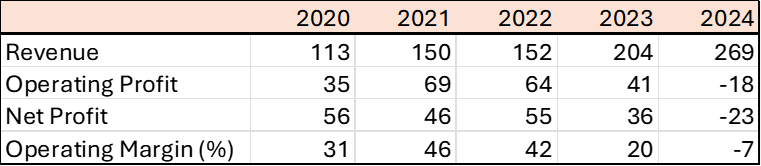
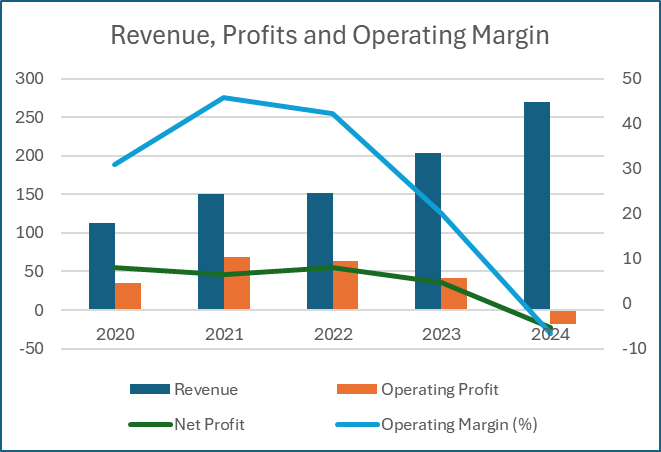
Flag’s sharp drop in operating profit and margins in 2023–2024 was driven by two very specific, non‑recurring hits: First, a large impairment and fair‑value write‑down in 2024 and second, unusually high depletion and acquisition‑related costs in 2023 following the Maverix Metals takeover.
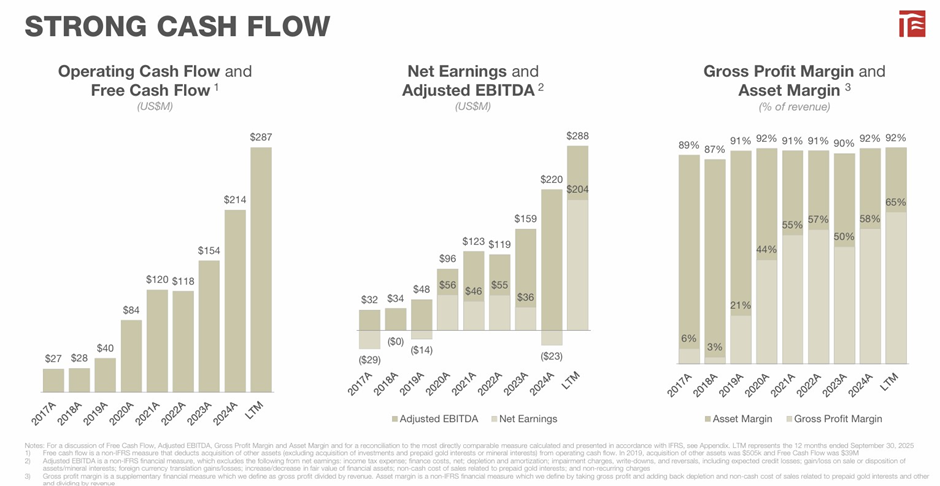
The operating income is 2024 was -US$18 million from record revenue of US$269 million. The ultimate net loss was -US$23.1 million because of a major non-cash impairment in Q2, 2024. The company took a large write‑down related to the Renard diamond mine which was acquired from Maverix and placed into care and maintenance in late 2023. This did not impact cashflow which hit a record of US$213.5 million in 2024.
In 2023, the operating income declined from US$64 million in 2022 to US$41 million in 2023. This was entirely due to a large increase in depletion expense: after acquiring Maverix Metals in January 2023, Triple Flag absorbed a A large portfolio of older, shorter‑life assets which came with higher depletion charges tied to purchase‑price accounting.
Depletion is the single biggest expense for royalty companies. When GEOs sold rise sharply (as they did in 2023), depletion rises even faster.
Balance Sheet
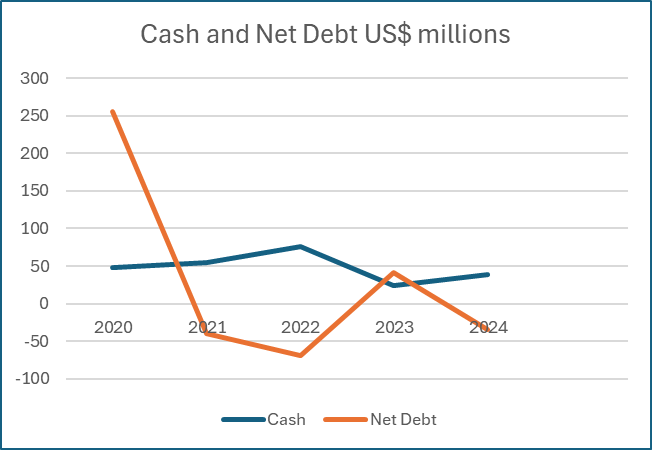
- US$24.4 million cash on hand.
- $1.0 billion total liquidity (including undrawn credit facility).
- No meaningful debt maturities. Triple Flag historically used a revolving credit facility for acquisitions, but they paid it down aggressively in 2024.
- Ample capacity to pursue additional streaming transactions.
Cost Structure & Margins
Triple Flag’s business model continues to deliver sector‑leading margins.
This margin profile is structurally superior to traditional miners, which face inflationary pressures, rising royalties, and higher sustaining capital.
Growth Pipeline (2025–2030)
Existing Contributors to Triple Flag’s Financial Performance with the Potential for Expansion. These are the bedrock anchor assets.
Northparkes stream (Australia) Triple Flag explicitly frames Northparkes as a core asset and the key driver of both record 2024 results (alongside Cerro Lindo) and record Q2‑2025 revenues, signalling it is now the single most material stream by GEO and revenue contribution. It’s a large, long‑life copper‑gold operation in a tier‑one jurisdiction, with Evolution as operator, so volume and reliability are both strong.
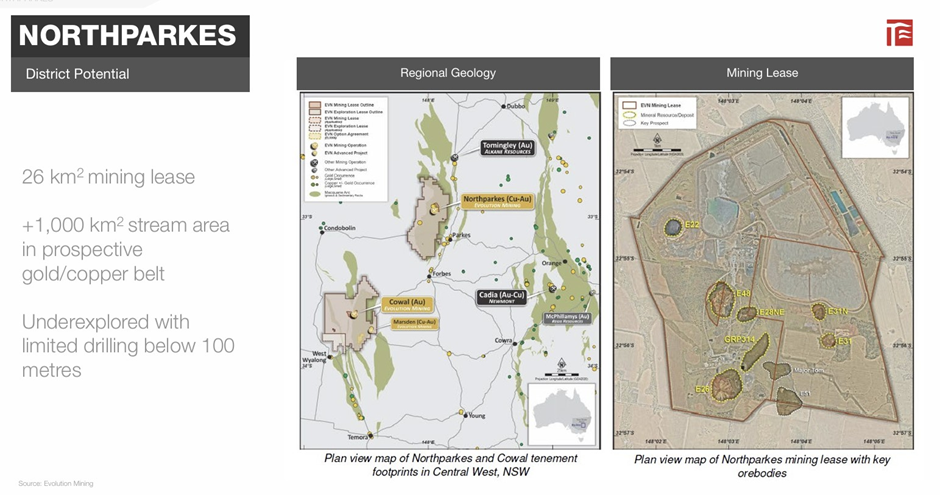
There is a long history of reserve replacement and growth with multiple large-scale porphyry copper deposits. Northparkes is a mixed underground caving and open pit mining with the current mine plan focused on 5 deposits: E26, E48, E22, E31, GRP314 The operation benefits for a well-capitalized infrastructure with 7.6 Mtpa mill capacity; permitted up to 8.5 Mtpa. There is significant exploration upside including from Major Tom and E51 targets +1,000 km2 tenement package.
Cerro Lindo silver stream (Peru) In the 2024 results, management states record performance was “driven by strong growth at Northparkes and Cerro Lindo,” which puts Cerro Lindo clearly in the top tier of contributors. It’s a big polymetallic mine (Nexa) where the silver stream gives Triple Flag scalable exposure without operating risk.tripleflagpm.com
Impala Bafokeng gold stream (South Africa) Triple Flag highlights Impala Bafokeng as one of the anchor assets in its diversified portfolio. It’s a large PGM complex with a substantial gold by‑product stream to Triple Flag, underpinned by long life and big reserves, so even moderate gold volumes translate into meaningful, high‑margin GEOs.
Buriticá silver stream (Colombia) Buriticá is named as one of the key long‑life mines in Triple Flag’s portfolio. As a high‑grade underground gold operation (Zijin), its silver output is tied to strong gold grades, so the stream gives robust, long‑duration silver GEOs with no disclosed cap/step‑down.
Fosterville NSR (Australia) Fosterville is a flagship Australian gold mine and explicitly listed among Triple Flag’s “suite of long-life mining assets” alongside Northparkes, Cerro Lindo, Buriticá, and Impala Bafokeng. Even as grades normalize from peak Swan years, a royalty on this asset remains a material cash generator.
Camino Rojo NSR (Mexico) Camino Rojo appears in the core asset list and is a producing open‑pit gold mine operated by Orla. The 2% NSR on oxide material (excluding the Fresnillo layback) gives immediate cash flow and leverage to mine life extensions.
La Colorada gold stream (Mexico) La Colorada is included in Triple Flag’s key asset roster and is structured as a stream on 100% of gold at a fixed ongoing payment, making margins structurally high and giving direct torque to production and gold price. While smaller than Northparkes/Cerro Lindo, the economics per ounce are very strong.
Summary of Growth Assets: Development and Exploration
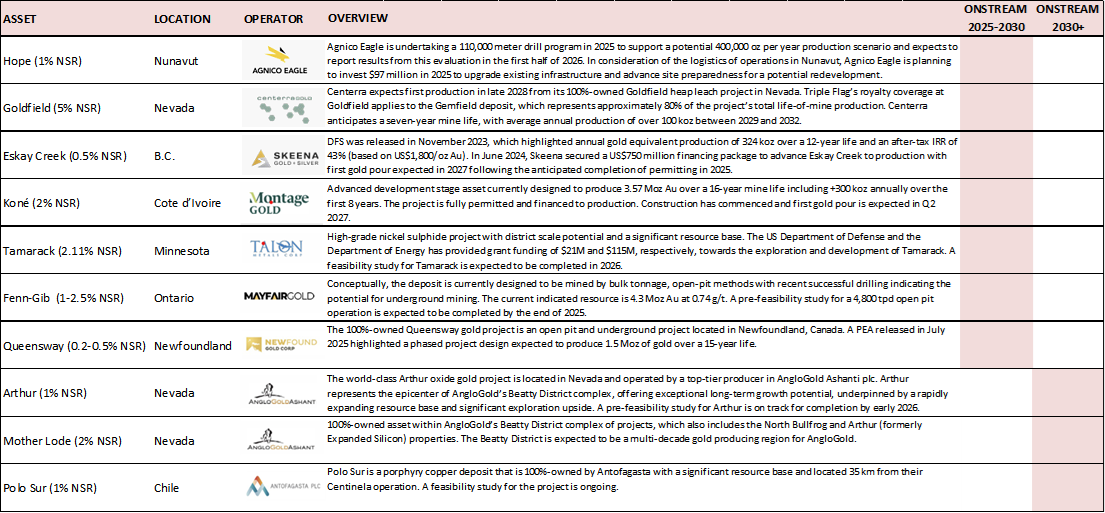
Among Triple Flag’s growth assets under development or exploration, the Arthur deposit in Nevada stands out.
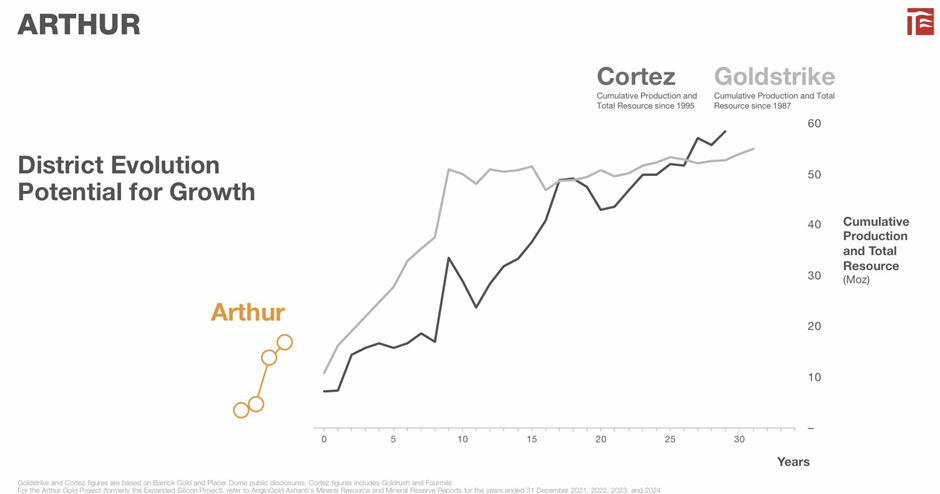
The Tier 1 Asset includes the Silicon and Merlin deposits in Nevada, which are recognized as North America’s largest new gold discovery. The project has demonstrated rapid resource growth, with resources increasing to over 16 million ounces since drilling commenced in 2018 and an initial mineral resource estimate was declared in 2021. There is significant exploration potential to extend mineralization further, including longer-term opportunities from deep, high-grade feeder structures. As a Tier 1 operator, Merlin and Silicon form the core of AngloGold’s Beatty District complex. Triple Flag holds a 1% Net Smelter Return (NSR) on this district.
Growth of Resource at Arthur
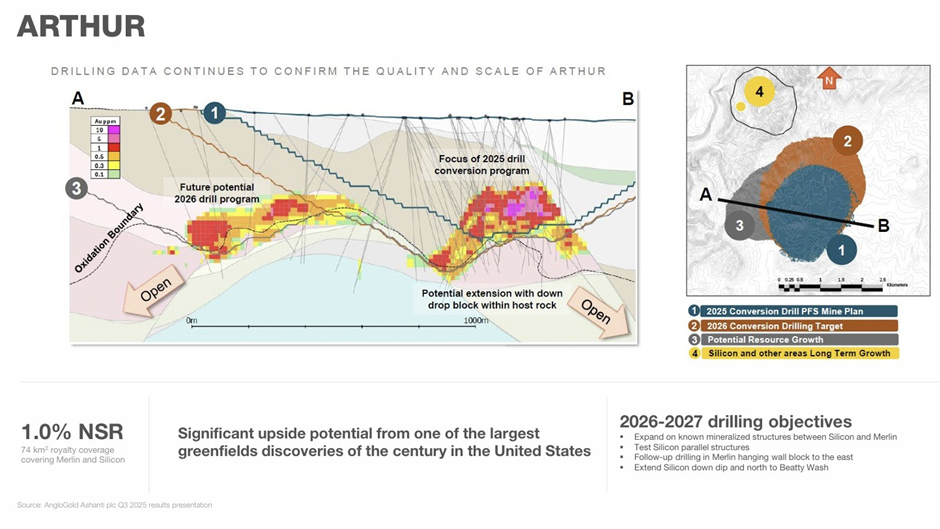
The royalty covers 74 km² including the Merlin and Silicon deposits, which together form the Arthur Gold Project. Triple Flag’s royalty gives it exposure to both current resource growth and future exploration upside across the district. This is a pure royalty contract, not a streaming deal — meaning Triple Flag receives a percentage of revenue from gold sales, not physical metal deliveries.
This highlights a key advantage of royalty and streaming companies: they can profit from resource exploration and expansion without paying drilling or geology expenses.
Valuation Considerations
Premium Multiple
Triple Flag trades at a discount to peers due to smaller scale and less liquidity, and the fall in financial performance in 2023 and 2024 due to the non-cash acquisition related reasons outlined earlier.
This is despite Triple Flag’s Balance sheet strength, solid per share growth in GEOs, strong exposure to silver and the streams are in tier 1 jurisdictions. Triple Flag also provides exposure to Australia where the major players – Wheaton, Royal Gold and Franco Nevada have minimum exposure.
At current prices, the stock trades around:
- ~23.6 x TTM EV/FCF
- ~19.25 x TTM Price / Sales
- ~32.4 PE TTM (GAAP earning basis)
- TFPM trades at 1.47× NAV and 17.2× blended EBITDA, “which is at the upper range of its peer group
This suggests the company’s shares are expensive. However, a DCF analysis prepared by the author suggests the share are significantly under-priced.
DCF ANALYSIS
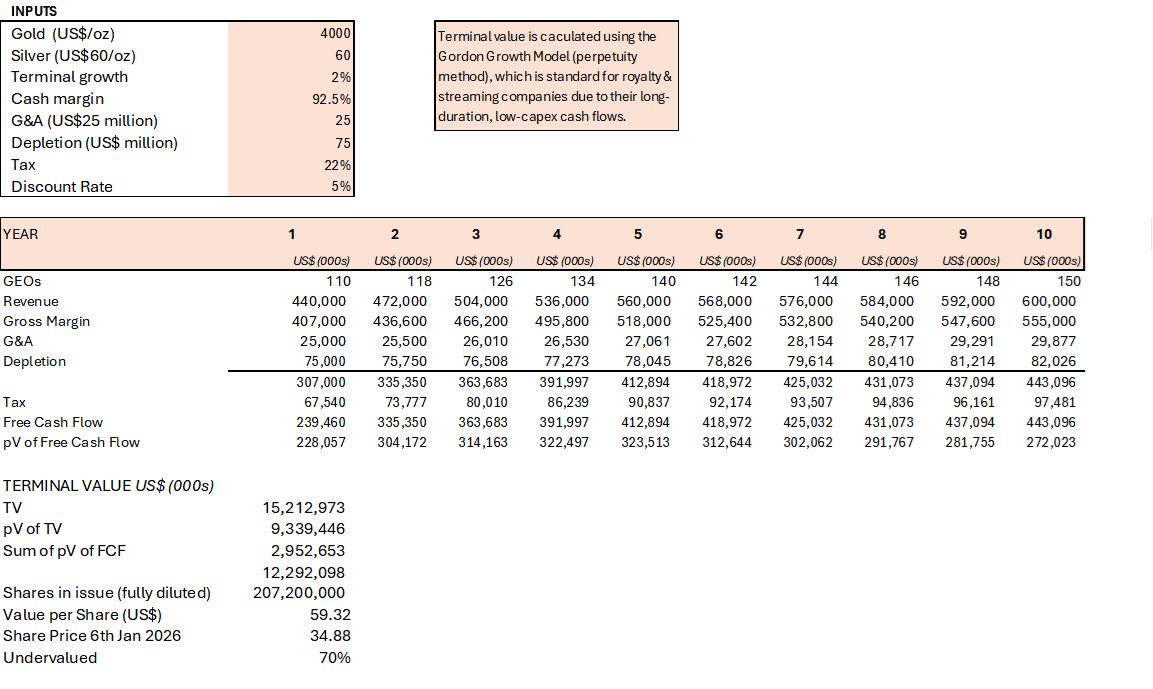
Source: Author’s own calculations from publicly available records including the annual reports.
Risks: Concentration & Step‑Downs
Key risks include:
- Heavy reliance on Northparkes in Australia which contributes 10,600 GEOs of a total of (~40% of cash flow).
- Several streams include step‑downs or expiries.
- Execution Risk on Growth Projects particularly Arthur.
However, the upcoming wave of new assets materially reduces concentration risk over the next 24–36 months.
Investment View
Triple Flag has been very successful at growing its Gold Equivalent Ounces over the past 8 years and, more importantly, has successfully grown the GEO per share which is an absolutely critical metric when considering whether or not to invest in any mining or streaming business, irrespective of commodity.
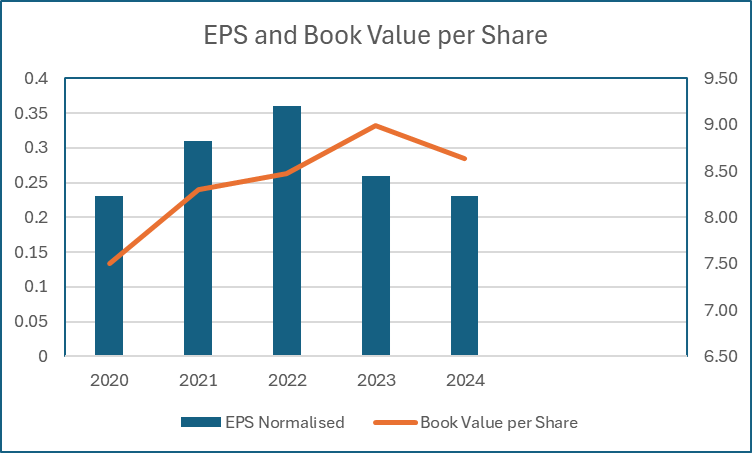
Triple Flag has been a significant position in my portfolio for several years now and is, for me, a string hold. Like Wheaton, Triple Flag offers one of the cleanest, lowest‑risk ways to gain leveraged exposure to gold and silver. The company combines:
- High‑margin streaming economics
- A deep pipeline of new assets
- Strong per‑share growth
- Balance sheet strength
- Minimal operational risk
- Similar to Wheaton, significant silver exposure
Pullbacks toward late US$28 to US$30s would offer particularly attractive long‑term entry points, and I would accumulate at these levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Many thanks for the really detailed analysis of Triple Flag Precious Metals (NYQ:TFPM) . The States and Canada have a much better selection of royalty/streaming based companies than the UK. I really like the model for exposure to commodities. Actual mining companies come with their inherent operational risks and I have had mixed results with these in the past. A single mining company is often too big a gamble on a particular commodity price for my liking though I did dip my toe in quite late in the game with Serabi Gold (LON:SRB) last year. A diverisfied spread across countries and commodities seems sensible. So in the past I have been more comfortable investing the sparce UK pickings such as Ecora Resources (LON:ECOR) one of the few royalty based companies on the LSE.
My new years resolution is to explore US stocks and shares after taking advantage of a Stockopedia offer to expand my subscription to the US markets. Knowing that the US has a decent selection of royalty companies this seemed a good place to start so your article is perfectly timed.
I had been thinking about Wheaton Precious Metals (NYQ:WPM) but believe the royalty model is less risky than the streaming model.
I also quite like Franco-Nevada (NYQ:FNV) which gives good diverisification and has a solid track record and the highest SR of all the US royaly companies I have looked at (SR84). It is also larger than TFPM.
GPTChat offered the following selection of US Diversified Precious-Metal / Multi-Commodity Royalty Companies
Wheaton Precious Metals (WPM) – Precious-metal streaming (gold & silver), limited base metal exposure
Triple Flag Precious Metals (TFPM) – Gold, silver, copper by-products
Franco-Nevada (FNV) – Also fits here due to energy and diversified assets
Are there any others you have considered in this category and your thoughts on Franco-Nevada (NYQ:FNV) would be appreciated.
Thank you very much for this, I very much appreciate the time and effort that has gone into this post (as well as your other recent posts). Although over a third of my PF is currently Ag/Au related, I was previously unfamiliar with Triple Flag Precious Metals (NYQ:TFPM). I am sure I am not the only one that has/will learnt/learn a tremendous amount from this post.
Very best wishes for 2026!
You are welcome Willinvest. I am finding to write is to learn and I am getting to know better the constituents of my own portfolio as a result.
Someone aske me to look at Gold Royalty (Gold Royalty (ASQ:GROY) ) and I would also like to research and write a royalty/streaming company comparison article. There are dozens of royalty and streaming companies, so why Wheaton Precious Metals (TSE:WPM) and Triple Flag Precious Metals (TSE:TFPM) and not others?!!
I also own Agnico Eagle Mines (TSE:AEM0, Pan American Silver (TSE:PAAS) , Equinox Gold (TSE:EQX) , Fresnillo (LON:FRES), Alamos Gold (TSE:AGI) and New Gold (TSE:NGD). I will try and write something for each over the next few weeks,
Fantastic detailed analysis of TFPM . Many thanks.
I think I am possibly one of the people keen for you to carry out your analysis of GROW.
Following your review of Triple I may now split my next investment between topping up GROW and starting investing in Triple as well.