Universal Store outperforms a universe of IPOs

In October / November 2020, five retailers listed their shares on the ASX. The table below shows how they have panned out.
| Company name | Listing date | Listing price | Capital raised ($m) | Price 16/3/23 | Change since listing |
|---|---|---|---|---|---|
Universal Store Holdings (ASX:UNI) | 16/11/2020 | $3.80 | $147.8 | $5.06 | 33% |
Adore Beauty (ASX:ABY) | 23/10/2020 | $6.75 | $269.5 | $0.83 | -88% |
Dusk (ASX:DSK) | 2/11/2020 | $2.00 | $70.0 | $1.52 | -24% |
Mydeal.com.au | 22/10/2020 | $1.00 | $40.0 | $1.05 | 5% |
Zebit | 26/10/2020 | $1.58 | $35.0 | $0.05 | -97% |
UNI is the only one with a materially positive return. Mydeal.com.au was taken over by Woolworths in September 2022 at a 5% premium to the listing price, however prior to the takeover announcement they were trading at $0.65. Zebit had declined 97% before being delisted in April 2022, only 18 months after listing. DSK is down 24%. ABY’s listing was a private equity exit and raised the most capital at $270 million. It is down a massive 88% to date.
Universal Store Holdings (ASX:UNI) are an Australian based retailer that specialises in men and women’s casual fashion and accessories with a particular focus on the youth market. They currently have a network of 93 stores and are growing their footprint at a rapid pace. They added six stores in the most recent half year. 76 stores are branded Universal Store, seven are branded Perfect Stranger and ten are Thrills. They are targeting 100 - 103 stores by 30 June.
The Thrills group of stores were added via an acquisition that was completed in October 2022.
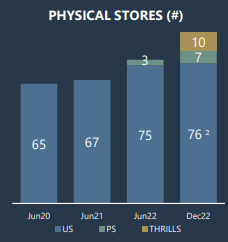
Source: Universal Store, H1 FY23 Results Presentation, 23/2/23
Sales for the group have grown very strongly over the past five years with a compound annual growth rate of 19%. This has consisted of in store sales growth, new store openings, growth in online sales, the launch of the Perfect Stranger concept brand and the acquisition of Thrills. They are targeting over 100 Universal stores across Australia and New Zealand.
Sales dipped in 2022 as a result of the extended lockdowns, but are forecast to rebound strongly in FY23. Indeed first half revenue growth was 35% but this is cycling against the period where a lot of stores were closed in the prior year.
Despite the constant talk of inflation and the rising cost of living, consumer confidence has proven very resilient. This is driven by the fact that unemployment is only 3.5% a level not seen since the 1970s. Consequently retail sales have remained buoyant to date. Rising interest rates may eventually start to dent that, but given Universal’s younger demographic, they will be less exposed.
Most importantly, sales growth has been backed up with profits. The business is highly profitable with gross margins approaching 60% and operating margins in the mid teens. Return on equity is almost 20% and Return on capital employed is above 17%. This combined with a Health Trend of 7/9 results in a Quality score of 97 placing it in the top 3% of all ASX listed companies.

The balance sheet is strong with cash exceeding financial debt. As with many retailers they have a high level of lease liabilities as they lease their bricks and mortar premises. This results in gross gearing of 57%, but they are still well within the safe zone on the Altman Z score.
Cash flow is also strong. Operating cash flow typically exceeds reported profits which is a sign of a healthy business. The liquidity and efficiency ratios are also healthy.
The Chairman of Universal is Peter Birtles. Birtles was previously the managing director and CEO of Super Retail (ASX:SUL). He joined Super Retail in 2001, and was managing director and CEO from 2006 to 2019. During this time the business grew substantially into one of the leading retailers with a market capitalization of $2.8 billion.
In terms of its valuation, UNI is competitively priced. Most of the value metrics are about the middle of the range for its industry. This reflects the fact that it is a strong operator as was highlighted by the comparison at the top of the article.
In an article by Roland Head titled “Screening for Warren Buffett stocks: the ultimate strategy?”, Roland created a screen that he believes would closely mimic the approach Warren Buffett uses to choose stocks that are likely to be great compounders. When that screen is applied to the Australian and New Zealand market, only 11 stocks make the grade. UNI is one of them. (DSK is too).
Warren Buffett is often quoted as saying “he would rather pay a fair price for a great business, than a great price for a fair business.” With an overall StockRankTM of 97, and a Value score of 71, UNI looks more like the former than the latter.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?