VAU - A coming together to create a mid-tier producer
There has been a lot of talk about how price takers are suffering. Especially with energy metals prices have been on the nose and their source of excess returns in 2020 to 2022. But then it’s easy to forget that there is a metal currently trading at all time highs which is quite a feat given Cleopatra reportedly loved being adorned by the stuff and she was around in BC times. Of course I am talking about Gold, and after a significant strengthening of the US dollar, the commodity has certainly received another free kick in AUD terms in recent years.
For those that have read my analysis over the years, you will know that I have repeatedly said that investing in an operational miner is different from investing in the commodity itself as it carries more risk than just the price. Therefore when you look for a miner, look for one where the production profile is expected to increase overtime, whilst also benefiting from a solid commodity price as well.
It is in this context that we cover Vault Minerals (ASX:VAU)

For those unaware, VAU was formerly known as Red 5 Limited. It is an Australian gold mining company that recently merged with Silver Lake Resources in June 2024. This merger in their words created a leading diversified mid-tier gold producer, combining Red 5’s King of the Hills asset with Silver Lake’s significant operating portfolio, particularly in the prolific Leonora region of WA.
An investment in VAU would note only be driven by good StockRank and underlying commodity, but also by its strong production and Financial Health as evidenced in their recent quarterly production report. Further the addition of the Sugar Zone in Canada extends its projects across a new jurisdiction and the recent Deflector find in WA also offers the potential of production upside in the near future. Couple that with the current strong cash balance and it would seem the business is now self funded, with little to no need to raise any additional capital unless it makes a game changing acquisition of course.
In the latest quarter it trumpeted AISC (All in sustaining cost) of AUD$2,231 per ounce, With gold currently around AUD$4,195 per ounce that is a juicy margin.
Quality
It is unsurprising VAU has an impressive quality score of 86.
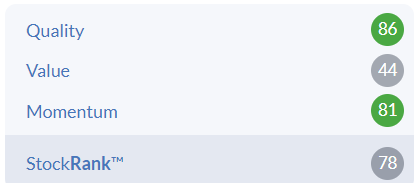
This not only reflects the strong profitability that the company has achieved, but also the company's financial health, efficient operations, and stable management.
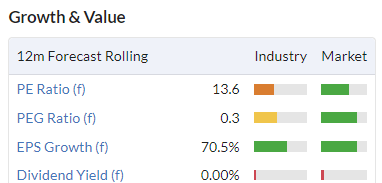
While its always hard to make such assessments after a massive transitional style acquisition, a forecast growth rate in EPS of 64.4% should not be sneezed at, notwithstanding there are more spectacular gaims to be had in likely higher risk plays.
According to the company and as is shown in the latest set of accounts, the company has low debt levels. We can also see that by its net gearing ratio of -13.63%, which indicates a cash-positive position.

What I want to see in these companies is sales growth, and not just because commodity prices have gone up. Given the merger you expect revenue to be 47% year-on-year and this is expected to grow. This growth is underpinned by its successful expansion and improved operational outputs.

As with all miners, they live and die relative to their cash flow and VAU has managed for the first time in a while been able to generate positive cash flow from operations. This to me suggests effective cost management and productive capital deployment, in this period where the cost of doing business is increasing. That said, they’re no island in this regard at the moment and if I held a gold miner who wasn’t doing this during a record price period I would be asking serious questions.

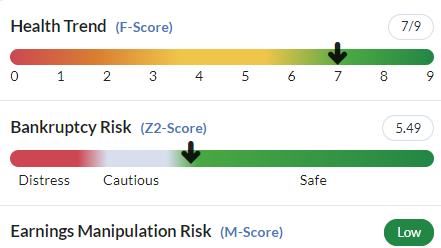
Finally when looking at other metrics regarding insolvency risk and cash manipulation their scores indicate that all is well. Again, a symptom of the strong cash flow generation that the business is undertaking.
Value
The company has a mixed value profile rating of just 44. While it would be easy to point the finger at the recent run up in price. I think investors are looking at the future increased cash flows that are expected to come. Looking at a P/FCP of 27.0 and EV/EBITDA of 16.25 indicates that you have to pay to play with VAU.
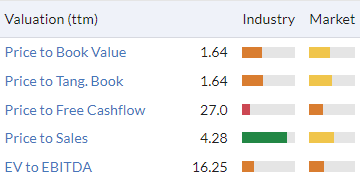
But investors are willing to do this on the expected future cash generation that will come from the King of the Hills expansion and the ongoing growth initiatives eg the Deflector region (in Australia) and the Sugar Zone (in Canada).
Momentum
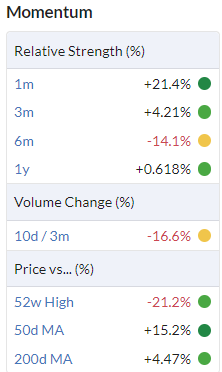
Again, not the highest score possible at 81, however still quite solid. Unlike the price of the underlying commodity that it deals with, VAU is not trading at all-time highs, however it has significantly de-risked the business.. First with production at King of the Hills. Then following the joining of RED and SLR.

The company is still in a longer term uptrend and short term it is also holding its own, As evidenced by the strong relative performance over the past month and the current price being well above the 50DMA. This especially when compared to the 6 month figure, where the stock underperformed the index.
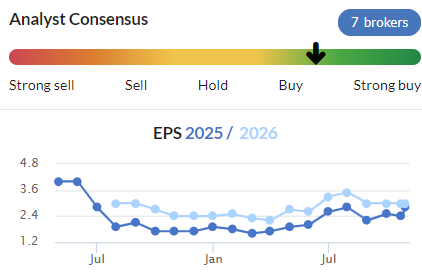
Whilst the analyst consensus on the business is still below the current price, more poignant to me is that the trend in EPS estimates after the big writedown over the May to July period last year have stabilised and have actually risen since, Whilst not a glowing endorsement at this stage. It does provide more confidence on what is to come.
For what it is worth, it is not quite in the Shine Zone as of yet as the QM score is 79. (the hurdle rate is 80 or greater). But in my view it is headed in the right direction so that is a bonus.
Leadership
Unlike some of the other companies discussed in this forum, VAU is not backed in large part by a Founder. In fact the current CEO Luke Tonkin has a negligible interest in the business, which in itself is not unusual for a $2.5B company. And as I read further into the annual report I see he played a crucial role in the recent merger with Silver Lake Resources. However much of his gold grounding was with Sons of Gwalia who for those that don’t remember went broke amid a wall of bad hedging contracts (though he was apparently a high level exec… not the main person.)
While this is not a big issue in my mind at present, it is something to bear in mind in the future should things get a little rocky. Though for the moment, there is plenty of liquidity for an investor or trader to get in and or out.

Development Pipeline
As mentioned earlier, I feel such mid-tier producers are only as good as what is next to come out of the ground. As a mining company, not only are we kept up to date when there is something significant happening in the business, but we also get quarterly activity and cash fow statements which add a level of transparency. Looking at the company;s latest documentation there are definitely things it is working on,
Fortunately for us as investors it is not too difficult to get our head around this. All growth from here is underpinned by the recent 39% year-over-year increase in ore reserves, along with a 99% rise in mineral resources.
They will be allocating approximately A$30 million for exploration work in FY25. This strategic investment will target both near-mine and regional exploration, enhancing the long-term potential for new resource discovery across its multiple sites.

Source: Denver Gold Forum 2024 Investor presentation
Of course for them a major focus will be in the Deflector Region, where recent high-grade mineralization (gold and copper content) was discovered approximately 500 meters southwest of the main lode.
Further, VAU is conducting advanced engineering studies for a planned plant expansion at King of the Hills, with a target capacity increase to 6 million tonnes per annum (mtpa). This expansion is expected to boost throughput, lower operational costs, and improve free cash flow from one of its flagship assets.
Finally, VAU’s Sugar Zone project in Ontario, Canada, represents a strong future development opportunity. Following a comprehensive drilling program completed recently, VAU is now evaluating new production scenarios to tap into this substantial deposit. I think this Canadian project will be a valuable addition to VAU's portfolio, by adding geographic and operational diversity.
Risks
Again as mentioned earlier, an investment in VAU is not without its risks. And when we are talking Mining stocks, we should, “never say never.”
There are the usual risks associated with a commodity producer which includes the commodity price and currency, operational and exploration risks. Even funding risk, despite the strength of their balance sheet they may need additional funding for significant future expansion. And if access to capital markets is challenging it could have an impact on VAU's ability to raise funds and seize any opportunities.
Other risks include a cost blow out on development and capital costs. For example, it costs more to complete King of the Hills expansion than first thought.
You also have the implementation risk. While Silverlake Resources elevates the revenue received, aligning operational practices, consolidating management, and streamlining financial systems may be challenges not yet fully appreciated.
All these reasons above (and more) are why investing in VAU or any gold miner is not like holding the core commodity. If anything it is a hedged exposure to the commodity. During good times you hope for the stock to do better, but that is vice versa if the commodity price goes the other way!
Conclusion
In the author’s opinion, and that of the company no doubt, is that VAU is a compelling investment opportunity due to its strong financial position, extensive growth potential, and solid management team.
I regularly point to the merger with Silver Lake Resources, because it has diversified its asset base, better ensuring a robust production pipeline. With a low debt profile, substantial cash reserves, and committed exploration spending, VAU is positioned for long-term growth and stability. Then there is the opportunity in Canada as well which we are yet to fully consider and comprehend.
A clear focus on operational efficiency and sustainable practices, further underscores VAU’s appeal as a resilient and growth-oriented investment. The latest quarterly produced by the company at least reaffirmed that view.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: VAU. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?