Vested in the electrification of everything

IPD (ASX:IPG) is a distributor of electrical equipment in Australia.
IPG consists of two core divisions - distribution of products (+90% of profits) and the provision of services.
The electrification of everything is a very strong narrative leading into 2023 and beyond. Supported by both the government and its citizens, IPG is on the frontline of critical work given the need to not only draw more from the grid, but to also do so more efficiently.
The replacement cycle which is currently underway is likely to continue and IPG should be beneficiaries of that.

Beyond servicing the renewable energy sector and Industrial communications, the company has an agreement with global electrics supplier ABB to sell EV infrastructure on behalf of them in Australia and New Zealand.
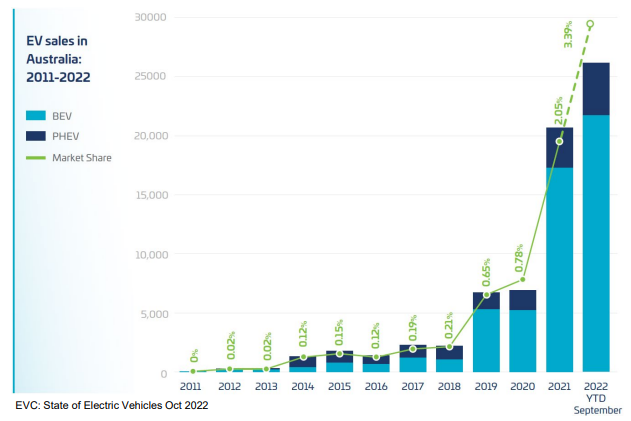
This offers an exciting opportunity for IPG given the expected uptake of EVs into the future and the urgent need to upgrade EV infrastructure. The company refers to this time as a "once in a lifetime opportunity" for them, and its difficult to disagree with that sentiment. The sale of EVs have jumped in Australia but still only account for around 3% of all new sales. This significantly lags the rest of much of the developed world. This gives the company runway for growth in a sector with very little in the way of direct competitors.
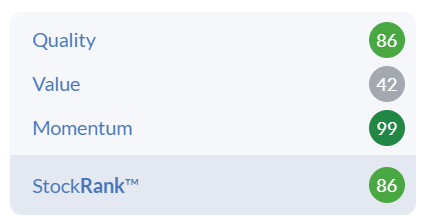
StockRank ™ score
The company only listed in late 2021, and it has maintained a StockRank TM above 80 for the entire time.

Looking at the current overall score of 86, this is slightly down on September 2022 figure when it most recently crossed back above 90.
However the score has since pulled back due mainly to the erosion of Value as the price has gone up. This is no better exemplified by the Momentum score of 99.
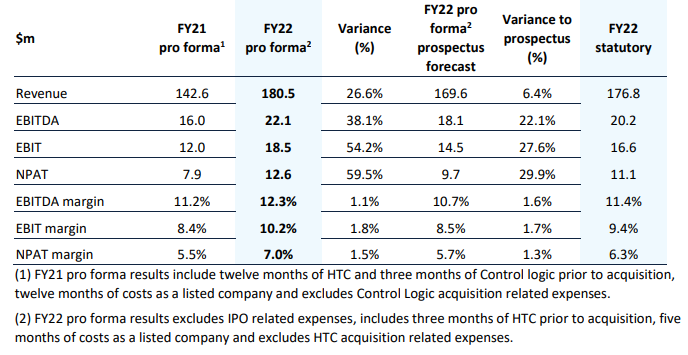
Pleasingly the company has been beating proforma expectations, 27% on the revenue line and 59.5% on the NPAT. This is the sort of return you would want to see from a new listing and its unsurprising that the early adopters have seen such a strong run.
Quality and Value
The company unfortunately has seen a lot of value gobbled up following the +150% price rise in the past twelve months. This has also reduced the expected forecast dividend to 2.98%, not that holders are too concerned by that.
Trading on a PE of 17x, EV of 12.6x further re-emphasises that the stock is not cheap. However should it meet expectations, maintain margins at current rates and hold an ROE above 20, then these elevated metrics will be supported.

Momentum
The standout element in this story is Momentum, both in price and analyst revisions.
However we note with interest that since the peak of early December the price is now 10% from its peak, offering a potentially more elegant entry for those keen on taking a position.
The broader trend of the stock is still well and truly up with relative price strength very strong over longer time frames.

A consoling fact may be that the recent pullback in price has not been supported by an increased spike in volume showing that those that hold the stock are not keen to part ways with it.
Support back to normal
IDG has a subsidiary business and team of 150 located in Colombo, Sri Lanka. Their role is specifically to support the Australian business.
In 2022 we saw civil unrest occur in Sri Lanka. This led the company to 'Pivot' to the Philippines to cover the.loss of capacity.
Now that operations have returned to normal in Sri Lanka, the company still has a skeleton presence of 11 staff in the Philippines in case of any emergencies. This strategy worked incredibly well delivering comfort to investors.
Financial Health
As the company has no debt and a growing cash balance, it is unsurprising to see both the AltmanZ score and the Piotroski scores in the safe zone.

One possibly worrying indicator is the M-score. The ranking is a little high suggesting possible earnings manipulation. In my view this is more a symptom of its recent listing and the mechanics of the calculation rather than anything sinister. Accruals look solid and operating cash flows for FY2022 were similar to profit. It will be interesting to monitor how this result progresses in the near term.
Liquidity and Ownership
One of the biggest challenges historically for investors is that the stock has been a little illiquid. However it has definitely picked up in recent times, particularly over November and early December 2022.
The company now has a market capitalisation of $250m, so despite the price recognition, it is still small enough to offer investors business growth potential.
Mohamed Yoosuff has been an employee and board member of IPD since 2005 Mohamed has held various roles within IPD and has been the CFO since inception. Mohamed, and wife Mary, are the major shareholders in the business owning 13% of all stock.
Pendal Group (6.7%).and Mirrabooka (3.1%) are amongst the fund managers on the register.
Outlook
I am yet to find anyone who can tell me that we will need less electricity, batteries or data centers in the near future, so the thematics driving the business remain strong.
In a recent presentation it further upgraded guidance expectations, now expecting revenue in the 1H23 to be 11% higher than 2H22, and profit to be 18% over the same period.
Perhaps most pleasing was that the company said, "Margins have remained strong, price increases from suppliers have been successfully passed on to the market."
This is reflected in the regular upgrade to analyst forecasts, though it is important to note here that there are only two analysts who cover the stock meaning it somewhat flies under the radar.

On top of the energy transition, the company sees 3 million EVs on the road by 2030, thus implying that the demand for the installation of chargers will explode.
Conclusion
Investors seeking exposure to the electrification of our lives can look to IPG as an option.
With macro growth thematic, strong business relationships and a strong balance sheet positioned for acquisitions, IPG is wired into the future industries of tomorrow with quality elements to support it.
_______
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
I just came across IPG, it looks strong with obvious tail winds. It is up 30% since Elio did his summary!!!
I have been invested in this stock since you highlighted it in Spotee. I has been a great investment for 2022 and hopefully for the future
Its future will be linked to the electrifying of the nation. Now I'm not a betting man, but...
Thanks for the support.
What is SPOTEE ??