VIT: Differentiated from the rest

Amid many of the thematic bubbles over time, one of the more recent cases has been in the Cannabis space. Its growing acceptance for medicinal use saw prices sore a number of years ago, only to see it all go up in flames as an insatiable thirst for capital, tiny industry moat and slower than expected regulatory acceptance saw many leave the space disappointed.
Which is why when I saw a profitable player in this space, it piqued my interest and have therefore decided to write about it today. The company is Vitura Health (ASX:VIT), previously known as Cronos, and is not your typical Cannabis play.
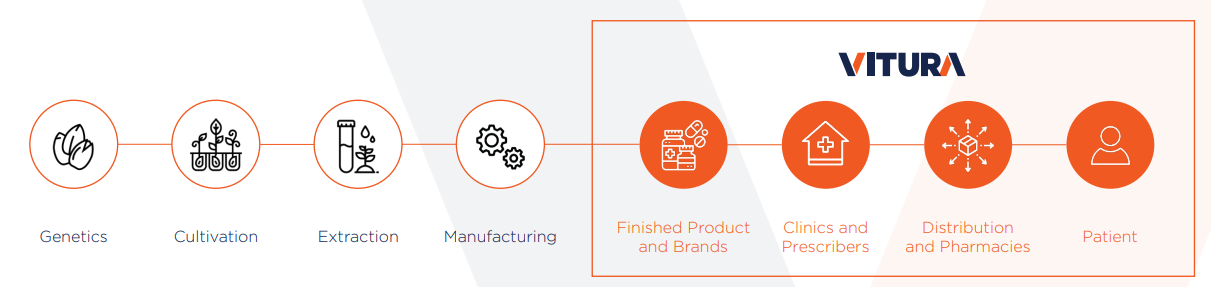
For one, as mentioned they are profitable and even pay a dividend! And second is that unlike the majority of the players in the space involved in the cultivation, extraction and manufacturing, VIT is involved predominantly in the distribution and clinical side of the downstream process.
The company is most well known, and receives the vast majority of its revenues from its CanView platform which operates Australia's largest regulated medicinal cannabis marketplace. It connects product manufacturers, practitioners, authorised pharmacies and customers. With some 200 products distributed on the platform it is rapidly becoming the place where suppliers are connected to customers. Vitura in the last half sold a record 450,000 medical cannabis units through its CanView platform, which was 130% higher than the pcp. So far, over 1 million units have been sold on the platform.The company is confident of reaching the 2.0 millionth unit milestone before the end of calendar year 2023.
The company also has its Clinics – CDA Clinics (in person) and Cannadoc (telehealth) to help support distribution. Excitingly the company entered a joint venture with a Canadian Firm to establish Cortexa, based in Melbourne, and is one of the only companies in the world able to supply validated psychedelics ready for patient use. In fact from the start of this financial year, medicines containing the psychedelic substances psilocybin and MDMA (3,4-methylenedioxy-methamphetamine) can be prescribed by specifically authorised psychiatrists for the treatment of certain mental health conditions. As a result of these regulatory changes, Cortexa is one of the only companies in the world able to supply validated MDMA and Psilocybin ready for patient use.
Overall the company in Stockopedia is rated 64, let’s see why and assess whether VIT is appropriate for investors who can stomach the volatility.

Quality
As alluded to in the introduction, VIT is rare in the cannabis industry, as it is actually profitable. Not only that but its performance metrics are quite outstanding, with Return on Capital 49%, Return on Equity 41% and Margins of 16%. This not only makes it a leader in its industry, but also places it in the upper echelon of companies across the entire market.

HINT: If you hover your mouse over one of the coloured bars you will see exactly where it sits relative to the industry/market.

However the company rates a 62 overall for Quality as it is dragged down somewhat by the Piotroski F-score of 5/9 and a Beneish M-score showing elevated potential for cash manipulation.
While these shouldn’t be ignored, a further exploration of each provides some answers. For example, within the F score an accounting amidst to the 2021 asset values (2 years) inflated ROA under the method Piotroski calculated it (using starting asset values not average as broader consensus is) so fast forward to today and it looks like profitability has dropped. Gross profit margins also declined,but are still quite high at over 36%
When looking at the Beneish M-Score leverage has risen yet most of that has contributed to intangibles. Further the company has been growing at quite a clip, and while this does not imply manipulation on its own, growth firms are more likely to manipulate because their financial position and capital needs put pressure on managers to achieve earnings targets.
HINT: Within the Piotroski F-Score, Bankruptcy Risk (Z-score) and Beneish (M-Score) clicking into it shows where the company passes and fails each criteria. Further, clicking on each criteria explains why the criteria is a pass or fail.

Therefore notwithstanding these measures for the moment, I suspect they will normalise come the coming full year financials. And should they improve, combined with the strong performance metrics (assuming those are maintained) the company could see a jump in its Quality score when it reports this month.
Value
Being the best looking house in a terrible street will mean you will garner the attention of most, and notwithstanding the fall from recent highs (I will speak to that in the next section) the stock is trading on somewhat lofty valuations. That said they are not nose bleed, should you be able to reconcile in your mind that simply by the nature of the CanView platform, intangible assets are a stalemate of businesses like this. I take heart from the EV/EBITDA of 14.7, PE of 13.1 and the one analyst who covers the company has a price target way above the current price (whilst no certainty - it is nice to see.)
Further, the price has fallen over 50% since its recent high, which has taken much of the previous steam out of the valuation - while still lofty, anecdotally a fall of this magnitude is a good place to assess the prospects of a growth business without the hype artificially lifting the price.
The price pullback has made the current yield more attractive, though still modest at 2.% forecast. Investors will hope the yield can grow along with the business. Though that will depend on future capital expenditure.
Momentum
Interestingly this is the Factor that scores highest for VIT at 84. Obviously most investors would look at the price decline from the high of $0.96 in October last year to today and wonder why this may be the case? Well the stock is still up on the 12 months, and price is above the 50 day moving average.
From an Earnings Momentum perspective, the 2023 earnings per share was upgraded by some 11% in June which does contribute to the overall score.
However price has been a challenge since the highs and shows signs of a price getting ahead of itself. But what does it look like from here?

The stock has been in a downtrend since the peak of October last year. A series of lower highs and lower lows confirms as much. It is important to note that a price is in a downtrend until it is not, therefore what news to happen here is,
Price gets above $0.595 (the previous lower high)
Pulls back from that level
Then a position can be taken assuming the pullback keeps the price above the previous higher low. (assuming the price rises from here that would be $0.475 cents
Whether you wish to be this pedantic, or whether you wish to jump in on the fundamental growth story, until prices crosses above $0.595 it will still be in a downtrend. How aggressive you choose to be may be helped by understanding what is happening with broader market sentiment at any time.
I also note the spike in volume on 19th May. That was due to a block trade of 18,750,000 shares in the Company conducted by Director Guy Rothwell Headley, a substantial shareholder in the Company and co-founder of CDA Health Pty Ltd that was merged to form Vitura.
The transaction occurred in consultation with the Company. The transaction represented approximately 14% of Mr. Headley’s overall beneficial shareholding was the first time he sold shares in the Company, and gave the indication that he doesn't intend to sell any more for the moment. (FYI that trade left $2.8M on the table - but I digress.) Since then, volume has stabilised and it would appear that normal trade has resumed.
Ownership
Which takes us to ownership and the VIT (Previously known as Cronos) merged with CDA in 2021 is still reflective on the shareholders list with many related parties remaining major shareholders.

In fact, when delving deeper to look at the free float less than a quarter of the stock is available.

Despite this though there is sufficient trade for most retail investors to get in and out - And on the surface the company looks well held by insiders which should provide some confidence
It is important to note however that the merger of Cronos and CDA Health has taken some time to meld. Despite the obvious benefits, former founders have taken it upon themselves to air dirty laundry in public. This was to come to a head in the 2022 AGM until all parties smoked a peace pipe (pardon the pun) and on November 28, 2002 an announcement was made saying all had resolved their issues. That said, the market will likely keep discounting the stock until confidence returns. The block trade described in the momentum section contributes to the continued jitteriness for now and investors will continue to watch this space (perhaps even more than the fundamental performance).
The company has said, “We have an aligned board and management, with proven execution capability to deliver on the strategy” - we shall see. (Editor note: The emphasis was placed on aligned by the company.)
As a further note, members may note the significant increase in shares on issue in recent times. While typically a point of concern, in this instance much of it was to do with the coming together of two companies. Therefore best to pay attention from the figure since 2021.
Outlook
The company believes that it has a rosy future ahead of it. It points to the fact that currently only some 3% of GPs are on the CanView platform. This already contributes $56.8M in revenue over the last half… so the potential to win a larger share of GPs could result in an exponential increase in revenue.
With the company reporting its financials shortly, investors will be keen to hear progress on the company’s primary targets for the year which included growing the GP network beyond the 920+ registered prescribers, and increasing sales from a larger investment in the sales team. Any progress on the recent new business line and the opportunity there.
The growing acceptance of the use of medicinal cannabis for patients which should provide a natural tailwind, given the platform VIT have established.

Source VIT half year report
It is difficult to find a cloud on the industry horizon with sales of medicinal cannabis products market forecast to exceed $400m by end CY20221 to which VIT could take a clip of the ticket. The company also believes it has a deep competitive moat around their specific business model (unlike their competitors), with a current dominant market position. One which it hopes it can further build on with its clinics (both CDA Clinics and Cannadoc) onboarding additional patients to the platform.


Also while still in its infancy the JV with PharmaAla (Cortexa) aims to be the leading supplier of psychedelics, GMP MDMA and GMP psilocybin, for research and therapeutic use in Australia. Under the deal, initially all Products will be imported from Canada, Cortexa’s will have an exclusive licence to the manufacturing technology and IP. While we are yet to see the size of ramp up cannabis acceptance has received, given the tone of many scholarly journals, it won’t take long to catch up. On the plus side as a cash positive business, VIT should be able to support this using internal funding - though it may come at the expensive of short term dividends - so keep an eye on this.
Conclusion
The fact VIT is profitable and growing differentiates it amongst most traditional stocks in this space. Whilst the growth opportunities ahead of it are clear, what the market will continue to watch are the moves amongst major shareholders. Can they remain harmonious for long enough to see VIT reach its full price potential?
Investors will hope so, and while the price previously got ahead of the fundamentals and saw the subsequent big pullback, with continued growth expected, investors will now hope that price can revert back to the size of the opportunity.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
7 comments
It’s always good to read articles on companies which are way off my usual watch list targets. The ROCE & ROE is what piqued my interest. BTW Elio, you must have been ‘off your head’ when you used that ‘smoked the peace pipe’ expression. Humour is what makes crusty research an interesting read. Well done.
I try to entertain :-)
Thanks Elio for highlighting this company. I had the impression that Cannabis bubble had burst, VIT may be the AMAZON in their field...
I have a small position in this one. While the next report for Vitura Health (ASX:VIT) isn't due until the end of August, I'm hoping that it will show continued growth.
The TGA reports on the number of patients who are prescribed medicinal cannabis under the authorised prescriber scheme. The reporting dashboard is available here. The data indicates strong growth in the sector, including in the first half of this year. That should bode well for the upcoming report, I expect (hope).
Thanks Grandslam for the contribution of that link. Very insightful indeed!
Am I reading this report correctly? 746k of new cannabis clients in a six month period - that’s nearly 3% of the Aussie population.
Good point. I had another look at the dashboard and it does acknowledge that where a patient is prescribed multiple categories of medicinal cannabis, that they'll be counted twice.
The overall trend (comparing recent figures to past periods) is strongly upwards however, which gives me some confidence that they should have the wind at their back for the short to medium term.