Volex – Providing Solutions for the Digital World
Welcome back to the Stock Pitch series. Today, I’ll be covering an industrial company that many Stockopedia investors are probably quite familiar with. The stock is Volex (LON:VLX). Fresh off the back of a strong trading update, and currently commanding a StockRank of 88, could it be worth a closer look?
Disclosure: At the time of publication, Ed Sheldon had no position in VLX.
- Share price at the time of publication: 586p
- Market cap: £1.1bn
The Pitch
Volex is a UK-headquartered manufacturer of integrated high-performance power and connectivity solutions for mission-critical applications. Operating 23 manufacturing sites globally, it produces power cords, plugs, connectors, receptacles, high-speed data transfer cables, custom wiring harnesses and cable assemblies, and more.
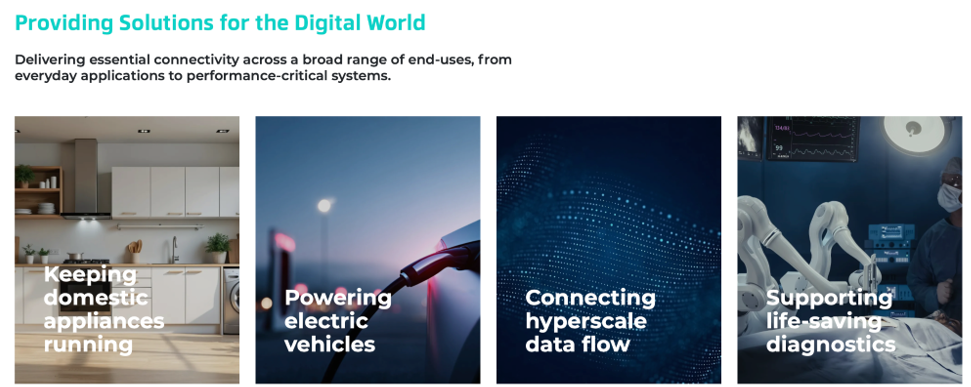
At its core, Volex’s strategy centres on providing solutions for the digital world. Today, the company is focused on five key markets:
- Complex Industrial Technology (approx. 30% of FY2026 revenue): Here, it serves the data centre, aerospace/defence/space, robotics and automation, and industrial manufacturing markets.
- Electric vehicles (15%): Volex supports the EV market with innovative power and charging solutions.
- Medical Devices (13%): Volex supplies components used in diagnostic imaging, surgical equipment, and patient monitoring.
- Consumer Electricals (20%): Volex’s products support everyday electronics in homes worldwide.
- Off-Highway (22%): Volex provides ruggedised power and interconnect solutions for off-highway vehicles in industries such as defence, mining, agriculture, and infrastructure.
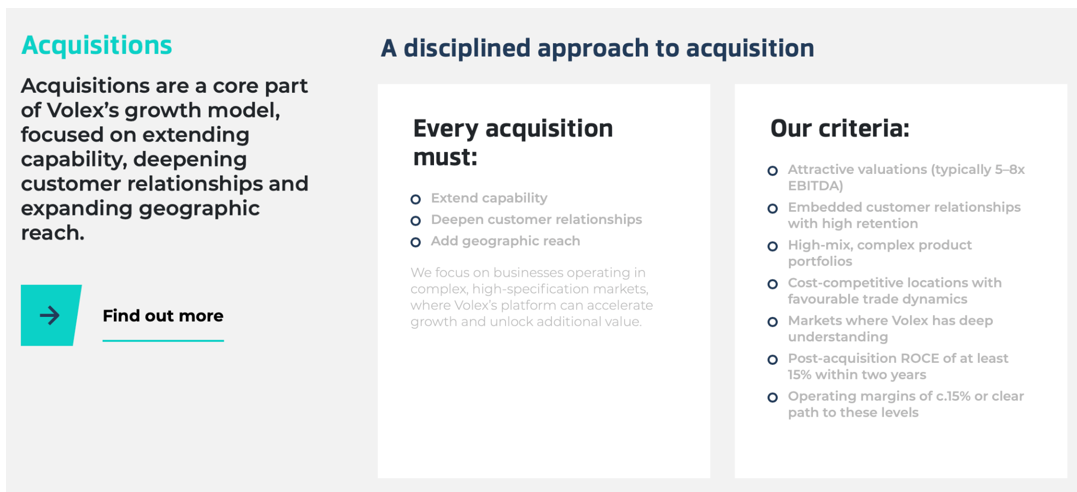
Note that acquisitions play a key role in Volex’s strategy; they are used to acquire capabilities or market positions that strengthen the organic growth flywheel. Over the last eight years, it has acquired 12 different businesses.
The Big Picture
Volex has built a business that is exposed to a range of ‘secular’ growth industries. These include:
- Data centres: Between 2026 and 2030, the data centre industry is projected to add nearly 100 gigawatts (GW) of new power capacity, roughly doubling current infrastructure.
- Electric vehicles: Worldwide annual EV sales are expected to hit roughly 40 to 45 million units by 2030, up from over 17 million in 2024.
- Healthcare: Within the healthcare industry, demand for diagnostic and imaging systems and surgical robotic systems is projected to rise in the years ahead.
- Defence: NATO members have committed to significantly higher levels of defence spending by 2035.
- Infrastructure: The US is currently undergoing a major infrastructure boom, fuelled by the tech revolution, the energy transition, reshoring of critical industries, and federal legislation.
The growth of these markets in the coming years should provide tailwinds for the company. Add in potential growth from acquisitions, and higher margins as the company moves up the complexity curve, and there’s scope for substantial revenue and earnings expansion.
“The markets we operate in are niche and fragmented, and all display strong structural growth characteristics. Our expertise has allowed us to build market-leading positions, creating a resilient business through the cycle. By moving up the complexity curve in every market, we improve margins and raise the barriers to entry.”
(Volex FY2026 results)
Going Deeper
Over the last decade, Volex has established a solid growth track record. Helped by acquisitions, revenue has climbed from $320 million to $1,243 million while underlying profit before tax has risen from $7.2 million to $108.4 million.
Looking ahead, the company is targeting $2 billion of revenue at a 12% operating margin in the medium term, along with a return on capital employed (ROCE) of around 20%. In FY2026, operating margin was 10.2% (versus 2.8% in FY2017).
In its most recent update, on 25 August, the company told investors that it was off to a ‘very strong start to FY2027 with profit expected to be ahead of market expectations.’ For the four-month period ended 31 July, it generated 28.0% constant currency organic revenue growth, thanks to a strong performance in its Complex Industrial Technology division – where data centre customer demand was high.
It’s worth noting that the 28.0% year-on-year growth rate partly reflected a prior-year comparator in which revenue built progressively as new data centre programmes ramped up. Over the remainder of FY2027, headline year-on-year growth rates are expected to moderate as this effect annualises.
Looking beyond the growth here, other attractions from an investment perspective include:
- Solid balance sheet: As of 31 March, net debt was only $152.3 million.
- Decent ROCE: Volex has generated an average return on capital employed of around 14% over the last five years.
- Well-covered dividends: Volex pays a small dividend, but coverage is high so there is scope for larger payouts.
- Buybacks: In April, the company announced the launch of an on-market share buyback programme to purchase up to £40 million of its ordinary shares.
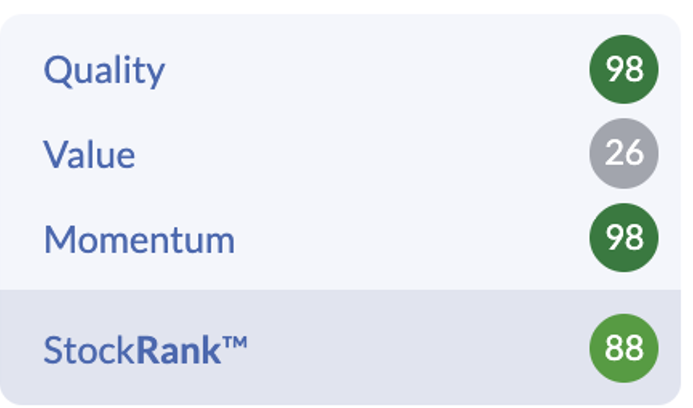
- High Stockopedia Quality rating: Volex currently scores 98 for Quality.
- Reasonable valuation: With analysts forecasting EPS of 49.7 cents this financial year, the P/E ratio is around 16.
- Main Market listing: On 24 July, Volex’s shares moved from the AIM to the LSE Main Market. This could broaden the range of potential investors in the company.
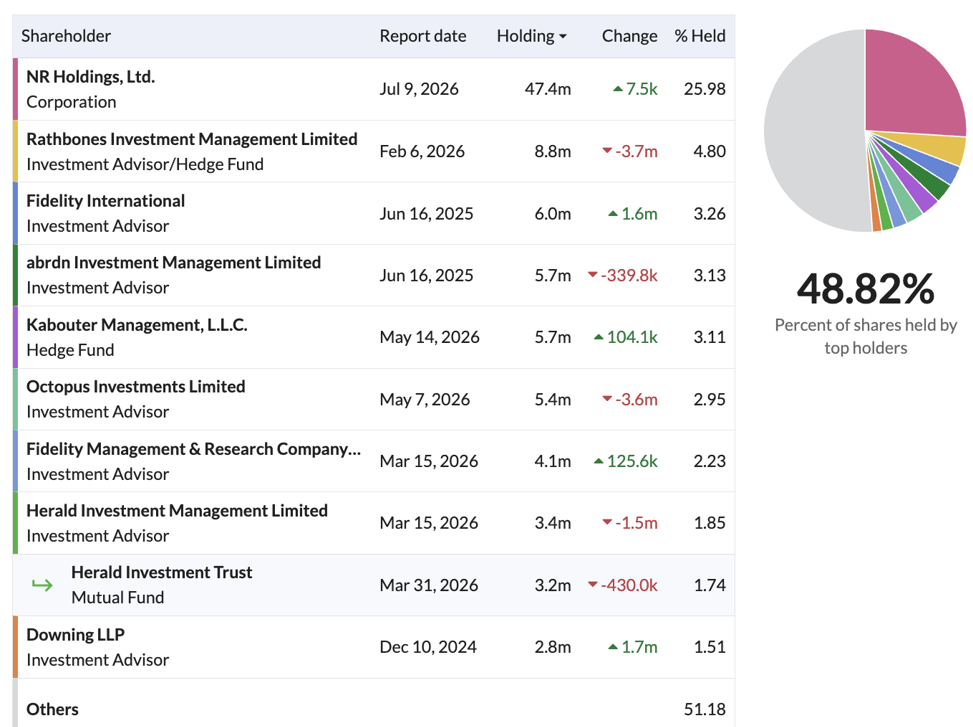
- Management’s interests are aligned with those of shareholders: CEO Nat Rothschild owns around 26% of the company’s shares.
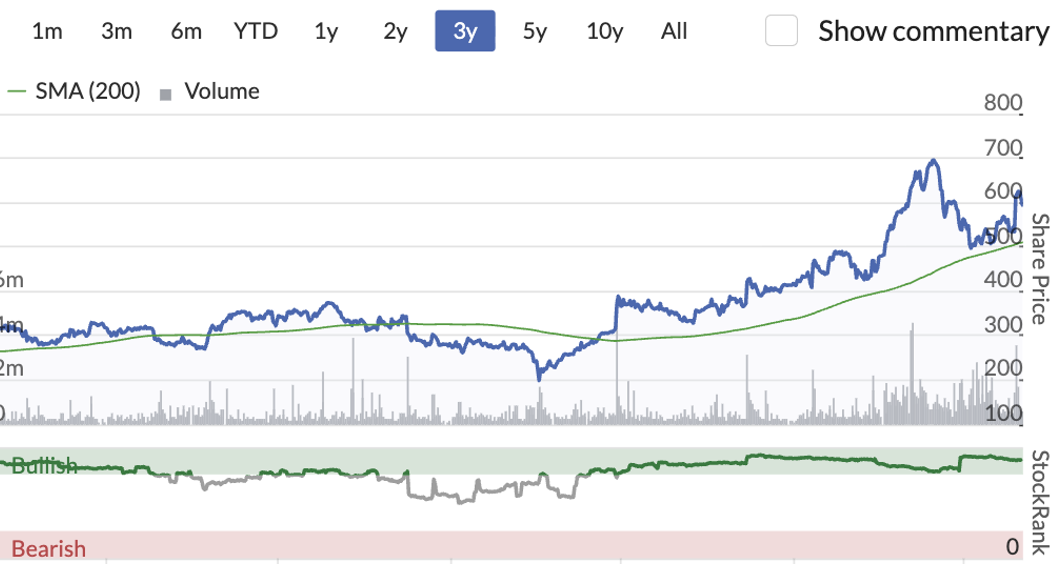
Turning to the technicals, the stock got a bit ahead of itself earlier in the year amid a surge in interest in AI infrastructure stocks. However, it has since experienced a pullback.
At current levels, it is:
- Above key moving averages: It is sitting above both the 50-day and 200-day moving averages.
- Not in overbought territory: The RSI is about 58.
- Scoring well for Momentum: Volex currently has a Stockopedia Momentum score of 98.
What the Brokers Say
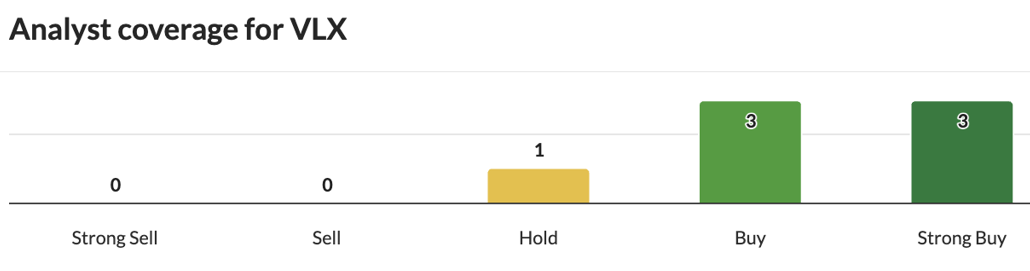
Broker sentiment is bullish:
- Multiple Buy ratings: Currently, the stock has six Buy or Strong Buy ratings.
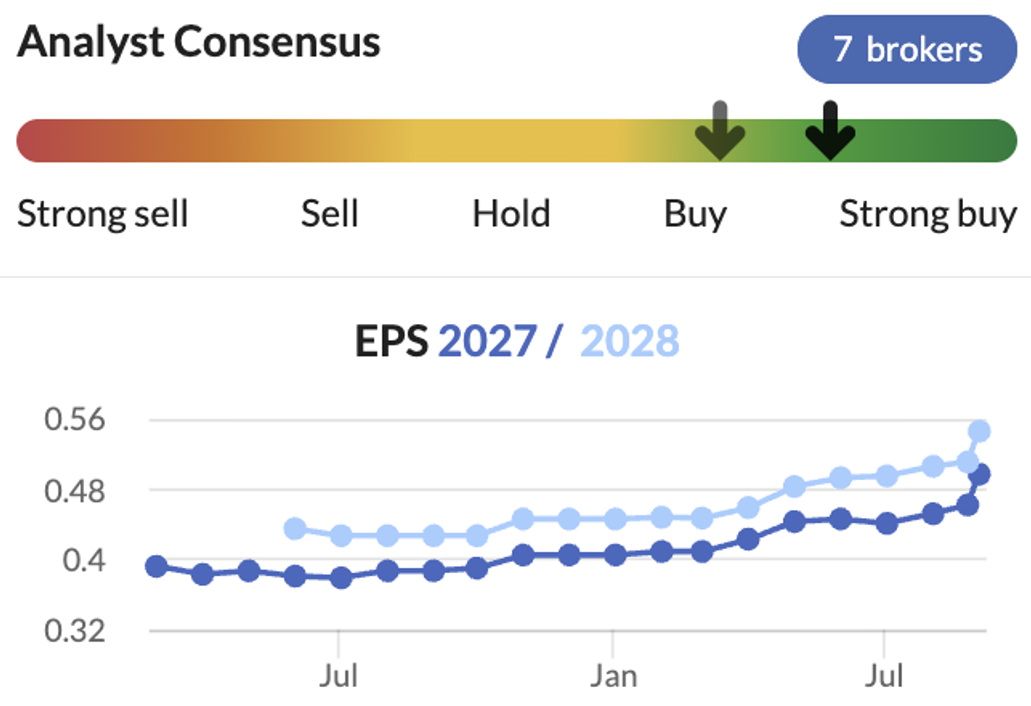
- Upside potential: The average analyst price target is roughly 20% above the current share price.
- Rising EPS forecasts: Over the last year, EPS forecasts have been trending up.
The Bear Case
As always, there are many risks to consider:
- Cyclical trends within secular growth markets: While Volex operates in secular growth industries, these industries can exhibit cyclicality at times, and an economic slowdown could temporarily derail the growth story.
- Data centre resistance: The ‘Not In My Backyard’ movement has been gaining traction recently.
- Supply chain risks: Input price fluctuations (e.g. copper) and tariffs are ongoing risks.
- Failed acquisitions: Overpaying for an acquisition, failing to realise cost synergies, or struggling to integrate systems across newly acquired entities are a possibility.
- Key-man risk: Over the last decade, CEO Nat Rothschild (formerly Executive Chairman) has been instrumental in the company’s success.
- CEO stock sales: Nat Rothschild owns 26% of the shares so if he was to sell down his position, it could put significant pressure on the stock.
The Bottom Line
Overall, the set-up here looks attractive, in my view. At current levels, Volex shares are offering growth at a reasonable price.
An economic slowdown is a risk, as are value-destructive acquisitions. Taking a long-term view, however, the company looks well positioned to generate both top- and bottom-line growth.
Disclosure: At the time of publication, Ed Sheldon had no position in VLX.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Thanks Ed for that comprehensive review. It was a similar review by Jack Brumby here that made me first look at Volex and I bought in Jan. 2020 and added since. It has become my 4th. largest holding.
The only thing I would add is that anyone wants to further research Volex a good place to start is the Capital Markets Day on 22/4/26 :
Having achieved its five-year plan to FY27 a year early, the following new medium-term growth ambitions were put forward:
$2bn of revenue, including:
o Organic revenue growth of $500m
o c. $300m of revenues added from targeted M&A
12% EBIT margins
20%+ return on capital employed
A recording of the event is available here: https://www.volex.com/investor...
Thanks for the write up Ed and what a great job the management have done.
Volex is proof that well run companies that remain focussed on their markets and invest wisely can deliver exceptional returns for investors. First bought into Volex 10 years ago and have watched them grow - they seem particularly adept at capturing emerging opportunities for their products which is good news for the future.
I think it has outperformed many of the US tech Titans over the last decade.
With that compelling case Ed, I am amazed you don't have a position! (I hold)
I have owned the stock in the past grumpy5. Sold it too early annoyingly. I may get back in soon!
By all accounts - Data Centres alone will provide massive opportunities for Volex - In the UK alone there are plans for something like 100 such builds, many in Scotland.
As announced today, Volex (LON:VLX) will be added to the FTSE250 on September 21, so should see some index buying between now and then
US peers have reported strong data centre growth in Q2 of 30-60%, so expect strong interim results and margin accretion given that data centre revenue has 25% EBIT margin vs ~10% for the remainder of the business.
US comps trade at 20-30x PER although they are significantly larger, but at mid teens PER I think there is still good multiple upside to Volex.
I hold.
Great write-up!
A lot to like here: niche, easy to understand industries/products, invested management, reasonably priced...