Volkswagen's drivers: premium cars & China

Volkswagen has the leading market share in China's car market and is benefiting from a recovery in European demand. The main profits driver for the group is the fast growing premium car brands of Audi and Porsche. The valuation is not expensive but the cyclical nature of car demand makes the shares volatile.
Volkswagen is something of a “car conglomerate" with it covering the full spectrum of the market. Skoda and Seat are value brands while Volkswagen passenger cars are mid-market and generate the bulk of group sales.
At the top end of the market are Porsche, Audi, Lamborghini, Bentley, Bugatti and Ducati motorcycles. Volkswagen also has a strong position in trucks and buses with it owning the brands Scania and MAN.
Volkswagen's twelve brands

Source: Volkswagen investor presentation
In 2014 the main driver of sales volumes for was the Europe/Other markets region at 4.4m vehicles while Asia Pacific came in at 4.1m. North America saw only 0.88m cars sold and South America came in at 0.79m in 2014.
This reflects the weak position of the volume brands like Volkswagen and SEAT in the United States – the world's second largest car market. However, the premium brands of Audi and Porsche are successful around the world.
China is world's largest car market and is has seen the rapid pace of sales growth start to moderate. In the January to October 2014 Volkswagen's market in China was 21% which is double the market share of its nearest competitor.

Source: Volkswagen investor presentation
Premium cars are set for higher sales growth than the global car market due to rising income per capita. This is illustrated by the success of Audi in China which has seen sales increase rapidly since 2007.
Audi sales in China: deliveries up six-fold since 2007

Source: Volkswagen investor presentation
Volkswagen's profit drivers
Looking at operating profits (excluding China) in 2014 and Audi made a €5.15bn contribution while Porsche came in at €2.7bn. Volkswagen Passenger cars generated €2.5bn of operating profits and in Scania came in at €1bn.
Total operating profits (excluding China) were €12.7bn in 2014 with premium cars the key contributors. Adding in the Chinese joint venture and total operating profit came in at €17.9bn in 2014 which highlights China's importance.
Volkswagen has been a growth story since 2007

Source: Volkswagen investor presentation
Volkswagen's recent performance
The weakness of the Volkswagen passenger car brand in the United States appears to be the cause of a recent boardroom bust up. The premium brands, though, are performing well and will support profits growth.
In 2014 Audi sales volumes were up 10.5% to 1.4m and sales of Porsche rose by 20.6% to 187,000. In the first quarter of 2015 sales of Audi were up 6.1% on a year ago while Porsche sales jumped 32.2% to 51,100 vehicles.
On a geographic basis the recovery in Western Europe is helping to boost sales as the Chinese market slows down. Total car sales in the European Union increased by 5.7% in 2014 to 12.55m vehicles – the first annual gain for six years.
R&D spending to stay ahead
Volkswagen is the world's largest spender on research and development in the world with €11.5bn spent in 2014. Much of this is focused on developing alternative drive trains and more efficient vehicles.
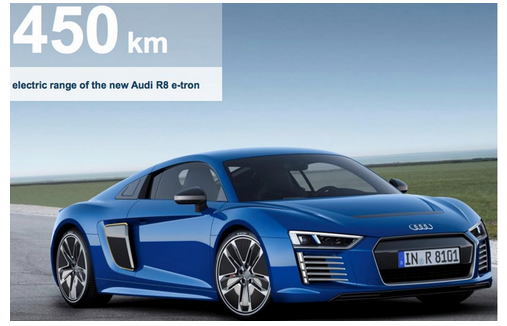
Audi and Porsche are rolling out plug-in-hybrids while Volkswagen passenger cars has launched two electric vehicles: the e-Golf and the e-Up! At the recent Geneva motor show the all-electric Audi R-8 e-tron was also announced.
Source: Volkswagen investor presentation
Summary and valuation
Volkswagen has lots of moving parts but what stands out is its leading position in China and the importance of its high margin premium brands. As Europe's largest carmaker the group is also benefiting from the Eurozone's recovery.
A power struggle at the top has seen Volkswagen's share fall back recently with the board backing the incumbent CEO. To address investor concerns the company has embarked on a €5bn cost cutting programme.
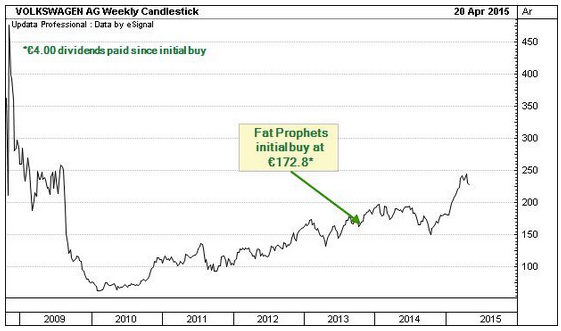
Earnings per share rose by 17% to €21.9 (€18.6 in 2013) and in 2015 will be supported by the weak euro. The 2014 dividend was up 20% to €4.8 per share (ex-div on 6th May) which is a payout of 21.2% versus a target of 30%.
The forecast P/E ratio for 2015 is 9.8X which is a discount to BMW on 11.5X and Daimler 12X. For 2017 the forecast P/E for Volkswagen is 8X which compares to 10.5X for BMW and 10X for Daimler AG.
Euro weakness will boost Volkswagen in 2015
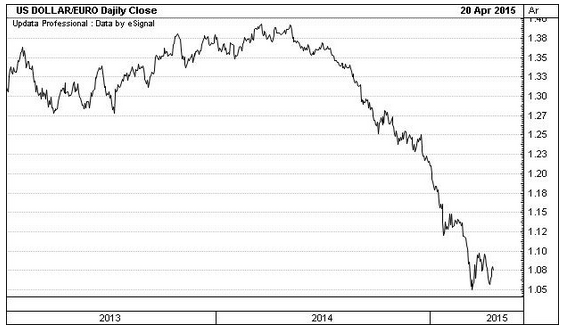
Volkswagen has a lower valuation than its German peers due to a portfolio that includes lower margin, volume brands. The P/E discount increases to a fifth by 2017 which suggests that the shares offer medium-term value.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?