Warren Buffett, Novy-Marx and the Metaphysics of Quality
Readers of the Seventies hippie bestseller, "Zen and the Art of Motorcycle Maintenance" may remember long, interminable digressions into the nature of "Quality". For those that haven't read it, the book describes the author's journey with his son by motorcycle from Minnesota to California. Along the way, the author (Robert Pirsig) recalls his past self as a young man, who he calls Phaedrus. Phaedrus is a gifted teacher of creative writing at a small college, who becomes obsessed with the question of what defines good, or "quality". These philosophical investigations eventually drive him insane, leading to him being subjected to a particularly nasty episode of electroshock therapy.
A cautionary tale perhaps for those that spend too much time meditating on Quality - it can hurt your brain. But when it comes to investing, it sure feels like the concept needs a bit of intellectual elbow-grease.
What do we really mean by Good / Quality?
There have been reams upon reams written about value investing. About the pros and cons of different value measures. Entire forests have been sacrificed for the sake of disecting metrics like the price/earnings ratio, the price/book ratio, free cash flow yield, or the price/sales ratio! So we know, pretty much inside out, what "cheap" means. But, in contrast, the concept of "good" is much more fuzzy!
Many have noted that Warren Buffett, the world's most famous investor, has evolved from just being a Graham-style bargain value investor to.... something else but what is that exactly? Buffett still likes cheap but he also likes good, high quality businesses. As he wrote:
"It’s far better to buy a wonderful company at a fair price than a fair company at a wonderful price”.
But what does he really mean by wonderful? What signals quality? As we've discussed, Buffet-esque Quality is tied up with ideas like a good management team, a differentiated product, a good "economic moat", or barriers to entry.
Well yes, but these all seem like rather vague and subjective notions, aren't they? They lie in the eye of the beholder. One man's first class CEO may be another man's joker. A seemingly unbreachable economic moat may look narrow to someone else. Is there a way of making quality a bit less... well less qualitative?! Is it possible to find quantitative signals that tell us that we're dealing with a quality business? Said another way, what objectively defines a company like Apple as being "great"?
How Much Quality Matters
On this front, there's been some interesting - but rather troubling - recent work by Robert Novy-Marx of the University of Rochester. In a 2010 paper called “The other side of value: Good growth and the gross pro?tability premium”, Novy-Marx looked in depth at one measure of quality, namely “gross profitability” defined as Gross Profit divided by Assets. His work found that companies in the top fifth of the market based on this measure returned 0.33% per month more than those in the bottom fifth. His conclusion: High quality firms generated significantly higher average returns than low quality firms, despite having high valuations on average.
Interestingly, Novy-Marx found that the gross profits/assets ratio is actually more predictive than widely used earnings- and cash flow-based valuation metrics. He notes that:
"in a horse race between these three measures of productivity, gross profits-to-assets is the clear winner".
Furthermore, Novy-Marx shows that this so-called Quality Effect is independent of - and highly additive to - both the Value Effect and the Momentum Effect. We have ourselves yet another stock market anomaly, it seems.
Gross Profits: Are You Frickin' Serious?
This is puzzling stuff. From a common sense business perspective, gross profits feels to us like a fairly crappy measure of quality. What gross margin tells you is how profitable the business is before subtracting all expenses apart from the cost of sales. That's it. It just nets off the cost of the materials or labor used to make the products/services sold. So forget about SG&A, i.e expenses not directly related to sales such as rent, lease, utilities, salary, marketing, etc. And R&D investments that companies make in developing new and better products or services. And interest, taxes, and depreciation.
Instinctively, you would have thought a measure like ROCE to be a far better test of Quality. There's a great discussion on why sustainable ROCE make so much sense which I won't bother to replicate now but, as Warren Buffet notes in his 1992 letter:
"Leaving the question of price aside, the best business to own is one that over an extended period can employ large amounts of incremental capital at very high rates of return.
The one really good argument Novy points forward in favour of Gross Profits to Assets is that, unlike other metrics, quality focuses on the top line rather than the bottom line. As such, it is a relatively "clean" measure of economic pro?tability. The farther down the income statement one goes, the more polluted pro?tability measures become, and the less related they are to true economic pro?tability.
That's a fair point but the idea that you can judge two companies before their SGA & other costs are taken into account still seems crazy. The kind of thing that would only have been conjured by someone with no experience of running a business. Some companies have an economic moat entirely based around their sales techniques - including their marketing and advertising techniques.
Furthermore, there are also huge differences across industries. In some industries, like clothing for example, gross profit margins are expected to be near the 40% mark, as the goods need to be bought from suppliers at a certain rate before they are resold. In other industries such as software product development, since the cost of duplication is negligible, the gross profit margin can be higher than 80-90% in some cases. Does that mean that technology investments are inevitably higher quality? Admittedly, we are going thorugh a major digital transition to an online world at the moment, but, intuitively, that idea makes no sense.
However, there's intuition and then there's empirical data and it's hard to argue with this stunning chart from the Novy Marx paper:
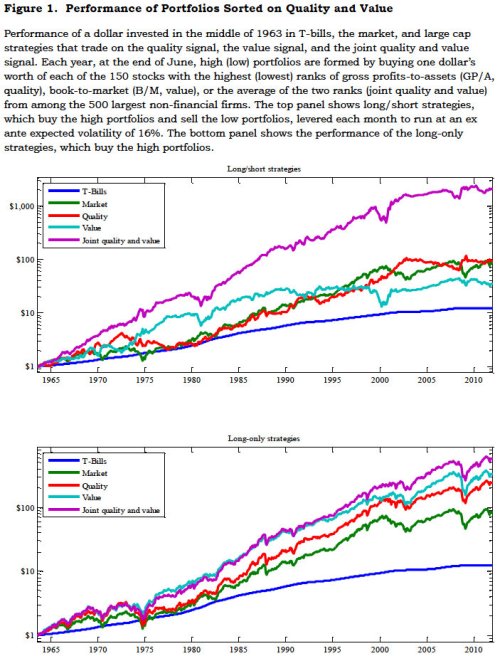
Novy's work does seem to picking up an important effect. Maybe there's a bit of data mining oddness or misinterpretation going on here (we discuss the danger of data snooping here) but none of these qualms seem to have stopped AQR Capital from jumping on this particular bandwagon. The Wall Street Journal reports that Greenwich-based asset manager is set to launch a set of investment funds based specifically on Novy-Marx's research.
Ok but just show me the list...
So, notwithstanding some reservations, we'd never want to spoil a good party and we've now added Gross Profits to Assets by popular demand to our screening library. We've set up a demo screen like that here so users can tweak and play around with it (it can be sorted by value or profitability). According to Jason Zweig at the WJS, Novy Marx defines good bargain priced quality stock candidates as having a quality ratio above 33% and a price to book value below 1.7, although those values don't really seem to tie back to the paper. For that reason, we've also added some rank bands on each ratio (which can be tweaked up and down), plus an optional positive momentum criteria, which is a departure from the paper but in line with the "factor" thinking.

Although the usual DYOR caveats obviously apply, some interesting names that grace the screen includes the likes of Low and Bonar (LON:LWB), National Express (LON:NEX), Huntsworth (LON:HNT), Inpellam (LON:IPEL) and Speedy Hire (LON:SPD). You can see the full list here.
The Truth is Out There...
In fairness to Mr Novy-Marx, he weighs up Gross Profitability against a range of other quality strategies, including our old friend the Piotroski F-Score, in another excellent 2012 paper called "The Quality Dimension of Value Investing". In a subsequent post, we'll be looking at how Novy's measure stacks up these other measures, and - in turn - the rationale for the mix of elements we've chosen in our own QualityRank. Unless, of course, we are subjected to electroshock therapy in the meantime!
Further Reading
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
This is an excellent article. I don't know the answer either. This has been something that I have spent many years thinking about. I am no closer to a simple measure of quality. I have just re-read Phillip A Fisher's "what to buy - 15 points to look for in a common stock" - point 5 he talks about profit margin. But this is just one point, earlier he also talks about the products the company makes, and whether it is in a growing market, whether the returns are not going to be competed away. And this is something that is very hard to deduce just by reading the annual report.
Novy-Marx might not be capturing quality at all but rather operational gearing. So, a software company can add additional sales with little extra cost or use of capital. Autonomy plc generated gross margins in the mid 90s which is not uncommon in the sectors, but high gross margins to do necessarily equate to a wide and deep moat. Technological change will bridge many moats in time.
I feel more comfortable using a measure of profitability which captures more of the costs of doing business. The problem is which form of earnings to use. The accounting treatment of intangibles has turned this into a minefield. Increasingly, I use EBITA (so after depreciation) less the cash spend on intangibles in the year (sourced from the cashflow statement). As for the denominator, I prefer to use total assets less goodwill and acquisition related intangibles (goodwill reclassified).
I am not clear how Novy-Marx and Stockopedia have chosen how to define total assets.
Thank you for a thought-provoking article, although like you I am incredibly sceptical about the use of this metric not only for the reasons given above, but also due to problems with the actual meaning of "gross profit" which is vague and so I would dispute the idea that it is a "clean measure".
One of the problems is that accounting standards is not prescriptive about the use of the term gross profit, and furthermore allows expenses to be classified in different ways according to either their nature (e.g. cost of goods, staff costs) or their function (sales, administrative) etc. As a result the definition is very subjective and comparing between companies is incredibly problematic.
A good example is if we take the company listed first on your gross profit to assets screen, AGA Rangemaster (LON:AGA). If you actually look at its annual report the term "gross profit" doesn't appear anywhere in the report, never mind in the income statement. So what do the financial databases do in this situation? Go to the notes to the accounts and pick up the figure for "Raw materials, consumables and changes in inventories of finished goods and work in progress" resulting in a gross margin for AGA of 60%. That sounds incredibly impressive until we take off all the other operating costs an find that its operating margin was a measly 2.7%. Would you therefore describe AGA as profitable?
Now take an example such as Next (LON:NXT). This company does use the term gross profit in its income statement and its gross margin is 31%. However, this is not what people might ordinarily think as being "gross profit" since it is not reflective of the profit achieved on sale of merchandise which is far higher. The usual practice with retailers is to include within cost of sales the significant expenses associated with running all the stores: staff costs, rents and other store overheads. Clearly, this is a totally different concept to that used for AGA which was only taking cost of inventories into account; but because this is the company's definition of gross profit the financial databases will tend to use it. So the gross profit margin for Next is about one half of AGA, but its underlying operating margin is several times higher at 18%.
I haven't read all of Novy-Marx's paper, but I wonder whether he deals adequately with these issues of actually getting a consistent definition of gross profit, otherwise in my view the whole concept is totally flawed. Whilst at best it might be of use for companies within very similar businesses which have developed specific industry best practice for expense classification, as between sectors it will be of little or no use.
For me, return on capital will continue to be a far more meaningful universal measure of quality which is less likely to be flawed by your very well described problems of data mining. Rather than try to find a less meaningul but "cleaner" alternative, one would be better off focusing their time on how to normalise the measurement issues with ROCE.
Best,
MI