Webinar: Britain's Stock Market on Sale
First, a quick apology. Five minutes into last night's webinar, our webinar platform went down - we couldn’t stream and the team couldn’t even access the backend. That's never happened to us before - and while the failure was at our service provider’s end, I know how maddening it was for everyone who had set aside some time to join us live. Sorry!
Anyway, Roland and I stayed on and immediately recorded the webinar in full as a video. It's was up on YouTube by 8:30pm last night - and you'll find it alongside the slides on the webinar event page:
We put a lot of preparation into this, so I hope you'll find an hour to watch over the weekend. Below is a quick tour of what we covered - and I hope this post can be a place for discussing the themes.
The backdrop: Britain on sale and breaking out
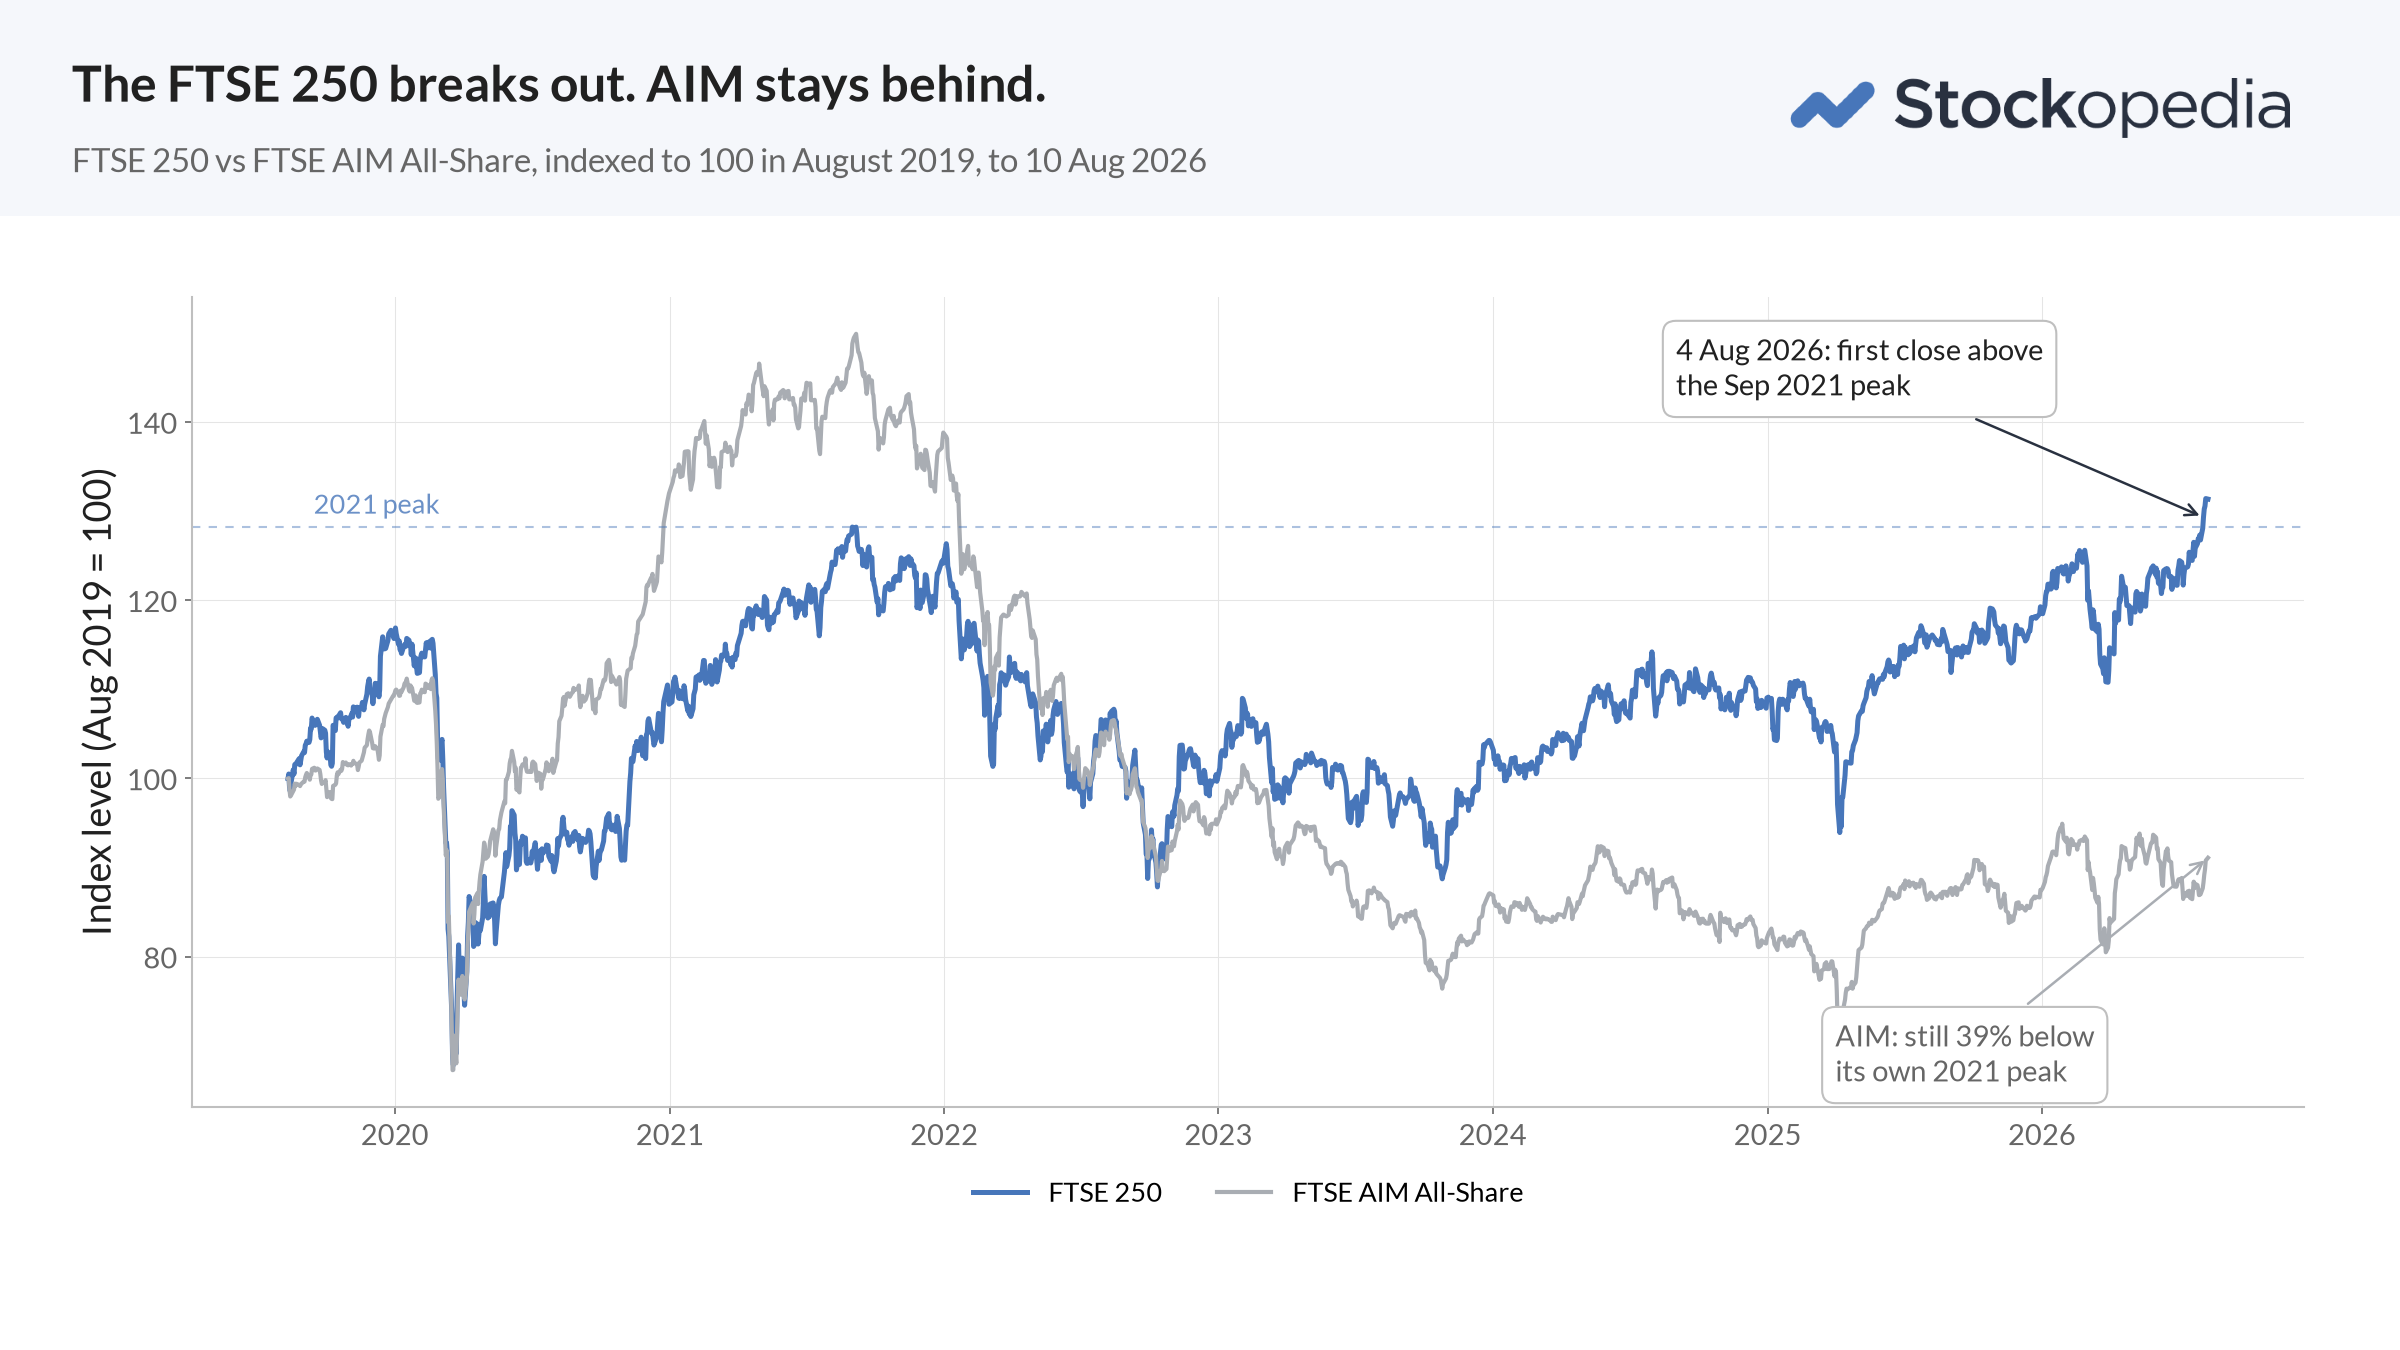
The spine of the webinar is what I wrote about last week on the site (here): the FTSE 250 has just broken out to its first all-time high in five years. UK shares still trade at roughly a 20% discount to comparable international markets, there were 23 takeover bids in the last three months, and companies are buying back their own shares at a rapid pace.
If trade buyers and private equity have noticed how cheap Britain is - then it should give us all confidence that there’s still a lot of value in UK equities. Of course, there’s one corner lagging - the AIM index, which is still 39% below its pandemic peak - which Roland and I do discuss.
Our analyst team has been focusing on mid-cap names recently. They've published nine FTSE 250 stock pitches this year, and all nine are up - on average by +38% - with 2 more written up in the last fortnight. We talked through a few of them. Roland pitched Raspberry PI Holdings (LON:RPI) in April, very soon after it had jumped 42% in a single session - which definitely took nerve - and it rallied another 43% since. Mark pitched CMC Markets (LON:CMCX) in March - earnings forecasts have roughly doubled this year, from about 24p to 52p, and it's still on around 12 times earnings. Meanwhile Keller (LON:KLR) , quietly digging the foundations for the world's data centres, has prominently featured in webinars and editorial all year, and is still telling the market it’s doing well.
Ramsdens Holdings: a textbook case study
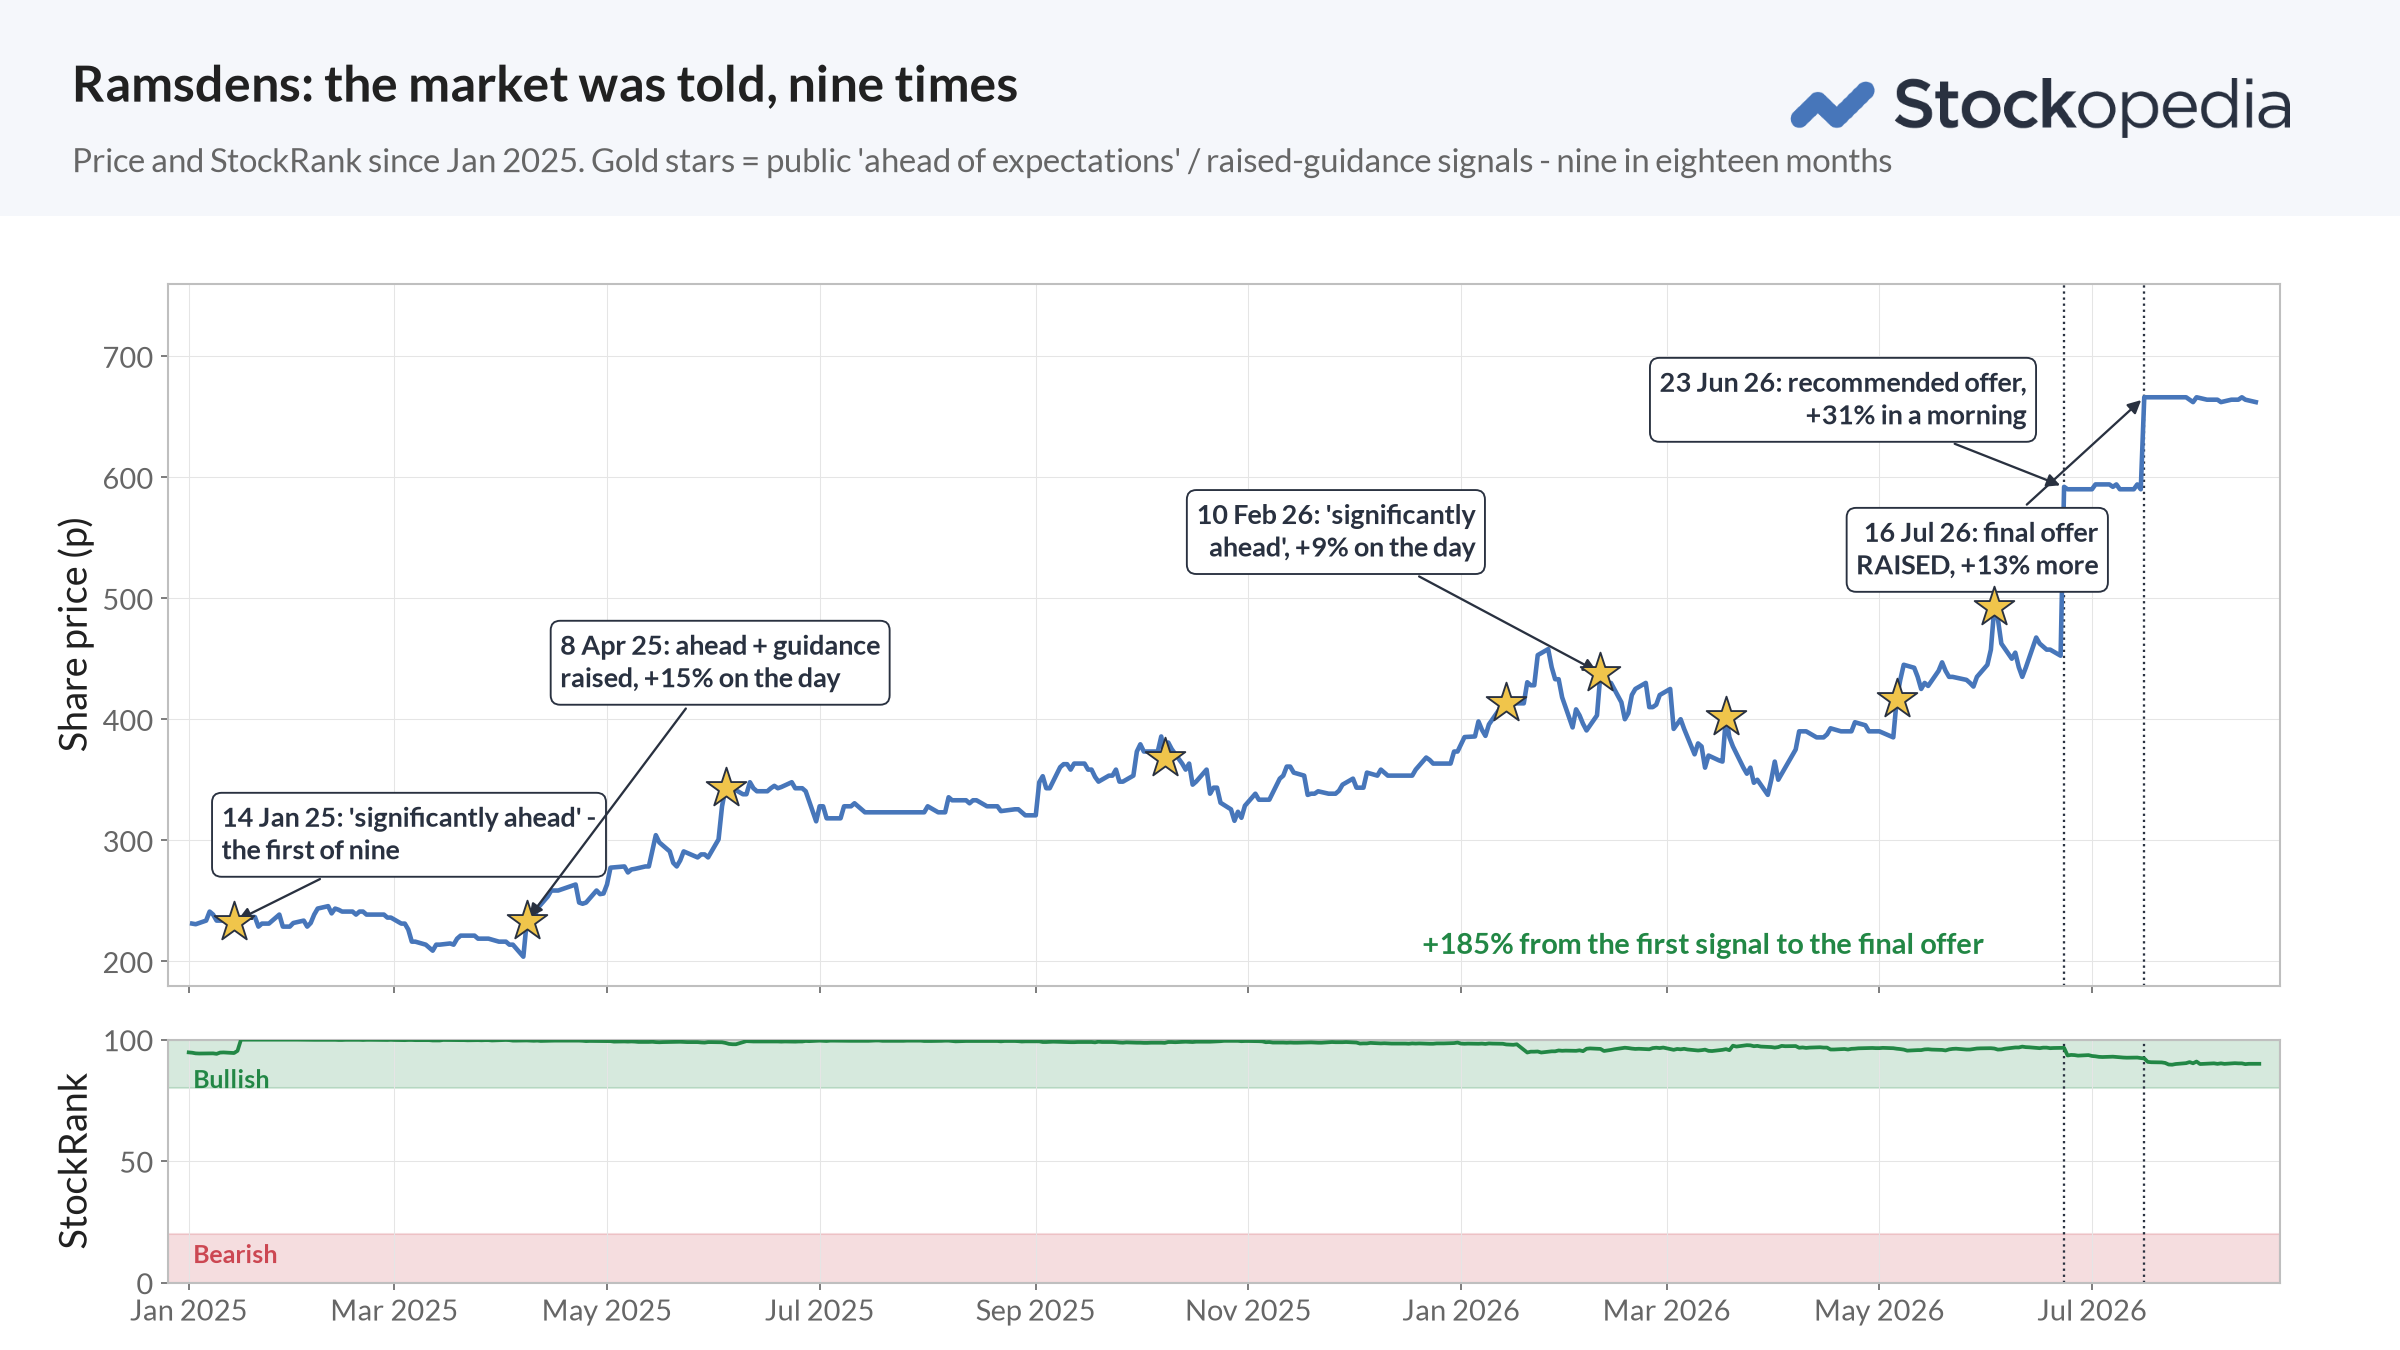
We dug into Ramsdens Holdings (LON:RFX) as this year’s perfect example of all the signals we zero in on at Stockopedia. Nine times in eighteen months, the company told the market it was ahead of expectations or raising guidance, while the StockRank was in the 90s throughout.
I think most people thought "pawnbroker, gold play", shrugged and moved on. But in June a trade buyer bid for the stock (just as they did for H&T) and the shares jumped +31% - raising its final offer by another 13% in July. From the first “significantly ahead of expectations” signal to the final offer, the shares gained +185%.
The principle does generalise - we’ve seen the same ideas play out in Keller, CMC and others all year. More than that we ran the numbers on 111 guidance upgrades this last quarter - shares popped by around 5% on that day’s trading regardless of StockRank, but 80+ ranked names continued to drift a further +6.5% afterwards. Winners do keep winning - and the signal is always in the news - the readers of the Daily Reports can get a real edge.
The growth stock corner
To show these points in action - we discussed four smaller growth stocks - across the StockRank range - some more speculative than others.
Two low ranked stocks:
- Rentguarantor Holdings (LON:RGG) - revenue up 250% year on year in the first half, with the Renters' Rights Act providing a real tailwind. Still loss-making, and on a valuation Graham has called "bonkers" on current numbers - but justified if the forecast growth comes through.
- Seeing Machines (LON:SEE) - who provide driver-monitoring systems, now required in new cars sold in the EU. Volumes are inflecting, but a convertible refinance is due in early October. A binary situation - not one for me, but I know many do follow this story closely.
Two higher ranked stocks beating expectations this week providing digital contracts:
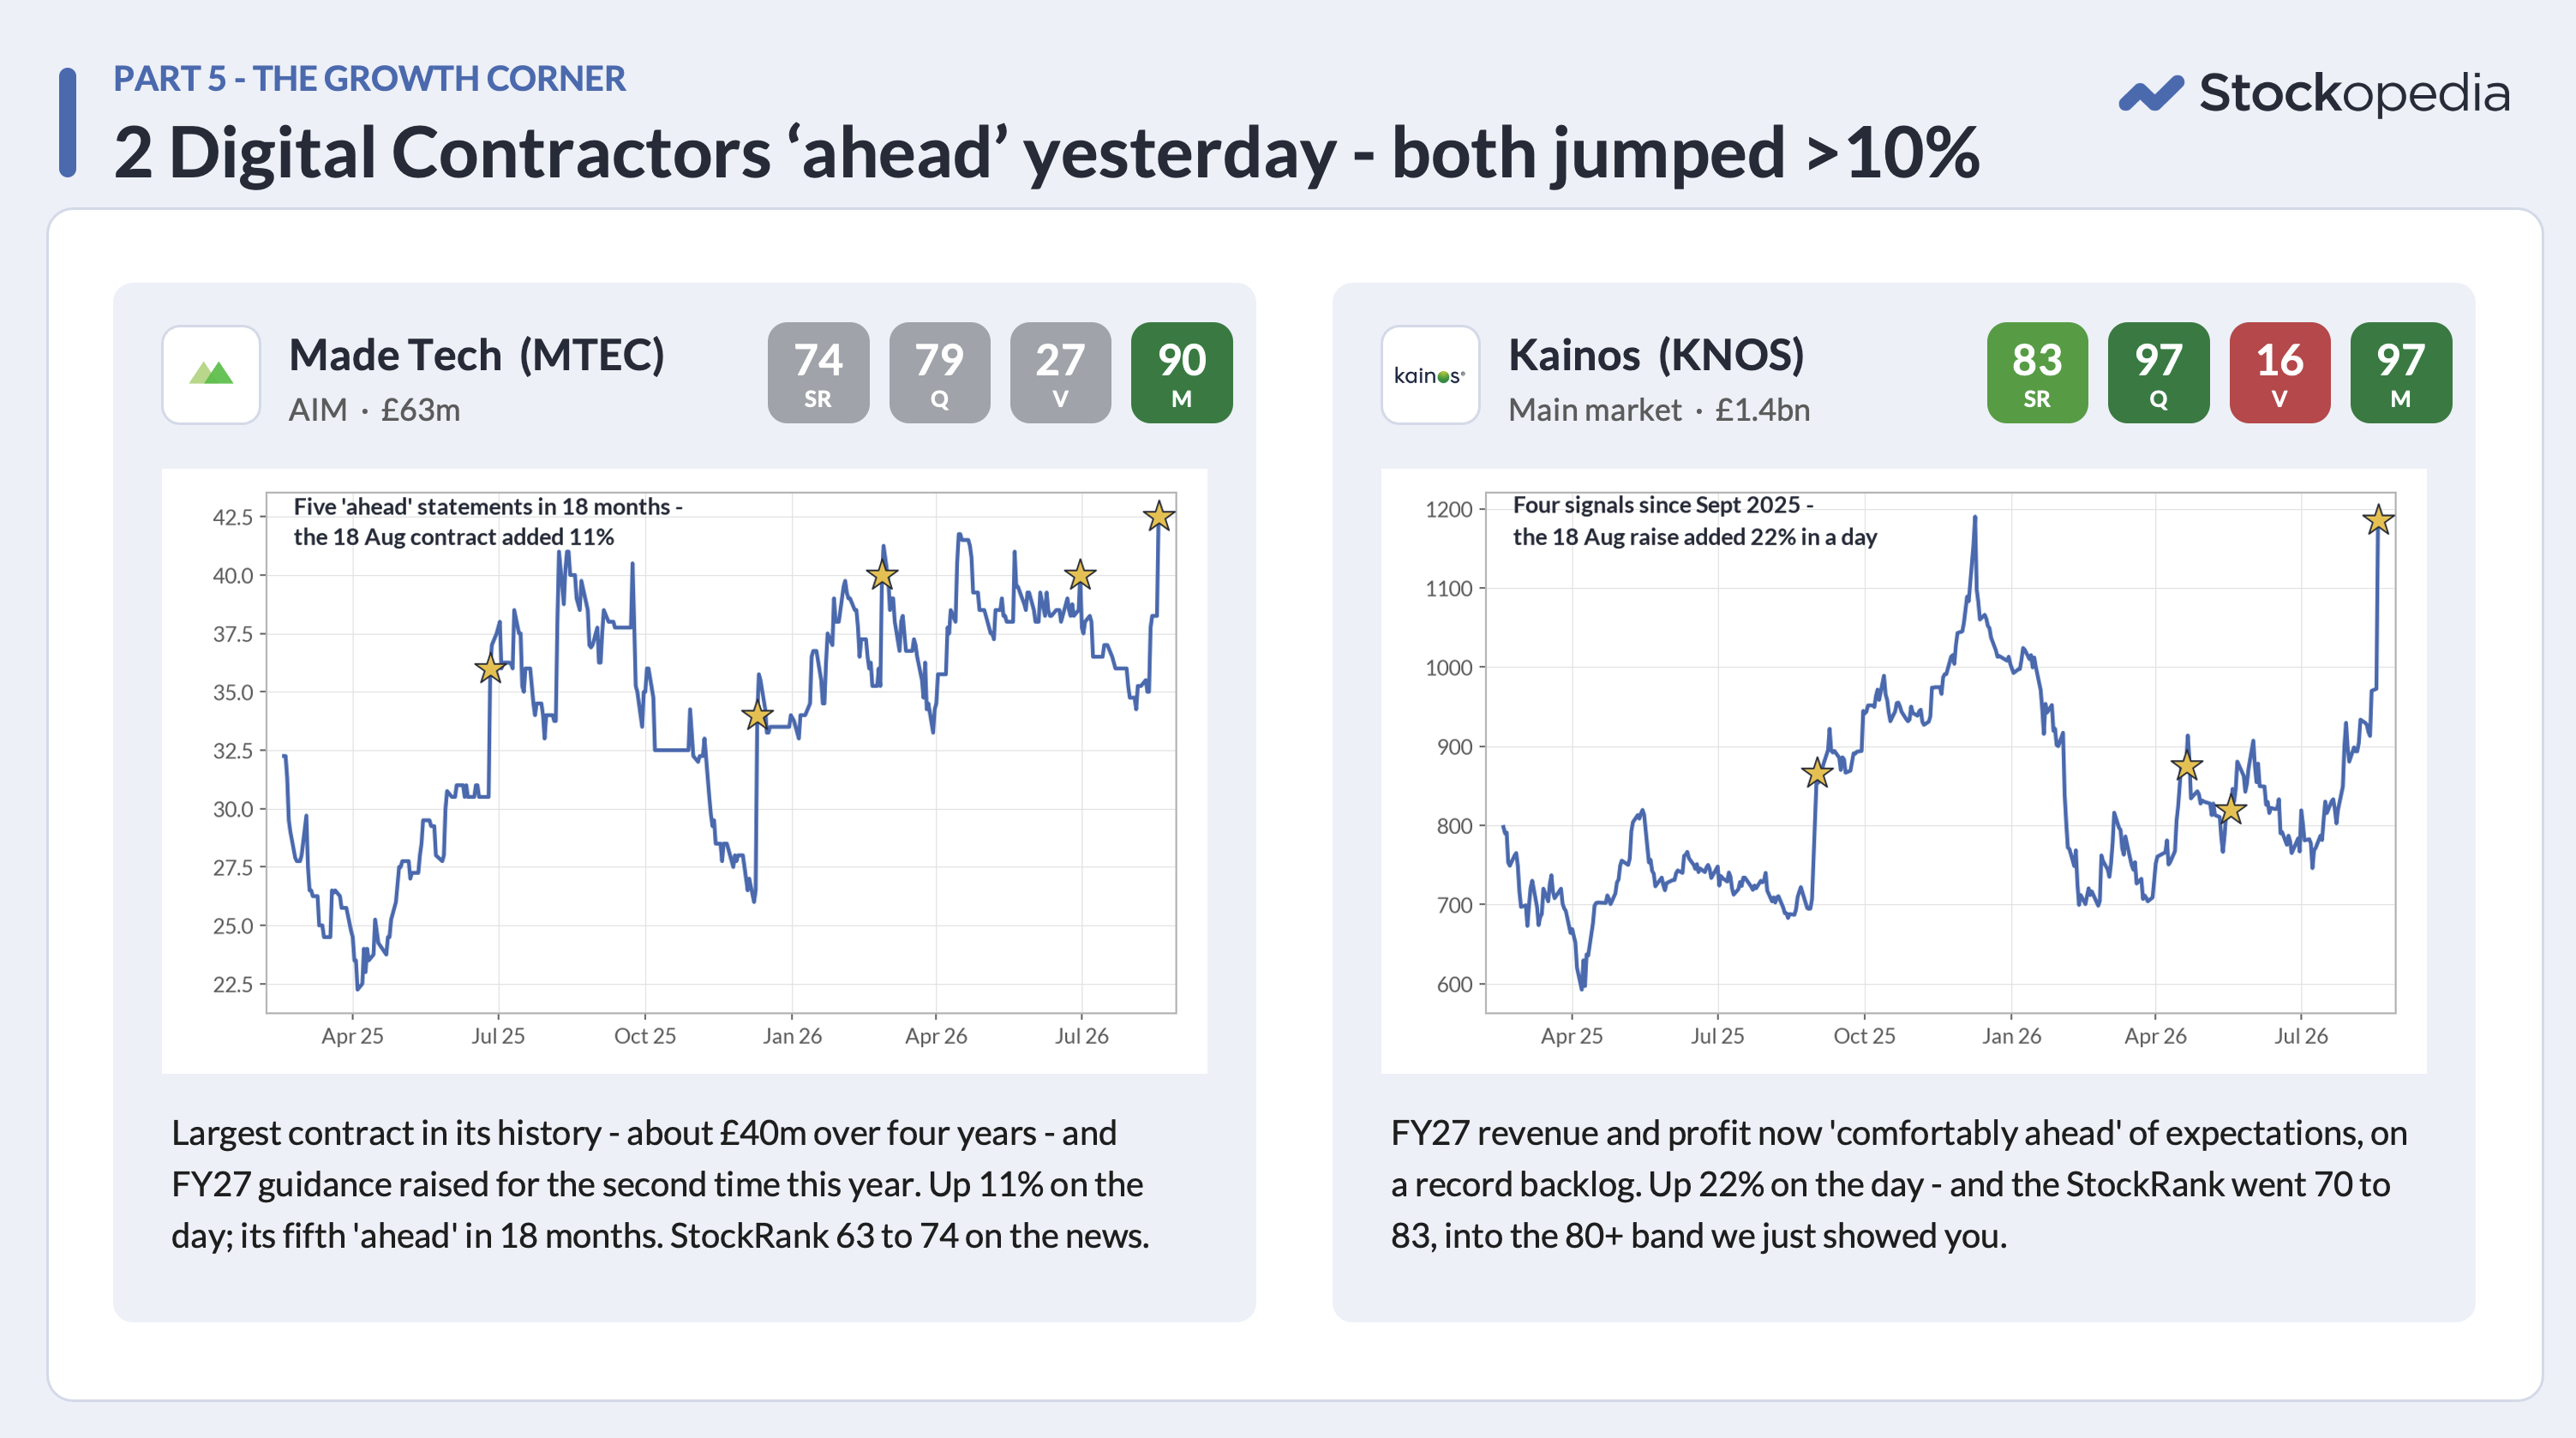
- Made Tech (LON:MTEC) - announced the largest contract in its history on Tuesday and upgraded guidance for the second time this year, its fifth "ahead of expectations" statement. I've held this one a long while - it finally looks to be breaking out.
- Kainos (LON:KNOS) - told the market it would be "comfortably ahead" and jumped 22% on the day. Not a share I’m hugely familiar with, but still on the digital contractor theme. Another in this vein is Tpximpact Holdings (LON:TPX) - the highest ranked of all of them.
The housebuilders - is there an early turning point?
I have written a couple of newsletters about the housebuilders in recent weeks. And have spotted an anomaly. Yes eight of eleven listed housebuilders trade well below tangible book value, and the six majors average about 0.7 times book against a 13-year average of 1.6 times. Deep Value alone isn't necessarily enough, though as you often end up owning Value Traps or worse for years. Returns on capital in the sector have more than halved and the valuation discounts are arguably deserved.
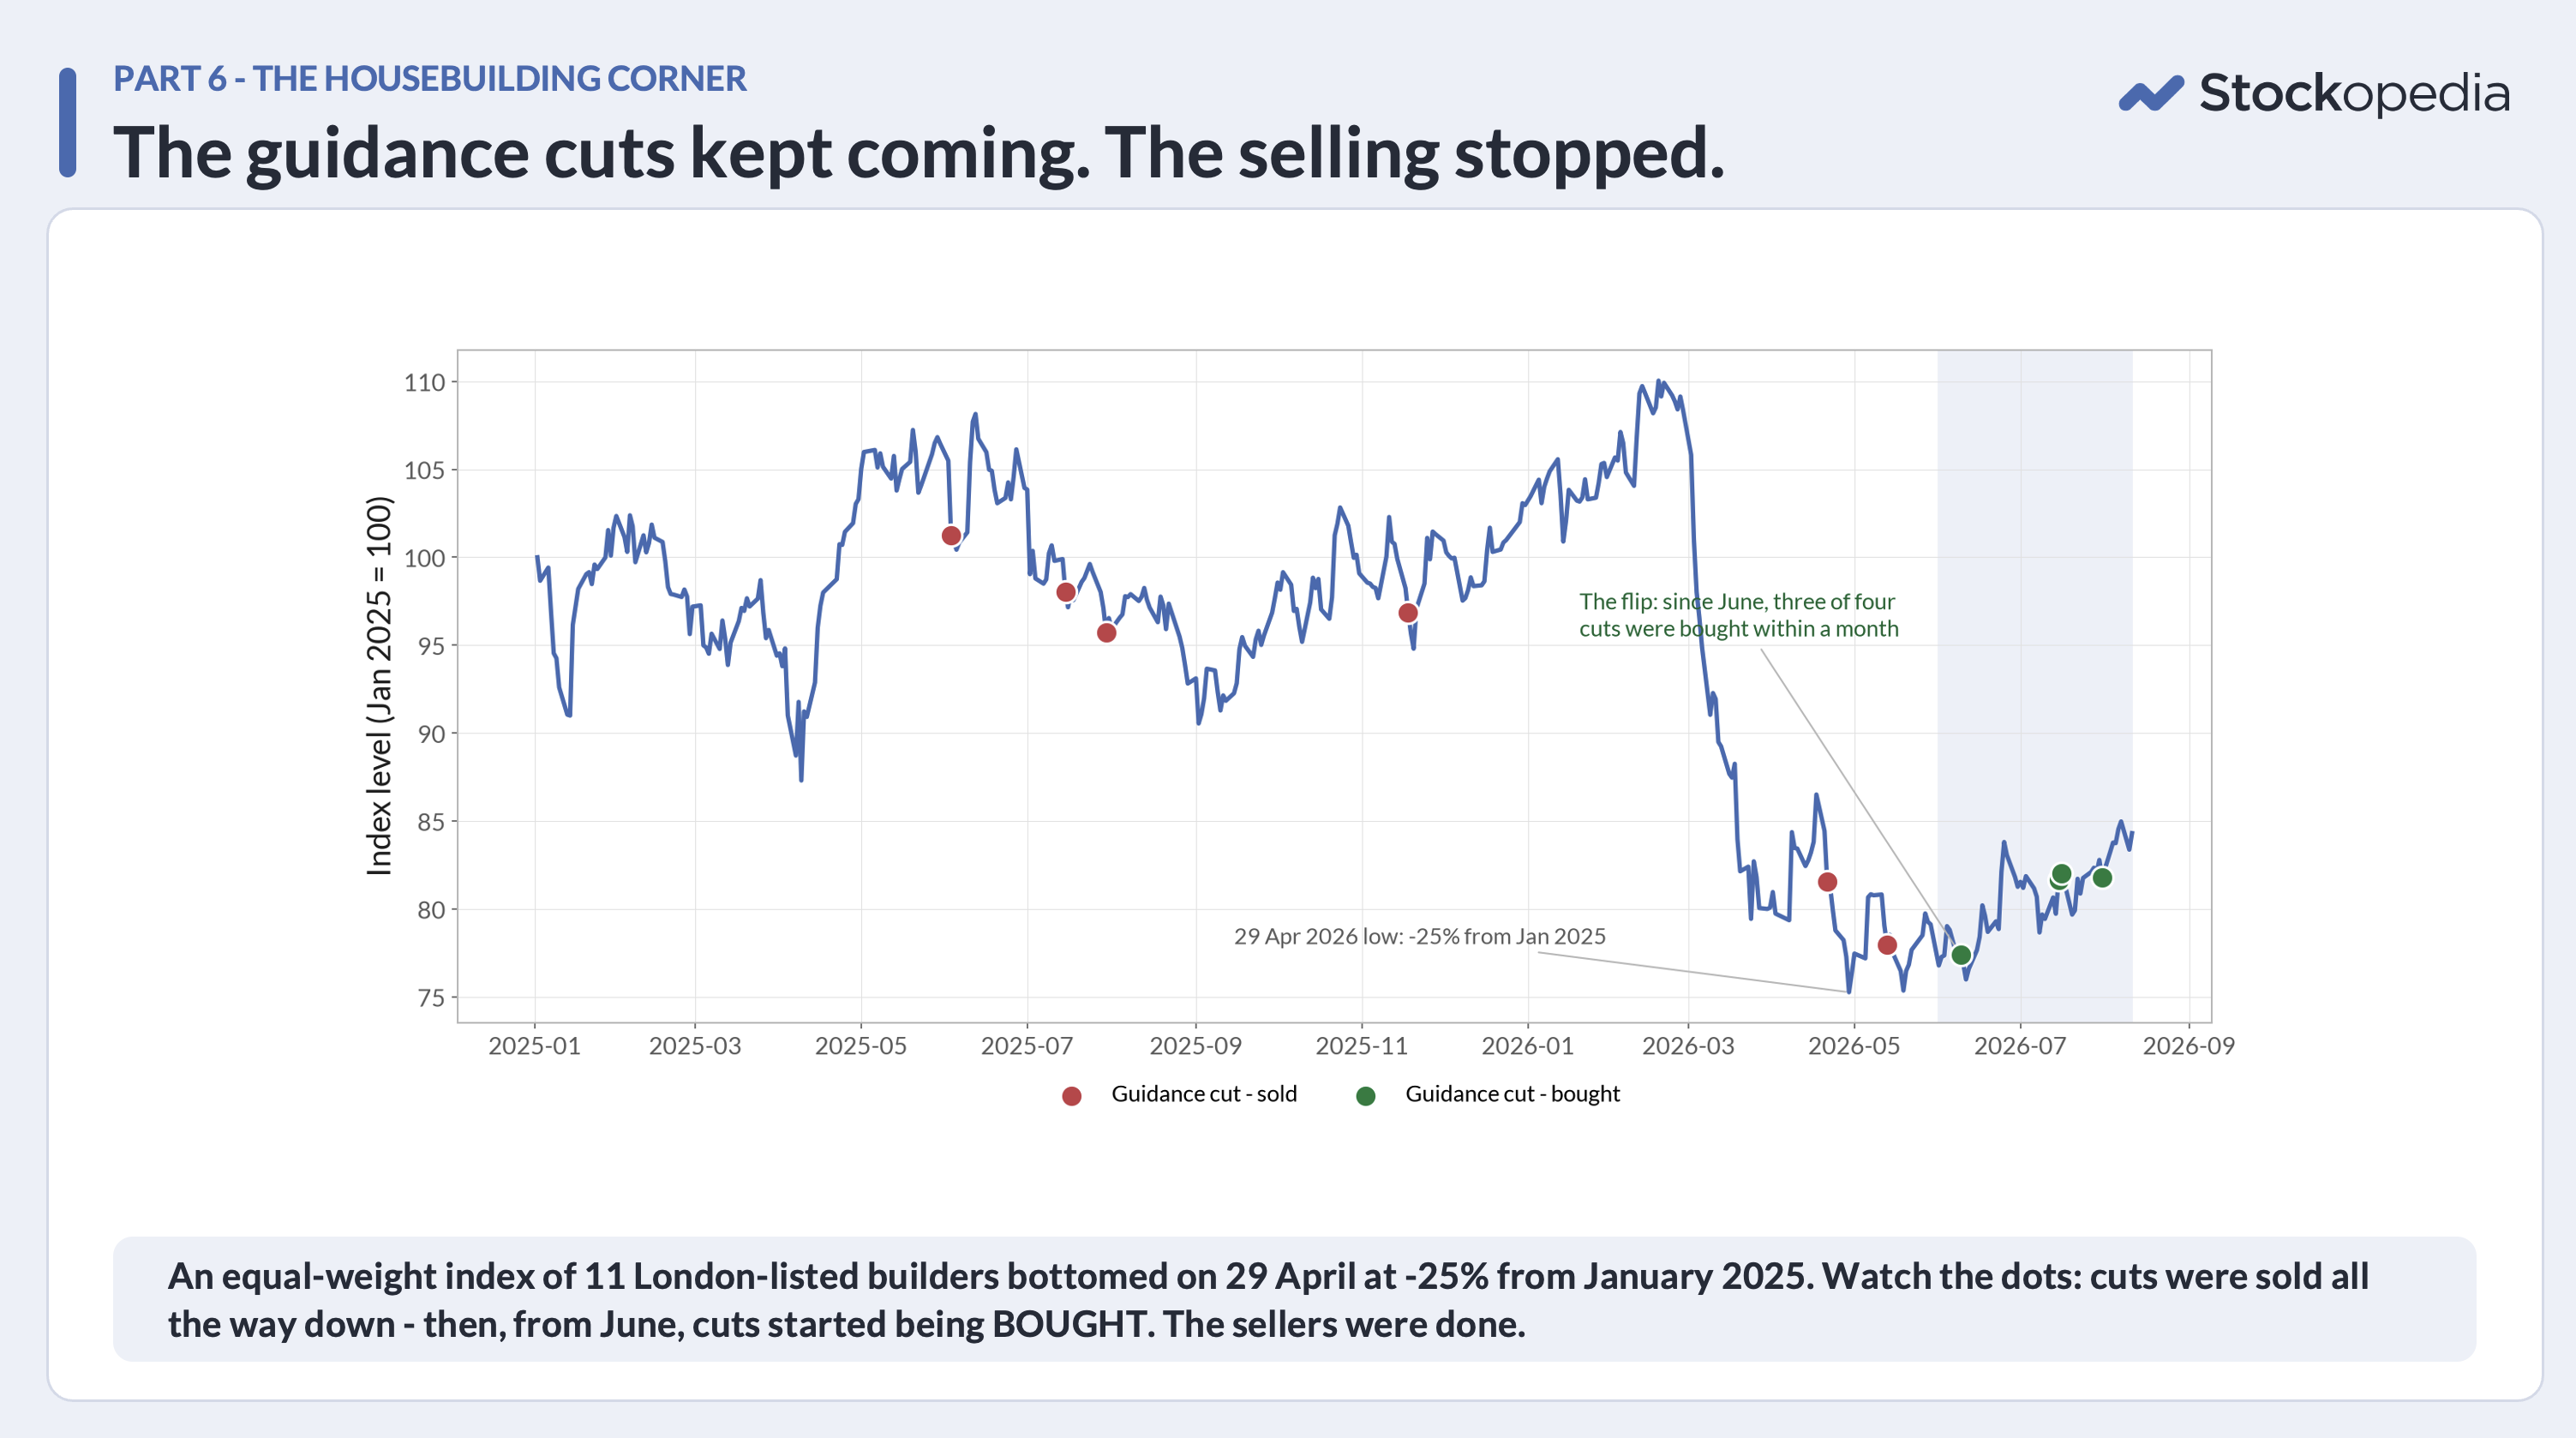
What caught our eye is how the market has started reacting to bad news.
There have been ten guidance cuts since mid-2025. The first six fell 17% on average on the day and kept falling over the following month. But all four cuts since June have traded differently. The share prices were higher four weeks later. Taylor Wimpey (TW.) even rebased its dividend policy on 31st July - normally that would create a share price hammering - but the shares have risen since. When guidance downgrades are ignored by the market, I think it’s a signal that sentiment has changed and the sellers may be done.
Personally I still want to see the language change - "ahead of expectations", upgraded guidance - before I'd move, even if that means being late. The risk is this is a temporary rally.
Roland's Irish comparison shows what can happen if the cycle turns: Cairn Homes (LON:CRN) was at 0.9x book on 7% ROCE in 2020, roughly where the UK majors sit today. It trades at 1.9 times on 16% returns now. If that played out, there are multibaggers to be had. But it’s a big if!
Three rules to take home
You know how I like some simple rules... well just to reiterate the key points in the webinar:
- Follow the words. "Ahead of expectations" and raised earnings guidance keep driving share price drift after the first day jump, especially in shares ranked above 80.
- Winners aren't too expensive. Ramsdens, CMC, Keller - rallying share prices often look like you'd missed the boat. So often you haven’t. If valuations are still low, share price rises don’t mean the shares areexpensive.
- In loathed sectors, watch the reaction, not the news. If bad news stops hurting shares, it’s a signal that sentiment is changing and sellers may be done.
What are your thoughts?
The webinar video has plenty more, including all the data about the takeover bid-wave and a closing list of a dozen companies beating expectations right now with StockRanks of 80 or higher. Watch the recording and download the slides.
I’d love to hear your thoughts on any of the themes discussed.
- Did you own Ramsdens - or what held you back?
- Are you buying the housebuilders, or waiting for further improved sentiment?
- Any views on the growth corner? RGG, SEE, MTEC and KNOS. Or any other growth stock names?
- And which of the 12 "ahead of expectations" names shared at the end are you most interested in?
Thanks for your understanding over the webinar streaming issues. I’m putting it down to being a glitch in the matrix. We’ve been putting on a great pace of webinars this year - more than ever actually - and targeting one per month. Let me know what topics you’d love to see covered more.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
thanks guys for the excellent event and interesting analysis on homebuilders.
Good webinar but please - for the love of God - sort out the audio, Ed. Your microphone distorted so often it made it hard to listen to.
One point I would like to add to the discussion is that the concept of whether a company beats expectations is a bit more complicated than has been discussed. A couple of companies you highlight recently Shoe Zone and Tristel mentioned Trading was positive but they didnt say explicitly earnings were above expectations. Tristel specifically said results are in line with market expectations, Shoe Zone is still making a loss, it mentioned cash & equivalent are improving. Similarly Yu is not clear whether they beat expectations or not and S4 Capital which rose 22% on the day on 5th August and had a stock rank of 91 said operational EPS was in line but adjusted basic EPS was ahead of market expectations. I personally try to make a judgement between 0700 and 0800 by reading the report to see whether I think the company has beaten expectations or not, but I also look at the Daily Market Report table in the morning to confirm whether Graham, Roland, Mark or whoever is covering feel the share has beaten expectations or not. I think its important to have a 2nd opinion, as well as looking at how the market reacts. Luceco said they beat expectations but they fell heavily on the day.
Thoroughly enjoyed watching the recorded session and thanks very much for the helpful insights. I already have an overweight holding in Ramsdens, thanks to Naps and realising some gold miner gains for this stock, but without the webinair I would have once again failed to act on the evidence of continual signals mentioned by Ed regarding improved performance and profit and missed completely the opportunities presented by recent news on MTEC, TPX, KNOS and FOUR. After watching the session I swapped my holdings in LUCE and half of those in YU which have come to a standstill lately and invested in all of the previously mentioned, deciding like others that it was still too early for builders, without a "help to buy" plan and RGG which looks to me as though it might soon run into bad debt problems, unless I am misunderstanding what they are providing to landlords in the event of non-payment of rents.
I can provide some more colour to your concern over bad debts at RGG Saltash Bob as it’s a company I’ve spent a fair bit of time looking at (& I hold the shares)
From my understanding, they have just a 4% bad debt rate at the moment as they are selective in who they chose to insure/ have a rigorous selection process. Of these the majority then enter negotiation to be settled. Only 1% actually go to court.
I suspect as the total market is growing rapidly they’ll be able to be even more selective going forward so this rate may decrease. I hope this helps allay your concerns, AG
This was really insightful and has added some conviction to a few of my recent ideas.
Many thanks to both of you.
Looking forward to the next one!
Thank you for this. One thing, the sound quality wasn’t great and for those of us with less than perfect hearing it was difficult to hear everything
A great video, really good approach, thanks to the team for all their effort much appreciated
Thank you for the recording- I’m amused to see the 2 small Growth stocks you talked about as I hold both!
Rentguarantor Holdings (LON:RGG) has been a major contributor to my gains this year since buying back at 38p in July. I believe it has further to go as it’s a business in the right place at the right time. I’d see the entrance of a larger company like L & G into the area as a positive as it will increase knowledge of the product
Seeing Machines (LON:SEE) is moving into human-robotic automation development software which is higher margin & has recently announced a new contract with a ‘global industrial technology’ company. I believe this to be with their largest shareholder & thus increases the likelihood of them bidding for them, let’s see
PS Am kicking myself for not holding KNOS & MTEC though ;-)
Hi Ed. Thanks for your efforts. Re builders; it’s too early for me. If this Is the first stage of a full recovery then there will be a retest of the bottom at some point. Only then will we know for sure if a bottom is in.
Yield on gilts are set to stay at elevated levels and may go higher IMO. Any attempts by government to artificially bring yields down will probably result in currency devaluation and then higher inflation, which is worse. So the days of cheap loans and mortgages may be over for quite some time. We need to get used to rates at this level IMO (pre GFC levels). This makes land and houses less affordable and there will have to be an adjustment at some point (including revaluing the land banks). Until then I can’t see the market getting back to normal.
If I’m wrong then I’m happy to watch this one go or at least wait until it’s clear that a recovery is underway.
Thanks Ed & Roland. I've followed your research on ahead of expectations announcements for a while, and have finally taken the plunge and created a Trading 212 pie made up of stocks that have had those kind of announcements recently. Will be interesting to see how it goes...
Hardide (LON:HDD) is a great example of a share giving repeated above expectations trading updates - it's had an incredible YTD performance!
Ed - I will try and carve out the time to watch the session but would offer the following on Kainos (LON:KNOS) which this week became my #3 position. My history with this one is pretty much down to following the Stockopedia data to great effect. I picked it up as an interest on 24th June after seeing the StockRank jump from 56 to 70. Analysis showed Panmure had upgraded it to Buy on 23rd June and since the results on 18th May, and Roland's report, the price had drifted down and in my view this one was suffering "SaaSpocalypse" fear creating a fundamental mispricing. The price previously got trashed over margin compression, but your algorithms had begin to recalc all this as brokers lifted EPS by 15% to 42.7p - so all considered I took a decent chunk at 778.25p on 24th June. My original intent was to add if there was a summer lull, but by early Aug there was a clear breakout and Momentum rank lifted further to 65. Also by then the 50dMA was closing in on the 200dMA and analyst targets were ~20% above current price. Taking a cut of all the stock data then suggested not only that the thesis was strong, but also that there must be institutional volume buying taking place, therefore I added strongly at 918.11p to bring me an average of 841p. I have moved increasingly into a rigorous process of screening, tracking moves and trying to catch "coiled springs" through the data here, combined with some AI assistance for analysis and some old-school "gut feel" - the results on Kainos (LON:KNOS) came good this week, and add to a similar success with Costain (LON:COST) last week. Whether there is significantly more to come on these is (for me anyway) a tight watching brief on rank moves and changes in outlook as the algorithms catch up on latest broker views.
Nice bike if its yours
A really varied and thought provoking session. Thx both.
Watched it this morning. Brilliant as always. thank you both.