What happened to the top ten multibaggers of the last decade?

Multibaggers. These are the stocks we all dream of owning. A single multibagger can make up for a whole portfolio’s worth of mistakes, and without one, beating the market becomes much harder.
Back in 2023, on the ten-year anniversary of the StockRanks, we posed a simple but fascinating question:
What lessons could we learn from the top ten multibaggers of the last decade?
It led to one of the most satisfying deep research projects we’ve done here at Stockopedia, and a cascade of analysis and insight, bundled into our Multibagger Masterclasses.
We limited the search to British stocks - and they really were a British bunch.
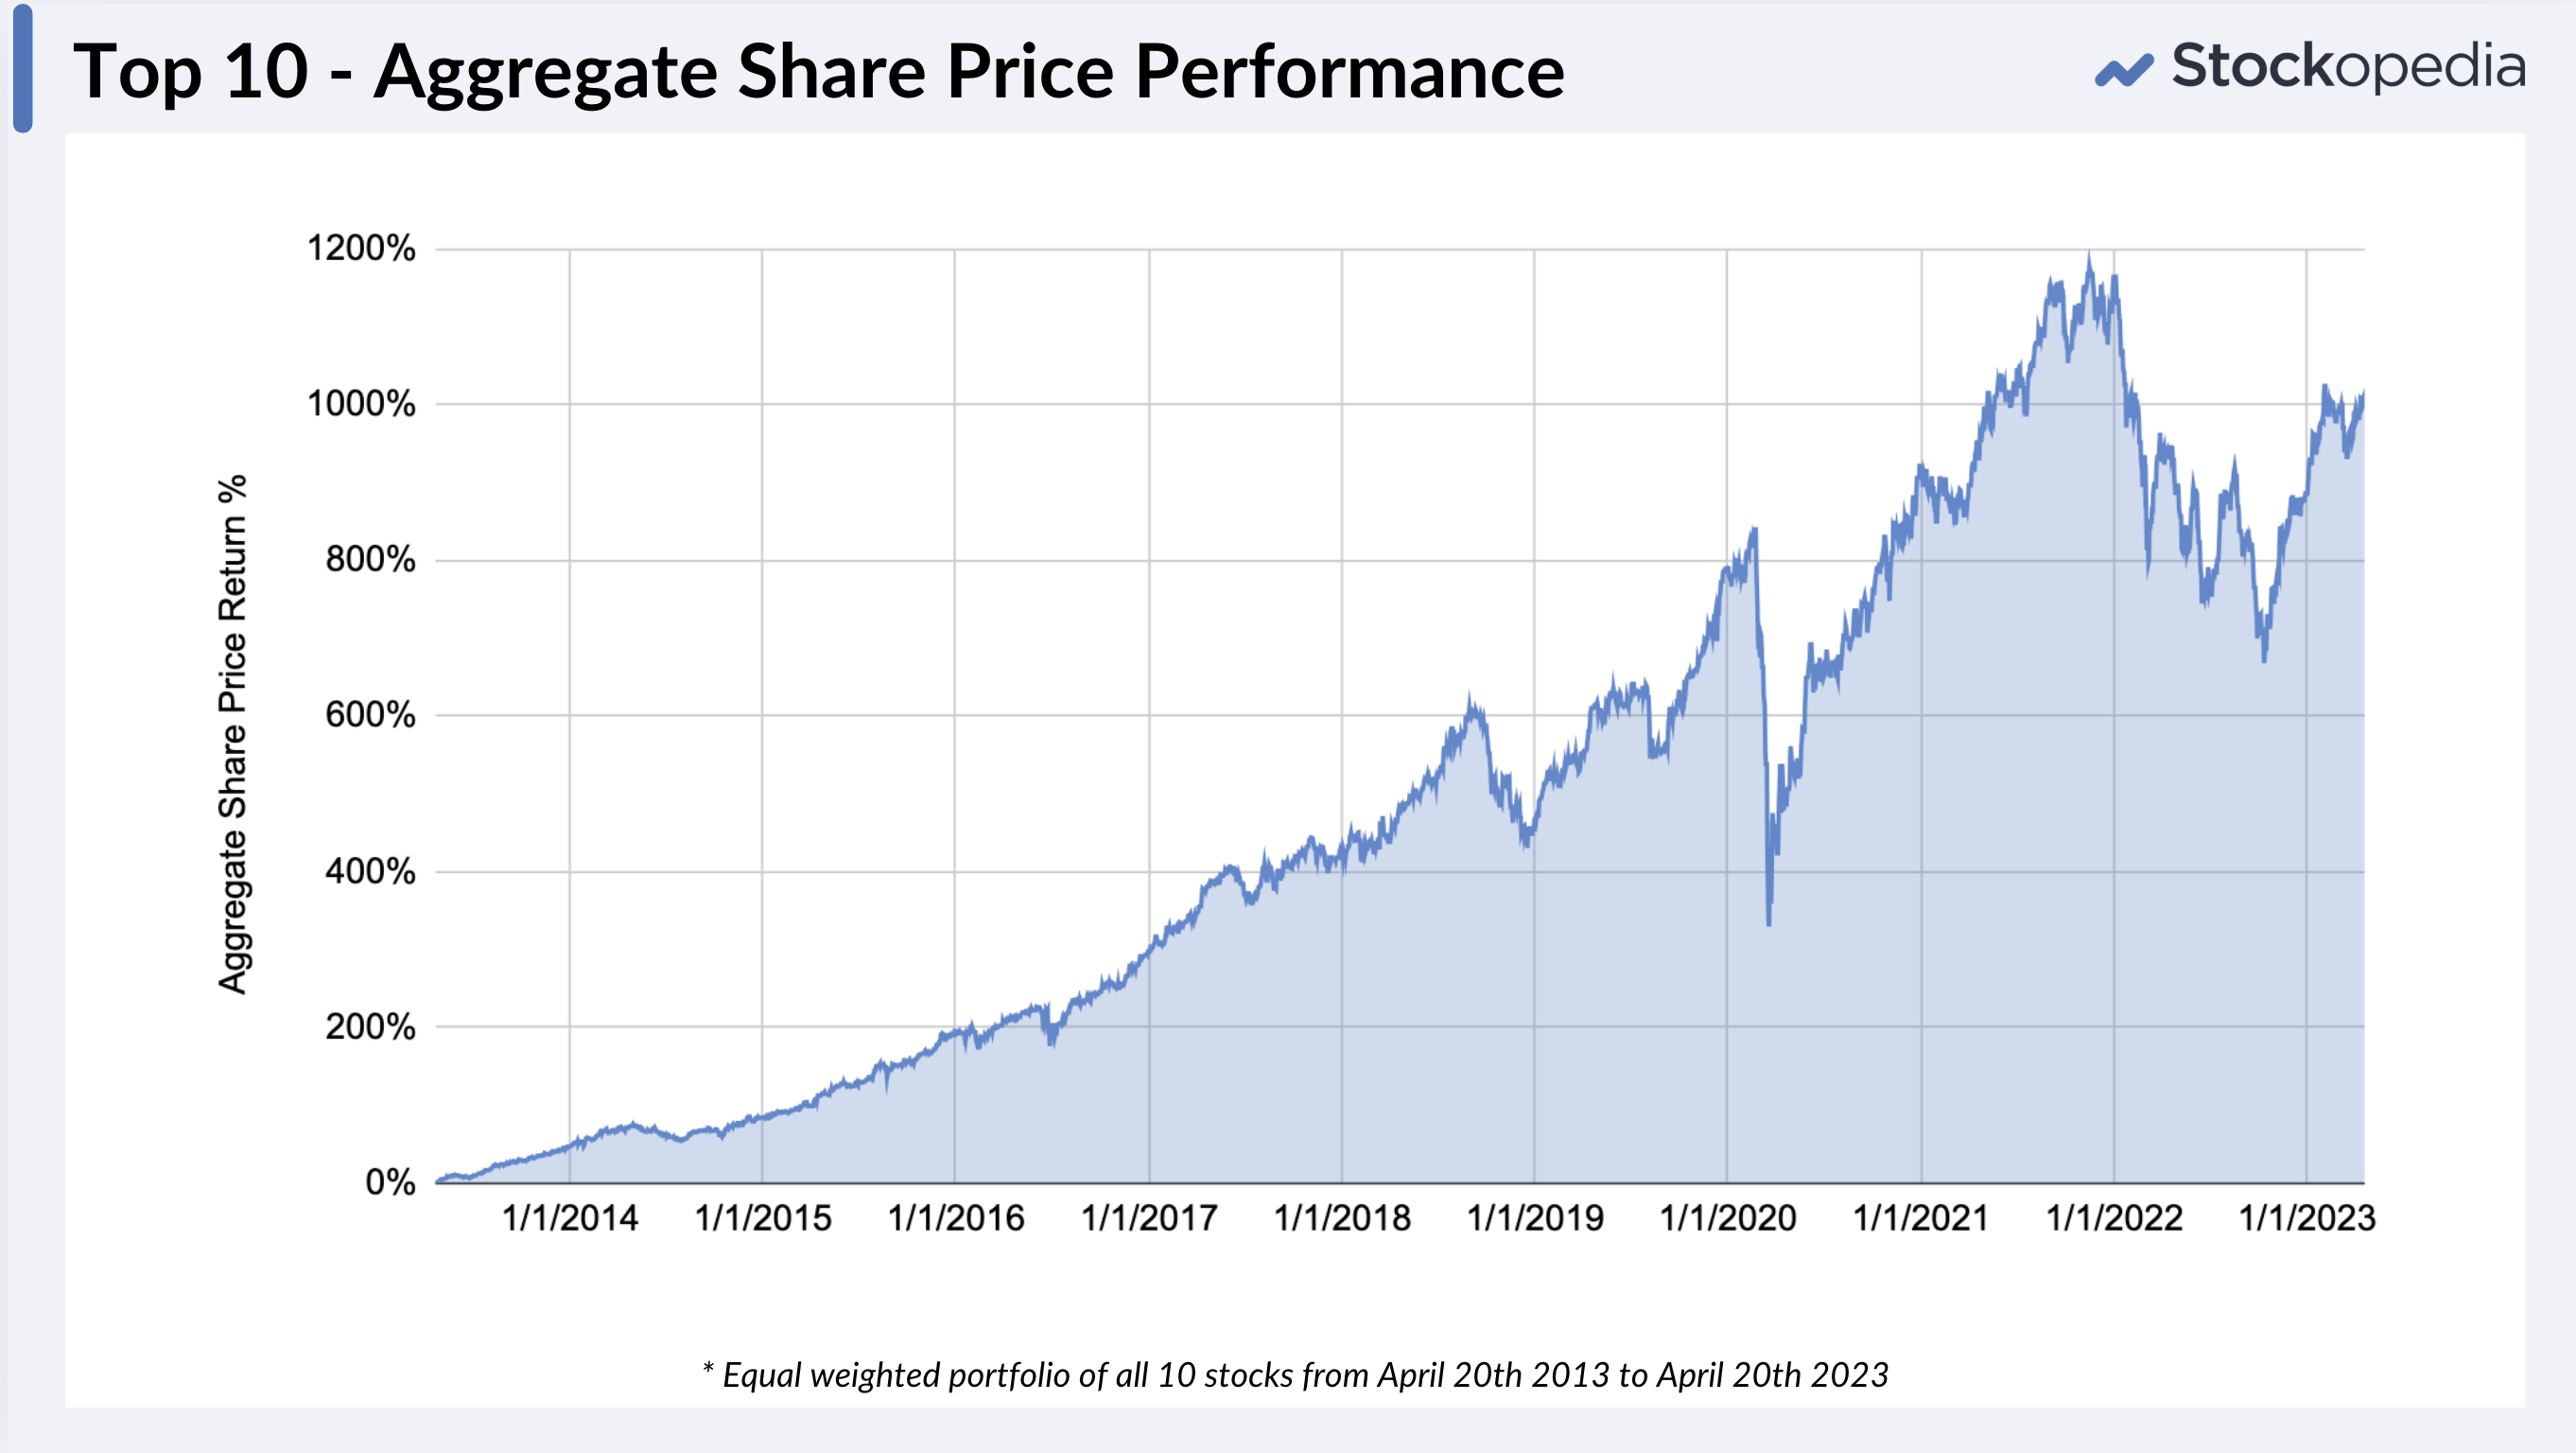
Rather reserved in their performance (no hundred baggers like we see in America) and not a single technology stock amongst them. But they still managed an average 1000% performance between them over a ten year period.
But what’s happened since?
A couple of years on, I began to wonder what’s happened since?
I’d noticed that one or two had stumbled, but only when I ran the numbers did I realise just how poorly the group has fared since the study end in April 2023.
The average performance since has been -8.4%. This compares very unfavourably with a FTSE All Share that’s risen 14% in the same timeframe.
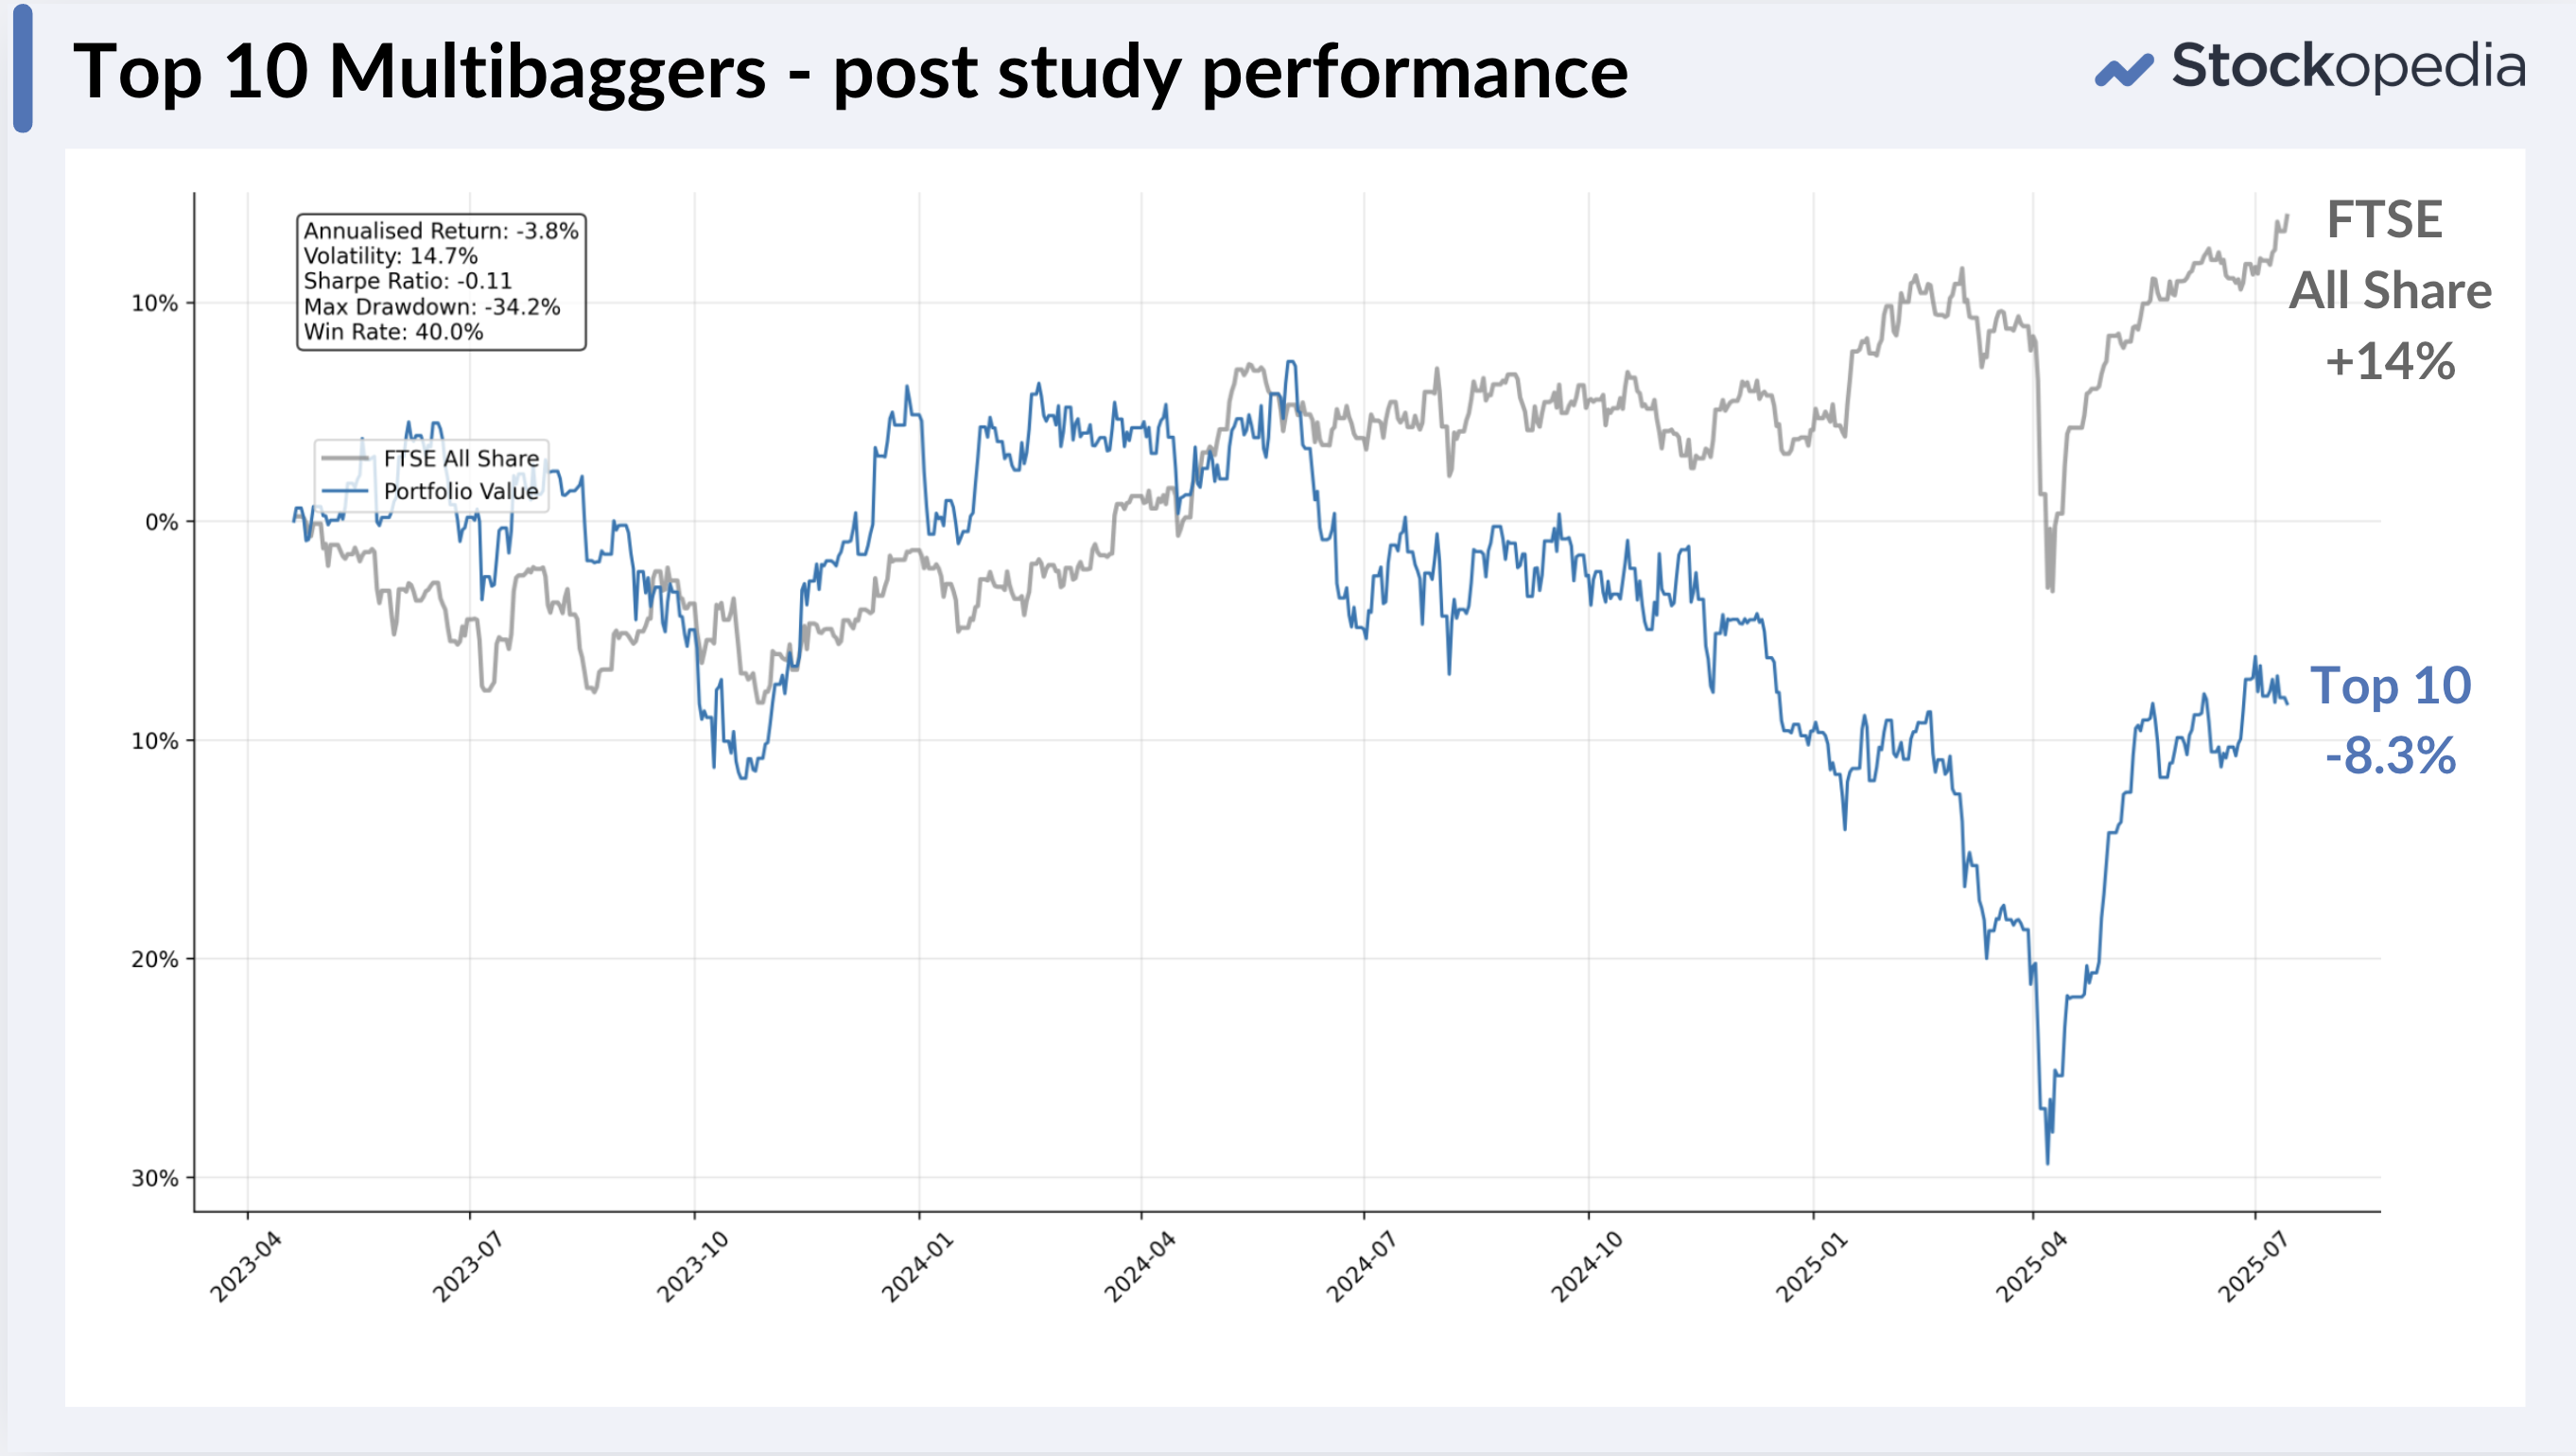
To catch up with the market, they’d need to rally 20% from here.
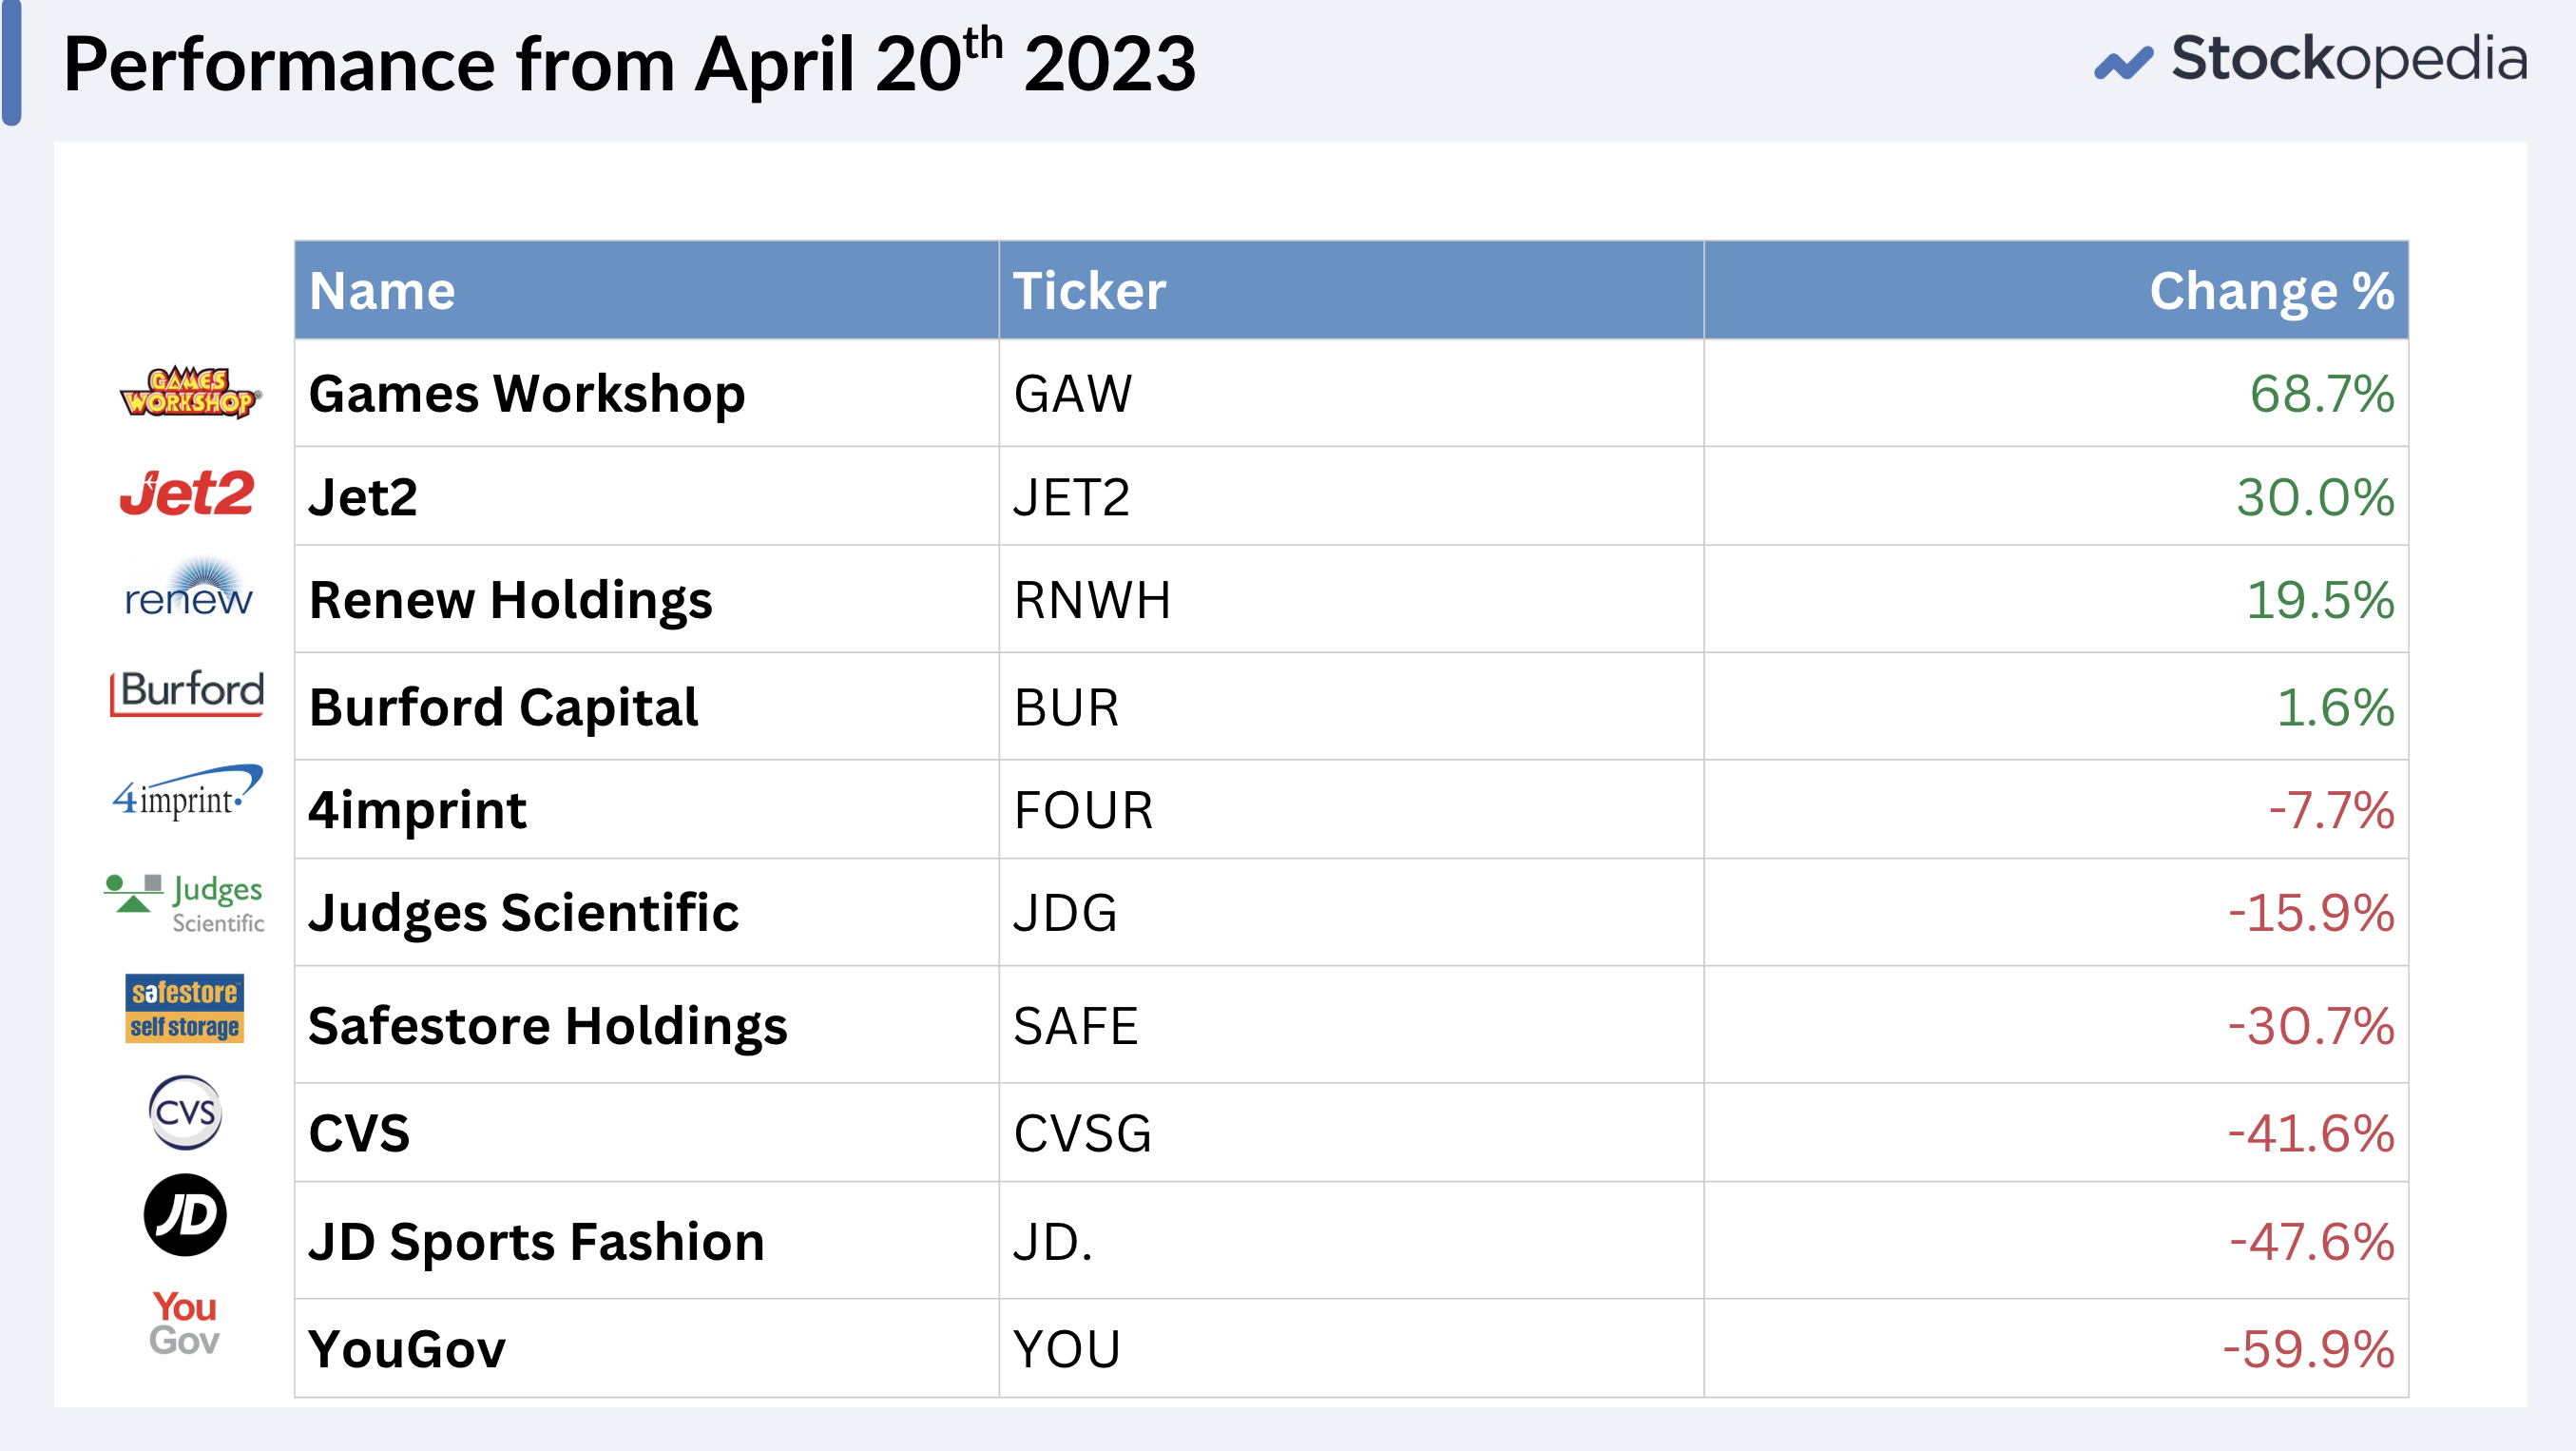
Six of the ten have been losers. Only four have risen. Games Workshop (LON:GAW) continues to perform brilliantly, but YouGov (LON:YOU) , JD Sports Fashion (LON:JD.) and CVS (LON:CVSG) have seriously disappointed.
Mean reversion is very real, and very ruthless.
Why the reversal?
It’s worth going back to what made these stocks multibag in the first place.
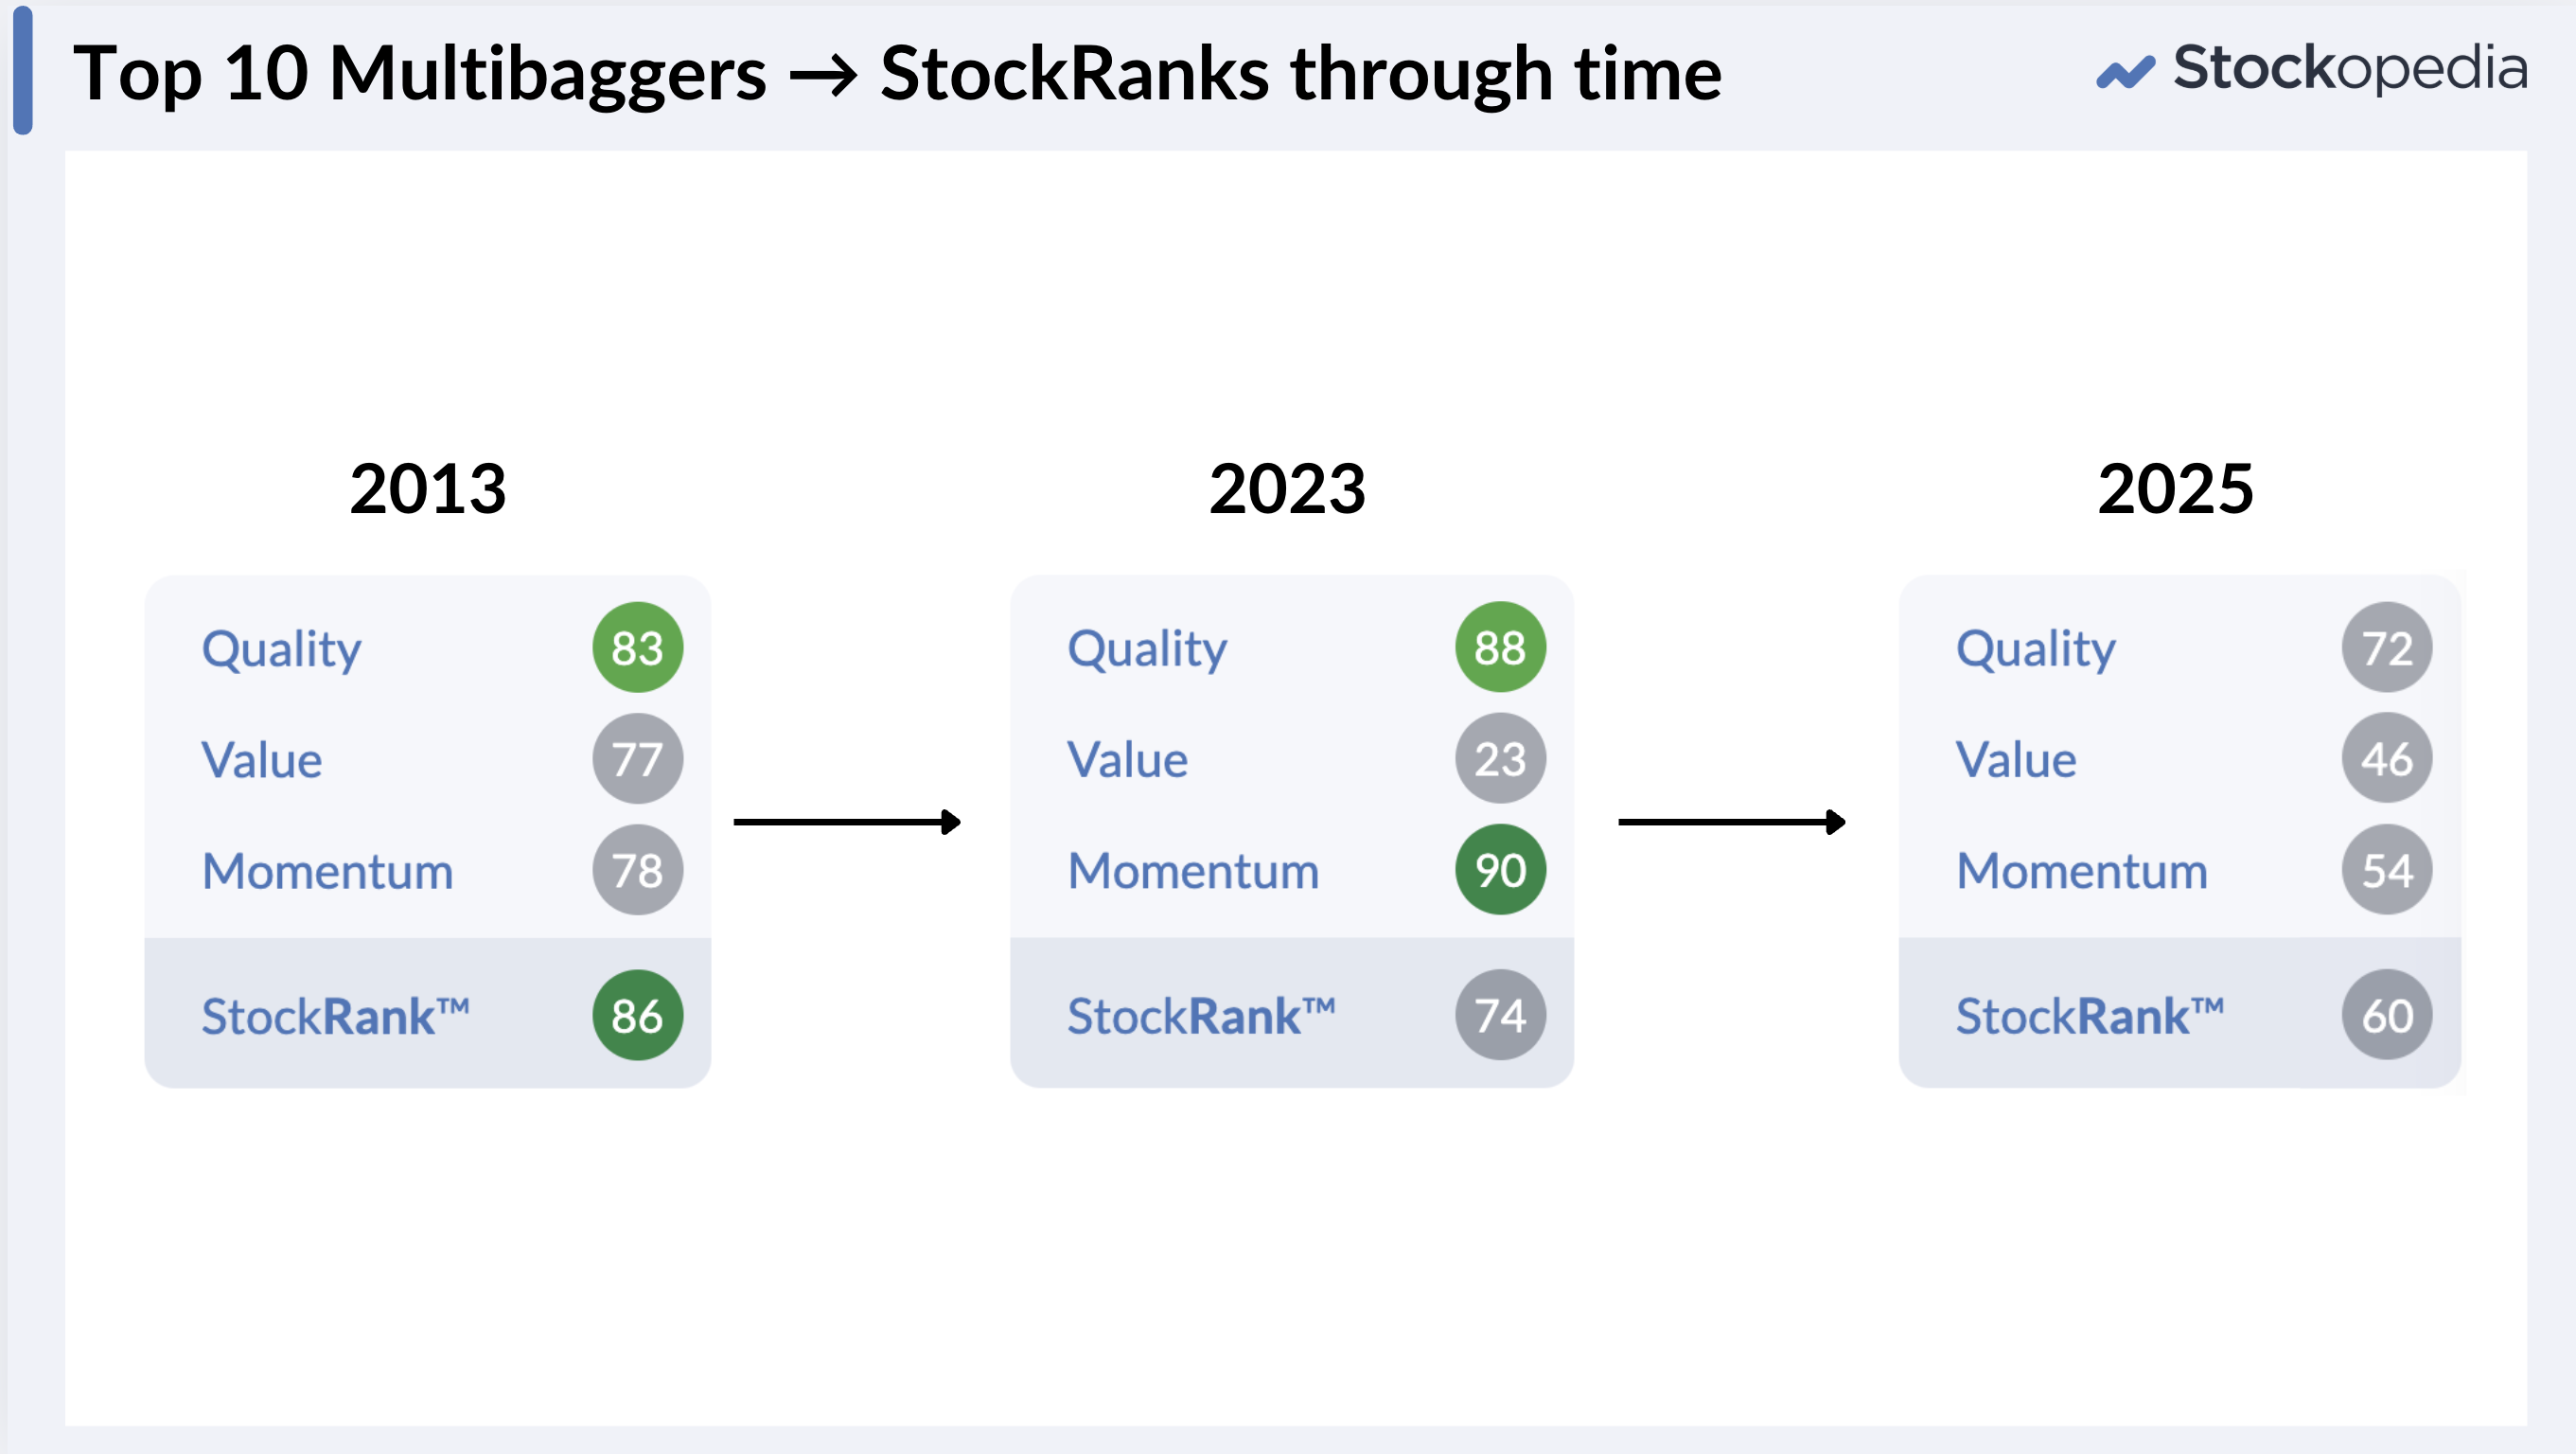
At the start of their journeys, these shares had an average ValueRank of 77 - in other words, they were inexpensive.
As their sales grew, and profits and margins expanded, their QualityRanks rose, and the market re-rated them.
But by 2023, the average ValueRank had dropped to just 23. In short - they got expensive.
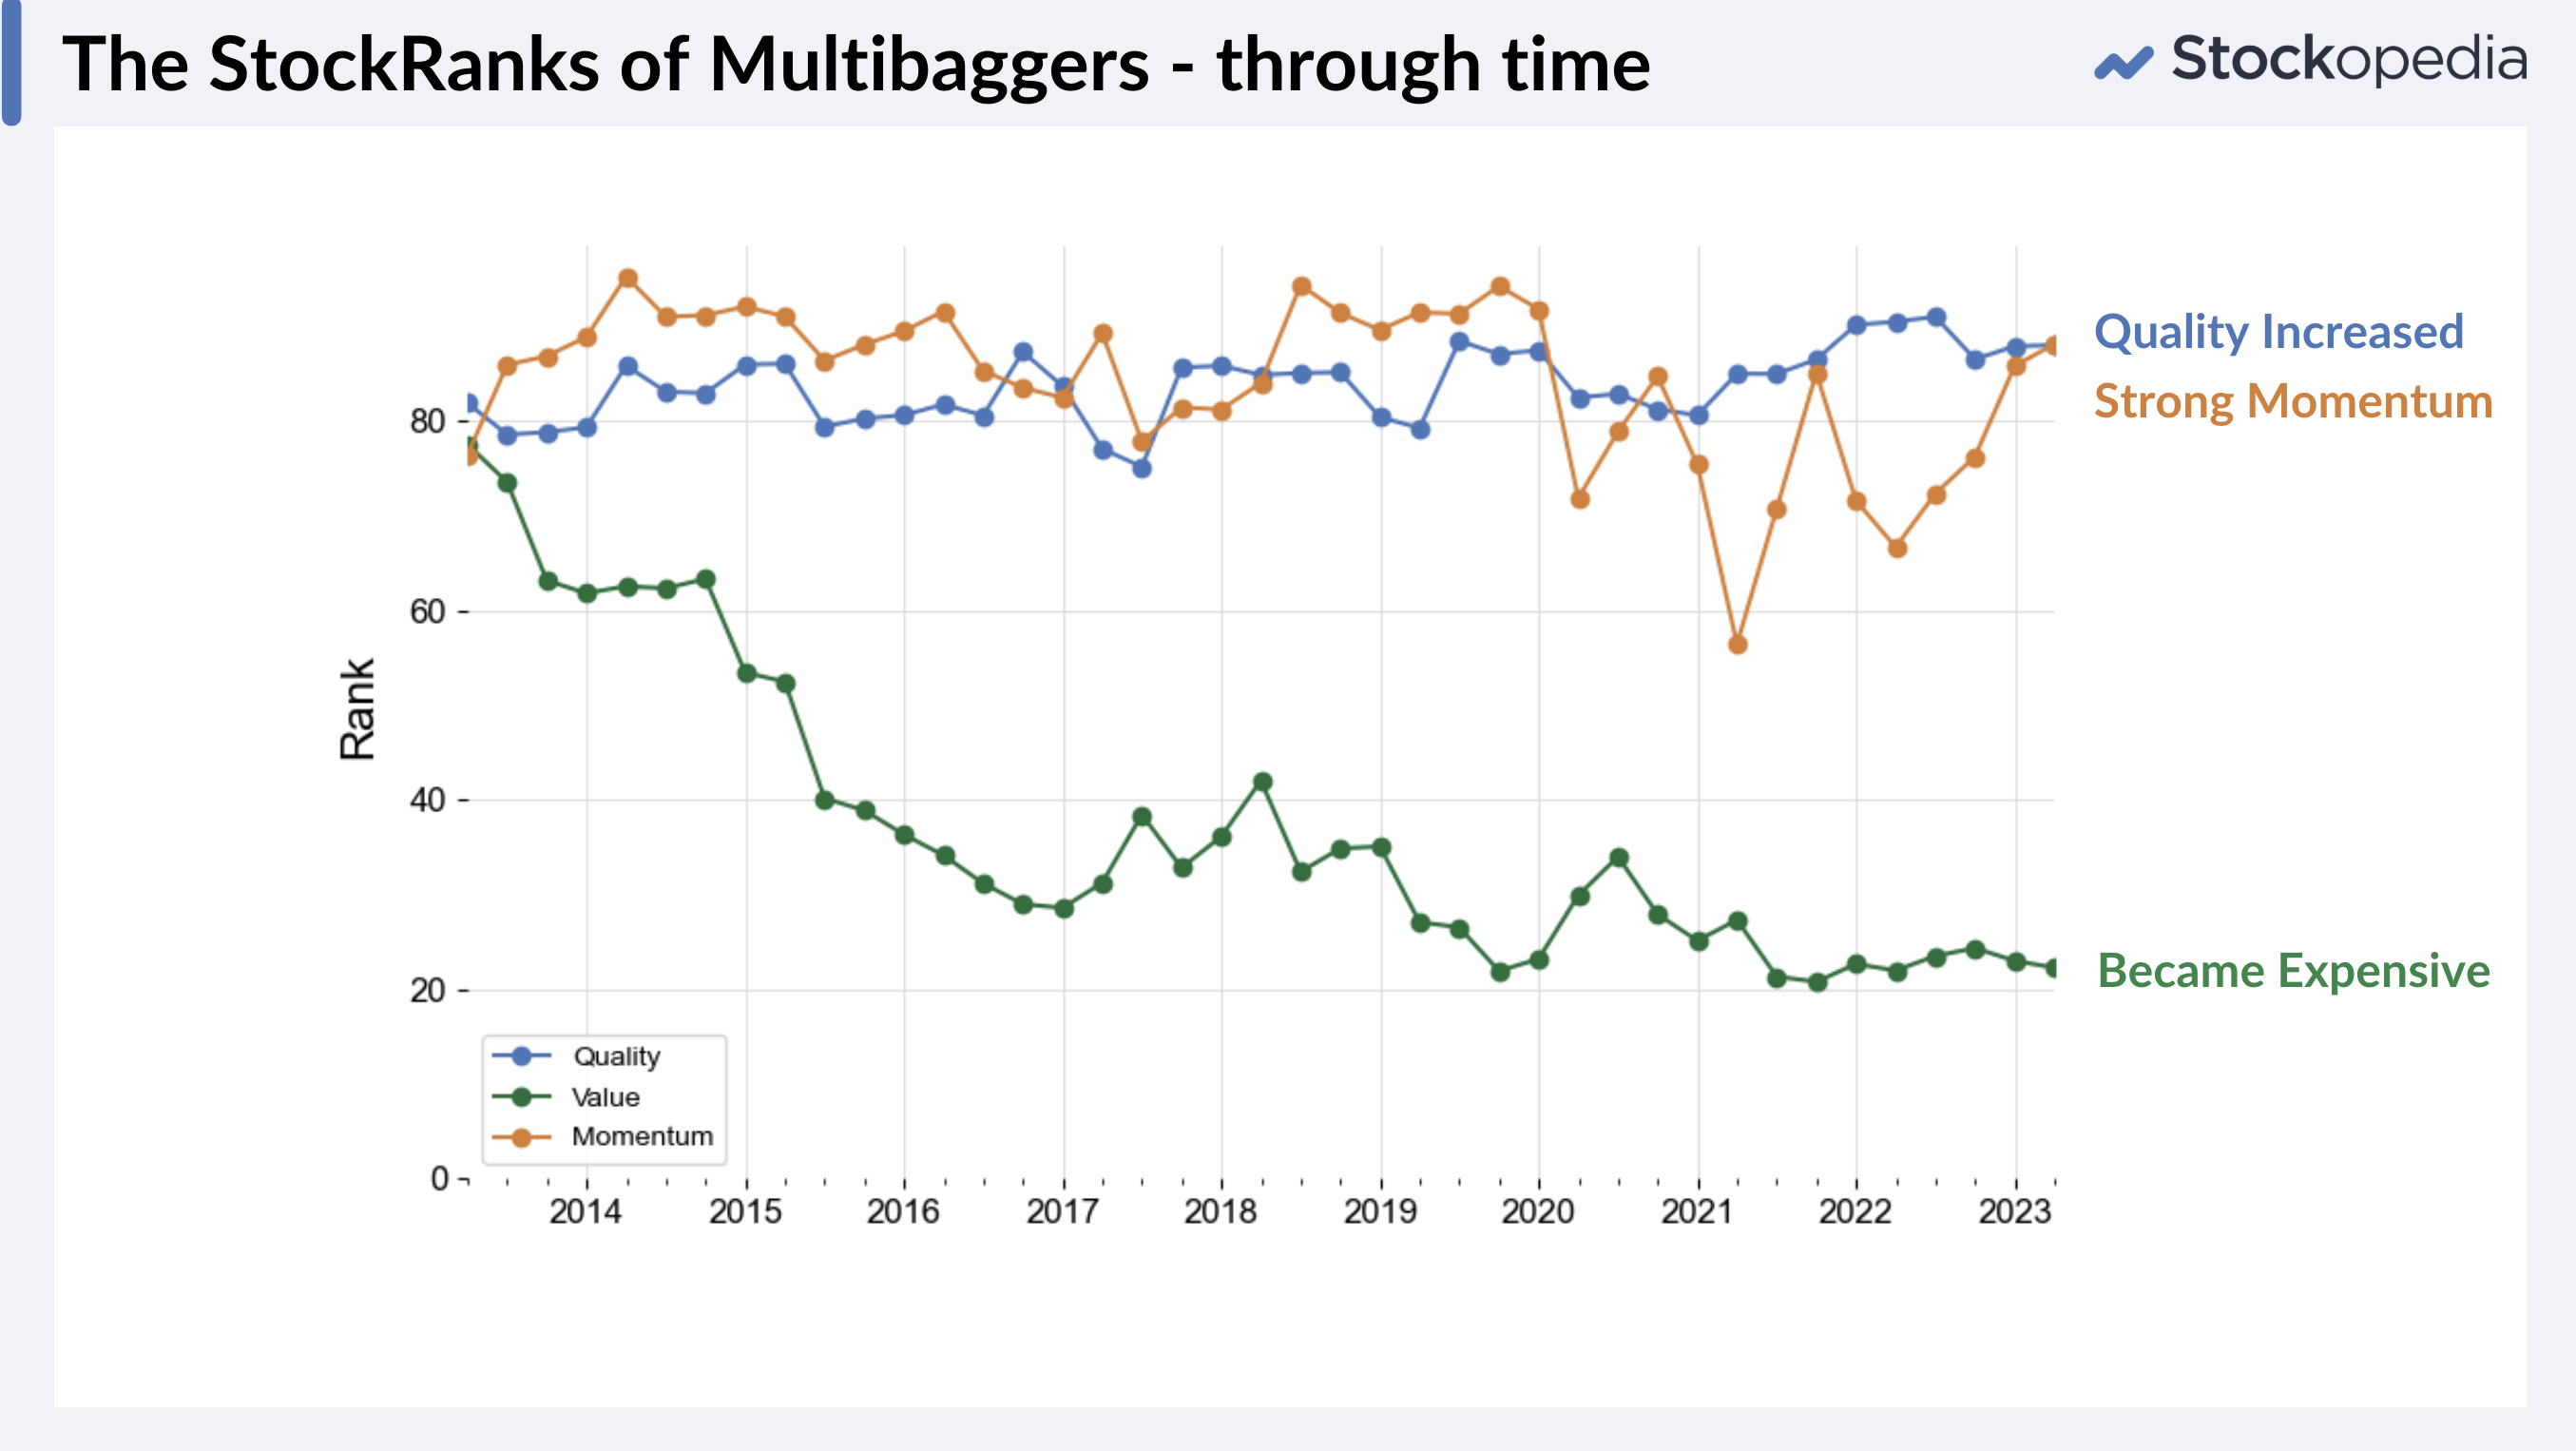
Since then, there has been a further slide in the numbers. Profitability has weakened across the ten. Earnings momentum has suffered, and valuations have come back to earth.
As of 2025, the average Quality Rank is down to 72, and StockRanks have fallen to just 60.
At those levels, these are not the kind of numbers that would make it into my portfolios.
I’ve long had a StockRank 90/70 rule of thumb, which suggests buying near 90 and selling below 70.
Looking at these names, that discipline would have served any multibagger investors well.
What’s the core lesson here?
We all dream of buying and holding forever. We are sort of brainwashed by Warren Buffett’s success into thinking this is what we should all be doing.
And yes - you can’t multibag without holding through years of growth and rerating.
But if you are investing in small and mid caps with the dream of them becoming large caps you can just never become complacent.
Expensive shares, on average, tend to mean revert.
A few months back I wrote about the biggest multibaggers in the NAPS portfolios. Many of them soared in a single year - then dropped just as quickly after selling. Of those I sold, four went on to be huge losers, and four went sideways - only two continued gaining.
When shares get expensive, you really do have to become highly vigilant.
If you want to catch multibaggers and keep the gains, you need to work with the Multibagger Equation. One of the three key drivers is a P/E ratio that can grow.
In other words, it’s easier to multibag if your shares start moderately valued.
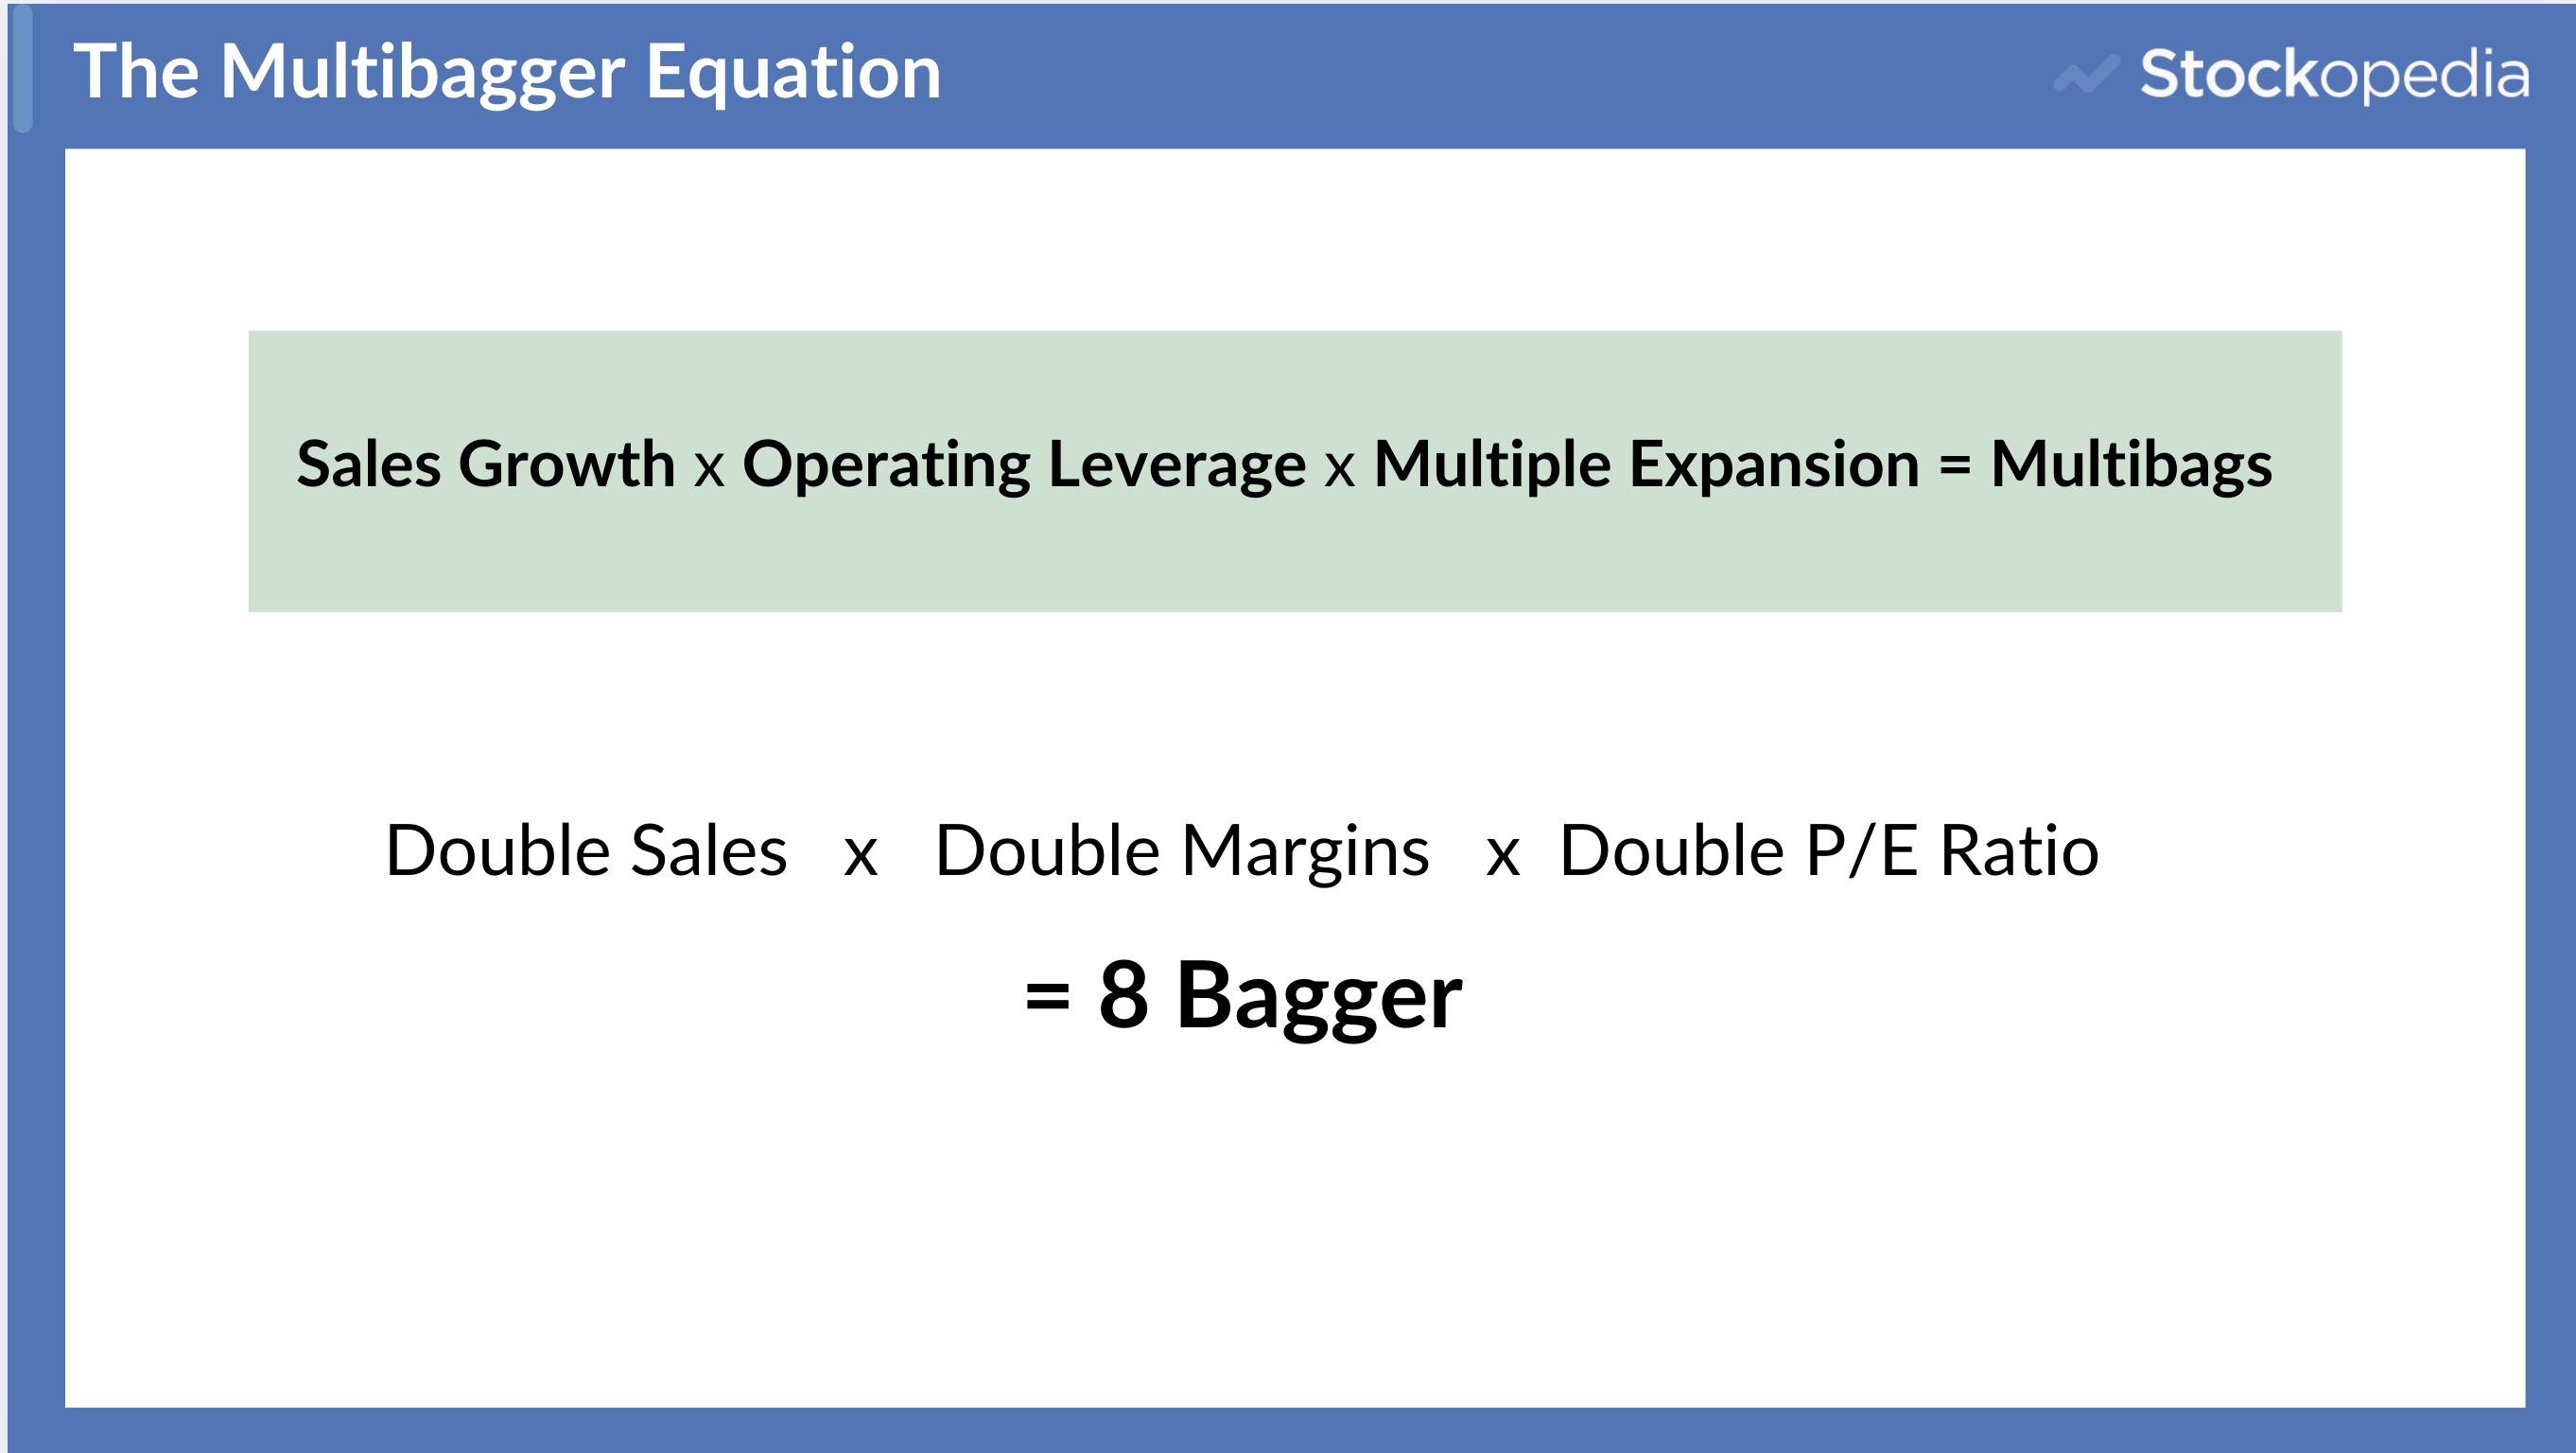
But here’s the catch: If a stock is expensive, it has to keep growing sales and maintain high margins to justify its price - and the runway for further P/E growth becomes limited. Any stumble, bad news or earnings reversal can be treated rather brutally.
It’s important to learn a great lesson from Jim Slater, who was a ruthless seller - “you want to be first in the line of disappointed enthusiasts”.
Remind yourself…
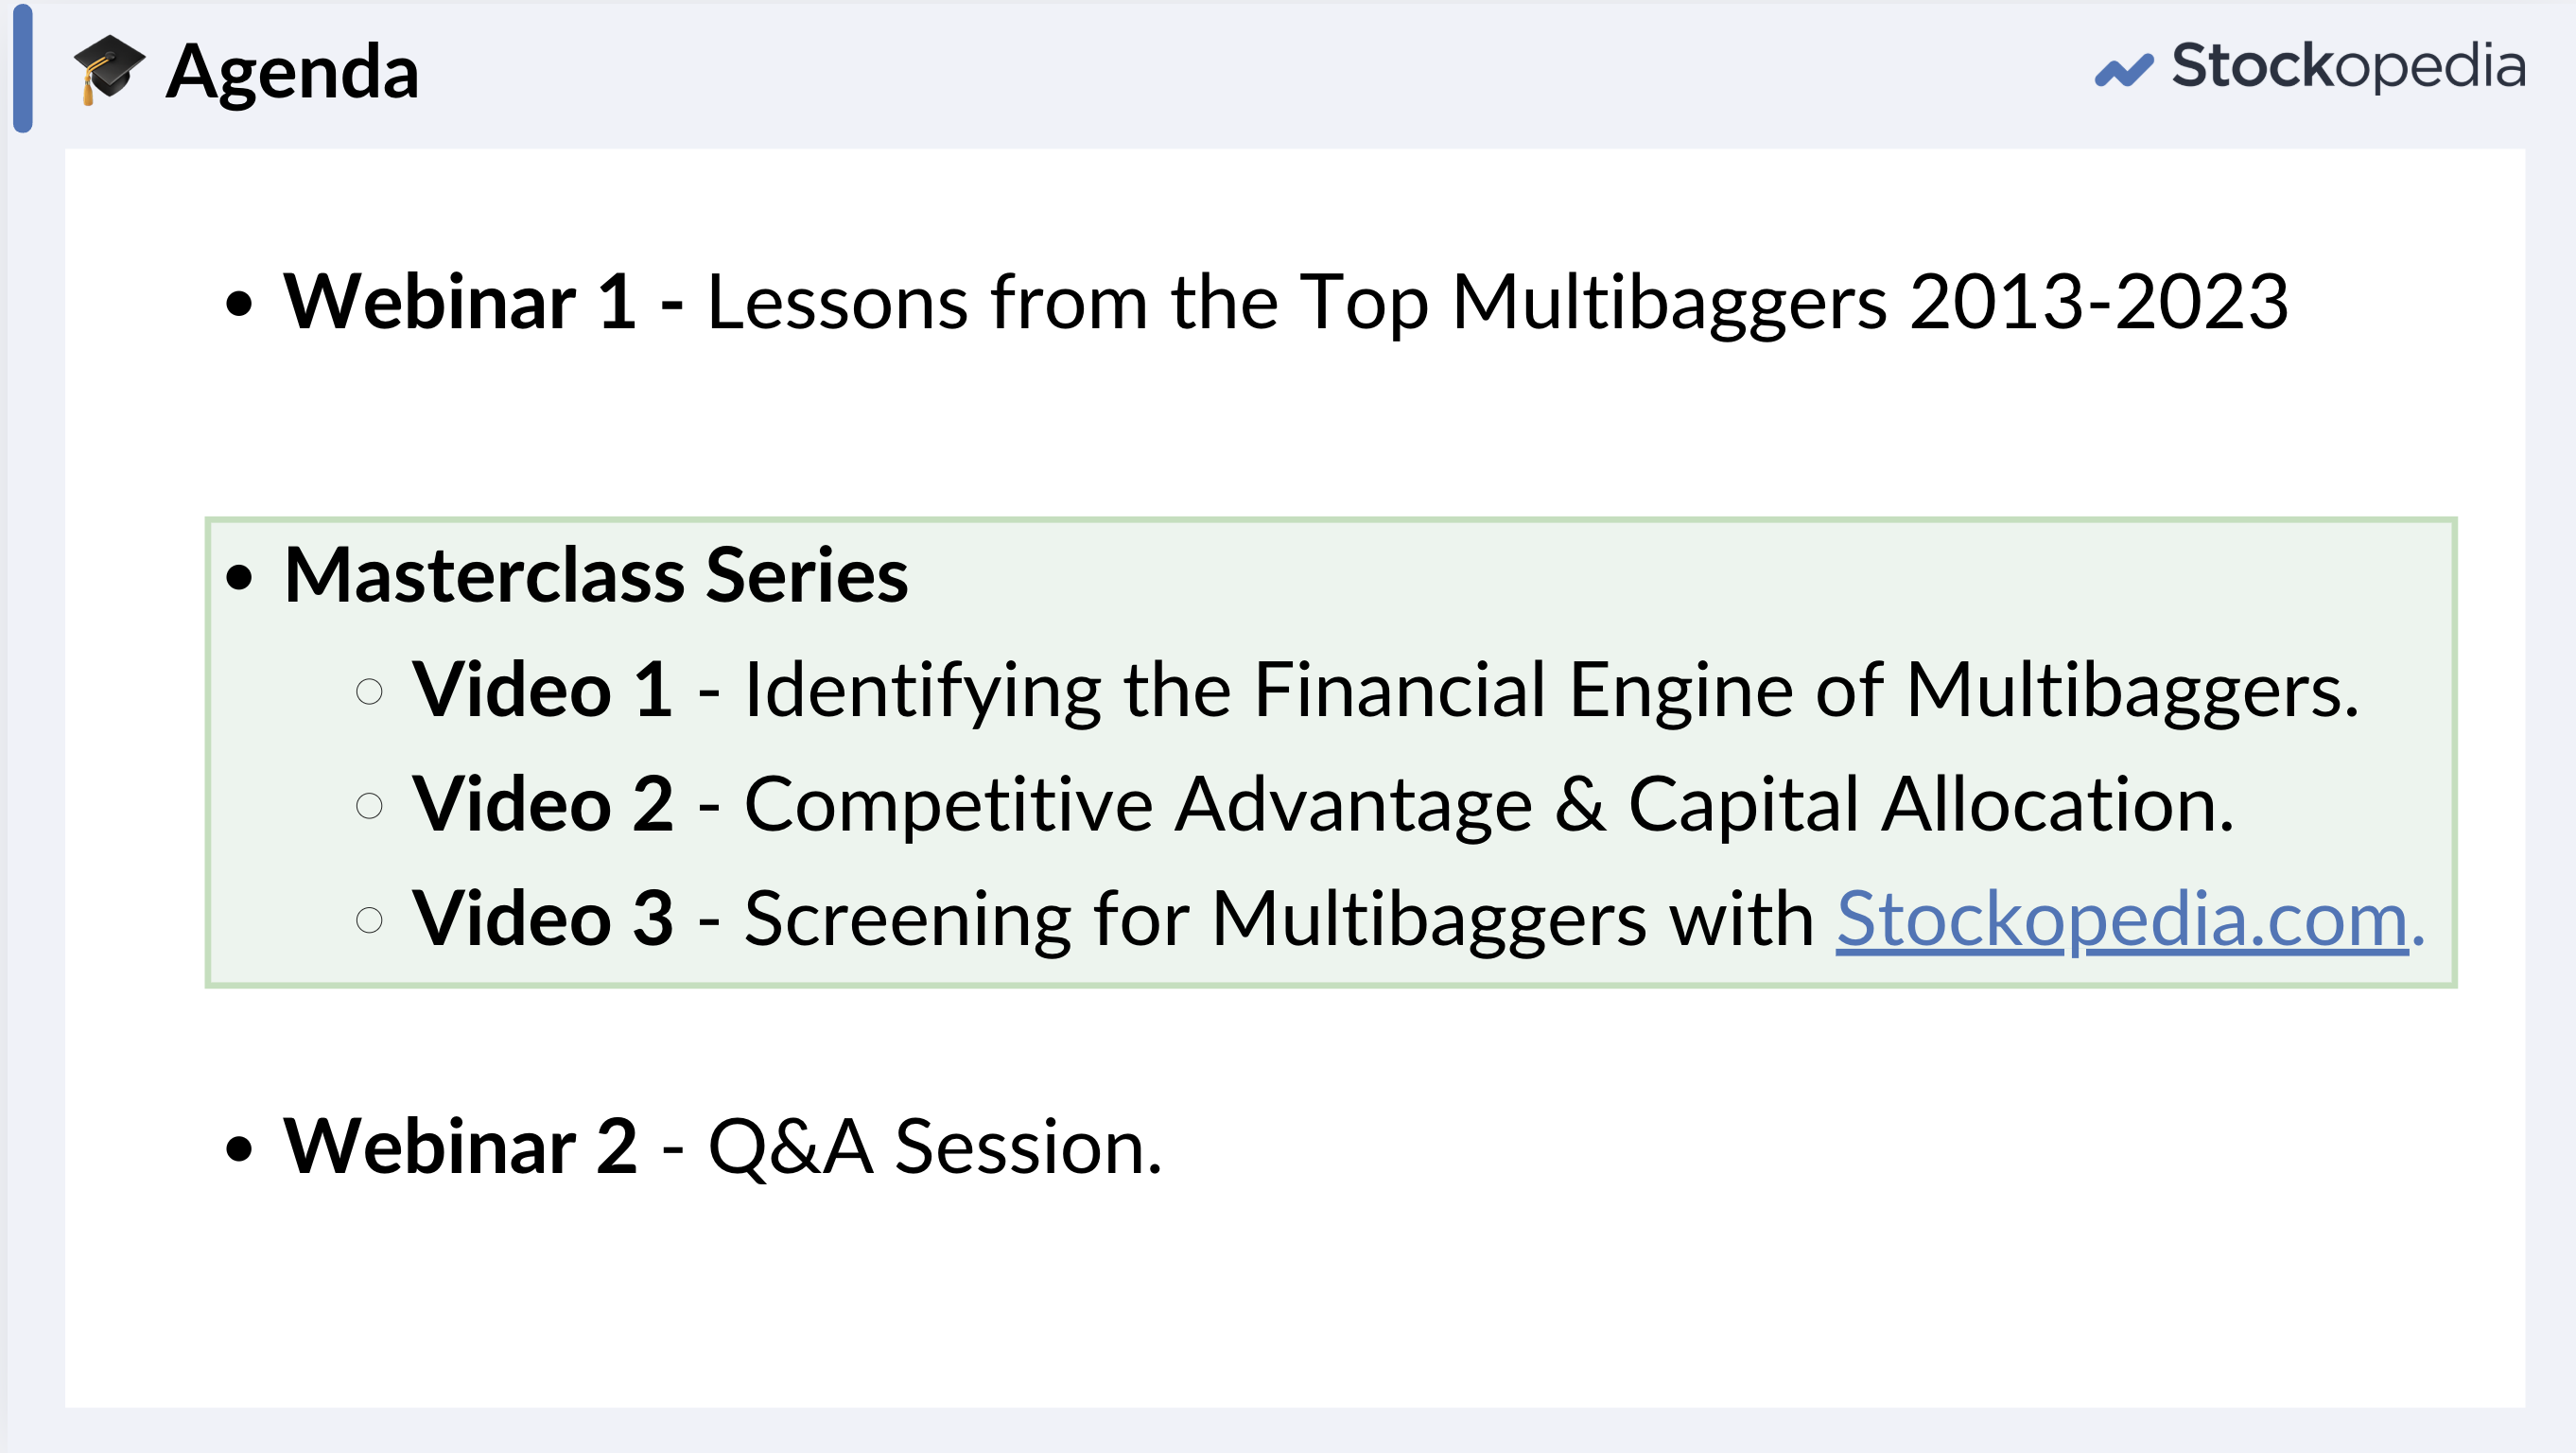
The lessons of the Top 10 Multibaggers are pretty timeless, and I do recommend that you review the material if you haven’t already. You can find all the video material here and an outline of the masterclasses below. We need one more on selling!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
A quick note here - the 2013-1012 top ten have continued to underperform in the post-study period.
This results season has seen a few profit warnings in those stocks - in Judges Scientific (LON:JDG) and Jet2 (LON:JET2) notably.
Beware over-attachment to past winners - especially if they get expensive.
The only reason someone else buys a stock is they think there is more upside in it. This by nature unless you time it perfectly ( and only God and liars do that) you have to leave some upside on the table when you take profits. Greed is good, it’s when you get greedy thinks go wrong!
I've always found that top slicing works well...yes you do lose some of the big gains, but you still get some..
my biggest multibagger is Jet2 from the days when it was DTG , bought at 30p, still have about 8% of my original holding, having sold some at various points
I’ve long had a StockRank 90/70 rule of thumb, which suggests buying near 90 and selling below 70
The trouble with retrospective analysis is that it's possible to prove almost anything you want. Taking the above rule the majority of these stocks wouldn't have been bought 10 years ago as they didn't meet the buy rule.
Meanwhile the best of them - Games Workshop (LON:GAW) - would have been sold during 2022, prior to it near tripling since.
Timing is everything and only hindsight gives us 20-20 vision.
timarr
As I said, it was helpful Ed. Selling at under 70 value rank would mean selling 17 out of 38 holdings. I would be selling e.g. L&G, MBH, Wynnstay, Mercia, CLIG and Mountview Estates. Buying at 90 would mean adding to Braemar, Epwin, Card, Vertu, Severfield and RWS. A dilemma and pause for thought as we have substantially more money invested in the first group.
Very helpful Ed, thank you.
The hardest part of investing is timing a sell rather than picking a stock as a rising tide lifts all boats.
For me, striving not to be wedded to the story of the stock has been the key to selling in a more objective manner.
I soldStride (NYQ:LRN) today for an 80 % gain in just over a year. They have good quality and momentum scores but the price action is failing when the wider market isn't ... time to move on. They could well pick up again and double but flat broker EPS estimates doesn't suggest to me that anything is going to drive the price. I won't look at them again unless the appear on my screen.
Compare that to Celestica (NYQ:CLS) which I hold for a 1283 % gain after holding since Nov '21. They still exhibit good quality and momentum scores plus analysts estimates continue to appreciate. I've top sliced this holding three times between the start of 2025 and mid Feb as it was just too big a risk to hold that much cash in one holding.
Maybe I'm just lucky ?
Jack Nikclaus was once interviewed after he hit a hole in one and the interviewer suggested it was lucky, he replied "It's funny ... the more I practice the luckier I get!"
Previous multibaggers for me include
Fire Angel (prev Sprue Aegis) + 291 %
Washtec AG (ETR:WSU) + 281 %
Limbach Holdings (NAQ:LMB) + 277 % (current holding)
adesso SE (ETR:ADN1) + 239 %
Corticeira Amorim SGPS SA (ELI:COR) + 213 %
Eckert & Ziegler SE (ETR:EUZ) + 212 %
Let's Gowex Sa (MCE:GOW^F18) +155 %
Sinnerschrader Ag (ETR:SZZ^H19) + 155 %
Trigano SA (EPA:TRI) + 143 %
elf Beauty (NYQ:ELF) +142 %
Axcelis Technologies (NSQ:ACLS) + 126 %
Shutterstock (NYQ:SSTK) + 124 %
CellaVision AB (STO:CEVI) + 121 %
GFT Technologies SE (ETR:GFT) + 118 %
Adobe (NSQ:ADBE) + 112 %
easyJet (LON:EZJ) + 110 %
Encore Wire (bought out) + 101 %
Of the 18 listed (including Celestica (NYQ:CLS)), 2 are UK stocks, 5 German, 6 US, 1 Portuguese, 1 Spanish, 1 French, 1 Swedish & 1 Canadian.
That's why I have a European and US subscription to Stockopedia and I use AJ Bell as a broker and I'm prepared to take the hit in terms of FX fees and withholding tax for any dividends.
Hopefully Lets Gowex Sa didn't appear on a Stockopedia screen.
It did appear on a Stocko screen! The financials appeared good that's why everyone was fooled
I got out in May 2014 as the price action started to falter
Love your analysis and articles Ed.
Thanks Anthony
FWIW, I hold RNWH, FOUR and CVSG from the list.
I'm doing pretty well in RNWH. I topped up in Feb 2025, and seen a 23% rise since then (about the same has my first purchase in Apr 2023. So not too shabby.
CVSG: I'm up nearly 30% from Oct 2024. So, again, not so bad. There was a lot of fuss from the CMA which drove down the share price. It's the sort of the situation where one has to take a view, with no guarantee of it being right.
FOUR turned out not to be so great for me. I'm down 40% on that. Ouch. Annoying Orange saw to that. The fwd PE is 13.8, with a divvie yield of 4.8%. I'm looking to top up at some point. This is another situation where one has to take a view. Do you think it is temporary, or is there a permanent shift? I think the former. In fact, arguably, tough conditions favour strong companies in a sector relative to weaker companies.
I think one thing it does show is that valuations are important. Sure, with some companies like EXPN they are expensive and stay expensive. But one has to be careful. There can be many bumps along the way.
A polite reminder to all contributors to use @ preceding the ticker code eg @ EXPN which converts to Experian (LON:EXPN) which allows immediate recognition of the company name and an instant link to the stock report.
"We are sort of brainwashed by Warren Buffett’s success into thinking this is what we should all be doing."
I'm with you, Ed! Like you, I believe that diversification is important. Yeah yeah, sure sure, diversification is the arbitrage of ignorance and all that; but the truth is that no-one really knows what will happen in the future, so you have to hedge your bets.
You also increase your chances of picking the big winner.
My other problem with Buffett is that he makes for excellent soundbites, but those soundbites need a more nuanced interpretation. Like "Rule 1 : Don't lose money and rule 2: see rule 1".
Except, sure, but no-one knows how to do that. Buffett has made plenty of duff calls. It's just the nature of the game. Even gilts carry risk of capital loss if you want to sell them early. So what does "don't lose money" really mean?
Howard Marks is a better writer than Buffett. He is much more nuanced in what he says, but doesn't attract all the starry-eyed adoration that Buffett has. What Marks said was far more sensible: "the job of investing is to intelligently bear risk."
So that's my little rant against Buffett for now.
Oh, one more thing ... a guy on Twitter (he looks fairly knowledgeable) somewhat facetiously put together a "bombed out portfolio" the other day. I said to him that he should definitely track it. The implication being that it might actually outperform the index.
Buffett is often quoted as a guiding light for private investors however, much of what he does cannot be replicated by private investors.
Furthermore the performance of Berkshire Hathaway has under performed gold over 20 year periods in recent years - which perhaps illustrates there is a limit to the BH formula of investing.
https://bmg-group.com/gold-out...
Another factor which cannot be dismissed is the law of compounding. The two principle founders of BH , one lived to 99 and other (still going strong) at 94. Any modest compounding rate is going to look good with this longevity.
Not dismissing the considerable business acumen of Mr Buffett, it is just that the average investor will find it difficult to use his skills as a template for investing.
Buffett
Has buffet not bought decent companies at decent prices and presumably mostly avoided the dross - or sold out quickly at the first sign of trouble perhaps?
I know he held Tesco for a while and cashed pronto before troubles arrived in i think he has bought and sold apple preumably at decent profit and preumbaly made a killing out of aiding banks when they are short of cash.
Any modest compounding rate is going to look good with this longevity.
seems insanity if he has made 19% pa compounded return to say anything other than what he does works well and should not in any manner be knocked. I suggest as he plows his own fourough its not fair to compare against the best perfoming asset classes over the last 20 years - as you are very much cheery picking your comparison against teh best of the best.
returning 19% compounded per year should do great job for anyone adding capital regualrly.
it is just that the average investor will find it difficult to use his skills as a template for investing.
huh why ? you can just buy his company and or try and try and follow him into the material trades he does. Perhaps he has outperformed on areas where others cant copy (without buying the company)
past performance is no guide to the future but i suspect over the next 10 years if you buy his company or copy his holdings you probably will get a decent average return even if its not best in class.
Hey ho we dont know the future , perhaps his replacement(s) may not match his success - i suspect his replacments will at least have been hand picked to follow the Buffett mantra.
I don't think he does get out quick when things turn bad, Tesco (LON:TSCO) he lost loads and admits he took too long to sell. General Electric he pumped in billions in to save it going bust. Heinz Kraft he is still in I think.
Yes he made loads in Apple, McD, Gillette. Find quality companies in their early stages.
Has he beaten the S&P500 recently. He advises investors to just a S&P tracker.
'Perhaps he has outperformed on areas where others cant copy'
He has indeed. He owns several insurance companies outright, which means that he is able to use the insurance premiums paid by the clients (which he describes as the float) to fund new purchases.
He's also acted as "lender of last resort" in a few cases. Occidental Petroleum seems to ring a bell where he did some kind of preference share deal. This is a very specialist operation which is not open to most people, fund managers included.
He bailed out Goldman Sachs during the GFC. That would be beyond my means.
"huh why ? you can just buy his company and or try and try and follow him into the material trades he does. Perhaps he has outperformed on areas where others cant copy (without buying the company)"
The average investor cannot use the insurance float from wholly owned companies to leverage up the investment in other stocks. This is extremely powerful
https://finmasters.com/warren-...
Some of Buffett's most profitable and low risk deals come from being a lender of (nearly) last resort.
https://www.reuters.com/articl...
By all means buy BRK.B to benefit from his skills, but it would be impossible to replicate what he does as a private investor.
Yes, looking at Vast Resources (LON:VAST) last December who would have thought it would be worth 396% more today? I held, sold at a loss, prior to last December thinking it was a real dog.
Very interesting.
I think this highlights the very different situation between investing in a broad index vs individual stocks. It's the same in the US, where if you invested in the S&P500 over a long period of time you did very nicely indeed, but if you'd invested in a frozen snapshot of the index, from 20 years ago, you would have done very poorly.
Even Games Workshop (LON:GAW) had a considerable fall in 2021/2, shares went down from nearly 12,000p to 5,900p.
It is looking quite expensive now. Last September it had a V score of 22, shares were 10,620p.
It is interesting, because quite a few of top trending momentum stocks, have low value scores, when to sell can be tricky. I'm tempted to sell some Rolls-Royce Holdings (LON:RR.) BAE Systems (LON:BA.) Games Workshop (LON:GAW) etc.
Rolls-Royce Holdings (LON:RR.) selling is very tricky decision. I purchased at SP of 231. A small top slice at 402 which i can’t remember the reasoning now but regret. I am using a manual trailing stop now and when it’s triggered (which it has but then SP recovered and moved further forward) I will look again with a view to stick with it or sell. I am thinking the sell will be big not a top slice. I may even leave a very small postion still on the table. Time will tell
Great reminder of the video series, prompting me to rewatch these.
Thanks Ed. I suppose most investors look forward not back and perhaps do not learn lessons from the past so these hindsight viewpoints are great. A review of selling principles would be timely after the recent mini bull run.
And when you do the video on selling, please ensure that all those "quality" investors, who did very well as interest rates declined, get to see it.
Terry Smith, Baillie Gifford, Lindsell Train etc
Each held good companies that got rerated, probably thought they had found the silver bullet of investing, and forgot that valuation does matter!