Why do buses always come in three’s, SLP, THS, JLP

Why do buses always come in three’s, SLP, THS, JLP
After a long period of waiting why do buses come along is a common expression and a real-life experience for anyone using public transport. Apparently, the subject is interesting enough for books to be written about the phenomena. See link below.
https://www.amazon.co.uk/Why-Buses-Come-Threes-Mathematics/dp/1861058624
It seems we have the same phenomena occurring in the investment world when three similar investment opportunities come along at the same time. For example, the extraordinary PGM opportunities with Sylvania Platinum (LON:SLP) Tharisa (LON:THS) and Jubilee Metals (LON:JLP) and the raising rhodium price. The question I'm asking myself is which of these buses should I be invested in?
For further information as to why I think the Rhodium price will remain high, read Sylvania Platinum SLP If I hold, there will trouble if I sell it will probably double. The link is provided below.
As an investor in Sylvania Platinum (LON:SLP) expecting the raising rhodium price to continue and recognizing Tharisa (LON:THS) and Jubilee Metals (LON:JLP) also offer similar exposure I wanted to think about which opportunities offer better returns if prices go higher and risk mitigation if prices fall. To determine which buses to ride I’ve decided to model Sylvania Platinum (LON:SLP) Tharisa (LON:THS) and Jubilee Metals (LON:JLP) and compared valuations with different Rhodium prices. Assuming the 2021 average Rh price is approximately $18000 per TOz, and prices might fall, stay the same or continue to rise in 2022-25.
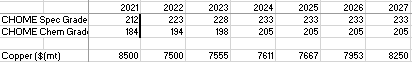
Noting Jubilee Metals (LON:JLP) has substantial exposure to the copper price and Tharisa (LON:THS) has substantial exposure to the chrome price, hence for this evaluation, I have forecasted prices for these commodities as per the table below with only the Rh price changing. Note Tharisa (LON:THS) is the only company committed to increasing PGM production at this point and this is included in the model.
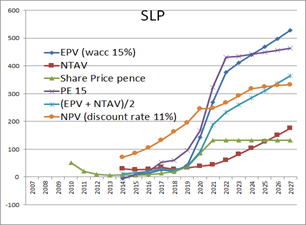
With the current Rh price at $18000, the best-fit valuation (prices investors are willing to hold stock) is probably (EPV +NTAV)/2 hence this is valuation metric is used for all three securities. See graph below.
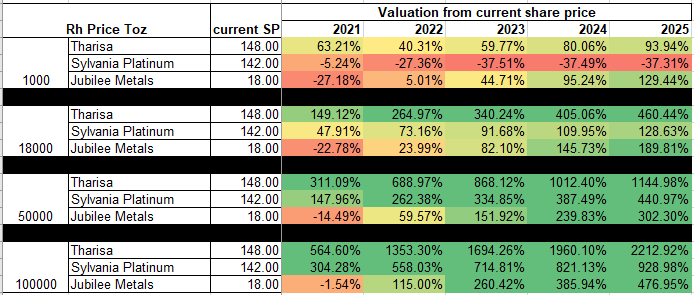
The table comparing valuations for Sylvania Platinum (LON:SLP) Tharisa (LON:THS) and Jubilee Metals (LON:JLP), based on different Rh prices $1000, $18,000, $50,000, $100,000 is provided below.
What do I have reasonable confidence in?
Tharisa (LON:THS) and Jubilee Metals (LON:JLP) offer better downside risk for a falling RH price, as they have diverse revenues from non-PGM commodities namely copper and chrome. Sylvania Platinum (LON:SLP) and Tharisa (LON:THS) are better investments for a rising Rhodium price. Tharisa (LON:THS) is the only company increasing PGM production and benefiting more from a rising price.
What am I doing with my own investments?
For my own investments, I’ve taken a reasonable position in Tharisa (LON:THS), from profits gained with £SLP. I’ve decided not to invest in Jubilee Metals (LON:JLP) as it does not pay a dividend, is currently investing high levels of CAPEX, and the investment case is overly dependent on the copper price.
As always DYOR
BSV
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
24 comments
Excellent article Bluesky Ventura and very useful links for further research.
Many Thanks.
Sylvania Platinum (LON:SLP) Q4 results.
https://www.stockopedia.com/sh...
Results to be expected for Q4, as Rohdium prices cool off. from record Q3 results.
Yearly comparison looks more promising
FY2021 sales come in at $207M ($114, 2020), and net profits of $97M ($41M, 2020).
Still basing my valuation on an average Rh price of 18000, which seems set to last for the medium term.,
200p still looks closer to fair value, but there will be market concern about the Rhodium price.
DYOR
BSV
Agree BSV with your view
Even with lower earnings this quarter than last
Market cap - cash divided by full year earning gives a P.E. of 3.5
With cash of 18.5 p per share so a good full year dividend looks likely though SLP does always seem to take a cautious approach when it comes to keeping cash on the balance sheet
Medium and long term platinum group metals will still be in as there is no replacement for them in many of their applications and that’s before we price in future demand for fuel cells and green hydrogen as discussed in JMAT last quarterly report
I am glad I got off Centamin (LON:CEY) now 106p. £1,193 Dividend dropped in to the account for my troubles too.
So far my holding of Tharisa (LON:THS) has not been joyous -3% but I will collect the Dividend franked today... I am new to Tharisa (LON:THS) and not troubled at this stage.
Oops Sylvania Platinum (LON:SLP) gone -1% for me today too.
StockRank TM is my friend.
Morses Club (LON:MCL) was second on my list when it was 60p, now 87p. (Cock!)
Hi UK_Investor_8888,
I can understand your frustration if share prices drop, something none of us can control. I find it easier to think about the valuation of the business's owned, and if the business case is still valid.
For Sylvania Platinum (LON:SLP) , Tharisa (LON:THS) , Jubilee Metals (LON:JLP) , this is all dependent on the Rhodium price remaining high due to an imbalance in supply and demand. I believe this is still the case.
Johnson Matthey May 2021 report still expects Rh to be in deficit well into 2025.
https://matthey.com/-/media/fi...
Trading economics forecast a 2021 year-end Rh price of 27,000$, see link below
https://tradingeconomics.com/c..
I see this weakness as an opportunity to add to my position.
As always the forecast above may prove wrong as no one knows the future, so as always DYOR and don't trust vloggers, bloggers,s, or any other commentator like myself.
BSV
COVID still has to hit the world economy. UK with furlough wind down - no clue on South Africa. UK can print money and nationalise rail and maybe airports? Sorry hospitality fashion etc is discretionary not top of Maslow hierarchy so apologies to the SCVR. To African governments the miners profits can be diverted without too much hassle. May get a paper gunboat from FO. Oddly enough most carbon neutral initiatives requires holes in the ground.
Momentum Investor also have a coverage. These 'tips' often help fill in the knowledge gaps,to my reckoning.
With regard to director deals, please bear in mind Mr Bird is 75,so might like to distribute some of his investment elsewhere .Cheers stay safe Tony
A lot of tipsters are bias, you wont read very balanced reports from them.
Just to let you know Simon Thompson has added a new piece on JLP 11th june.
Great! Where might we find it?
https://www.investorschronicle...
Does anyone know about the directors dealing on Jubilee Metals (LON:JLP), looks like they are pocketing a lot of the profits, some massive share sales this year. Are the fees in lieu of salary?
Thank you very much Mr Bluesky Ventura.
Centamin (LON:CEY) sold (5% gain), replaced with Tharisa (LON:THS). Centamin (LON:CEY) just seems "limp" and not moving anywhere.
I like the StockRank of 99 and your commentary. I also pick up another Dividend next Thursday and like the Value, Growth and Cashflow.
I hold a large Sylvania Platinum (LON:SLP) position already.
my understanding is that Centamin (LON:CEY) is going to remain restricted while the instability issues are rectified which could take 3 years and a great deal of money. On this basis I sold earlier this year at a small loss and bought into Capital (LON:CAPD) the company commissioned to sort out the problems at the centamin mine.
Firstly Thank you for a very interesting discussion.
I have a holding in SLP, bought last year and showing a 90% gain. The stats were compelling,and after one false start- after they mentioned electricity,and water supply problems,pushed me thro' the 10% stoploss. However the figs were still compelling,and i rebought,and intend to hold whil'st the green revolution creates such demand on the PGM basket ,this alone will fill the bottom line. The reason I hav'nt added a great deal more is because this management see to have little ambition, beyond paying out their surplus :- as either divi.,or buybacks.
My BIG buy out of the three is JLP. I started out here in the days of Braemore,and the novel 'conroast' extraction process.Never seemed to go forward,although it did seem an excellent new way to extract PGM's from ore rich in Chrome. My mining friend explained what an excellent idea this was if it could be converted on scale. Anyway that was years ago,but does seem to be coming to fruition now. I left a long time ago .
However during the early days of the pandemic ,it appeared to me the green,especially EV movement got a real shove on. Due to the comment I was seeing I had another look at JLP [i had bought a few,and sold several times over the years-never a serious investment]. The problem was they would come out with a decent trading statement,and before you knew it,they were diluting one's holding yet again,for another project. However since Leon has taken on 'the boss' roll this is becoming history, almost certainly helped by being in the commodity 'sweet spot' ., Thereby producing the profits to payroll the capex required -hence no dividends, but no additional dilution,except for bosses warrants [ which have often been taken in lieu of a larger salary].
Since this article was written JLP have made two announcements that will mean a large increase to the bottom line[although a new capex spend seems likely for the east ridge spoil]. I think we will hear a lot more about this expansion ,after all two major deals in two days in this one area . I believe there will be more,and following on from that a new plant has been mooted.
Stoko's figs I believe will be upgraded by brokers fairy soon,but make VERY pleasant reading anyway. Add to this one Cu project up and running,and two more, very close to production . Hence my making a substantial investment here.
On Tharisssa l have never indulged, good luck to all your investments. Just thought ,my comment might suggest JLP were worth some more research ,as a decent growth company. Cheers stay safe Tony
Hi Tony,
Noticed the Jubilee Metals (LON:JLP) announcement, which should add to revenues. I find the lack of information explaining the CAPEX spend related to it frustrating and makes valuations difficult. Hence I hold back in buying the stock. Until they start returning some capital to shareholders and share more information on CAPEX I can't invest.
BSV
Hi BSV.
I have committed a good deal here which is about 180% up overall, ,my last buys about 15/16p. [I started during lockdown - 1, at under 3p Ithink] Divi.:- Even though i'm in my 70's J Slater zulu,is my major way of investing,I feel JLP is fitting many of his 'sieves'.
As long as the eps is growing[especially so strongly currently] at a decent rate i'm not worried about divi.,as the share price is likely to reflect the companies earnings. Much better to invest the spare cash to enlarge the business[I have done extremely well in the past using this technique ,and SDI is my biggest ever,starting at first buy 12.5p].
Much of your anxiety might be settled with the july 12th statement.
Good luck with your decision,stay safe Tony
One question which someone here might know the answer to re Sylvania Platinum (LON:SLP): What is the nature of the contracts with the feedstock suppliers - looking at the latest presentation all I can see is this: "Profitable operational life of approximately eight to ten years". It sounds like they have some kind of exclusive contracts. But do the supplying mines have any on-going pricing power? I assume not since this is not presented as a risk.
Hi Robert,
I believe your opinion is correct. They are processing other companies' tails, and have few assets of their own.
BSV
Any ideas why Tharisa (LON:THS) doesn't have a Jim Slater PEG assigned? If Tharisa (LON:THS) qualifies for a Jim Slater PEG then it could well lead the Stockopedia comparisons: https://www.stockopedia.com/co... Interesting to see that Tharisa (LON:THS) leads the historic metrics, but Sylvania Platinum (LON:SLP) is wining the quality and RSI ones. Thanks BSK for interesting insight :-)
I couldn't decide so I hold all three - but thanks for the interesting analysis
SLP and Tharisa also have excellent corporate governance .
a nice RNS this morning from JLP. Growing fast.
Not a fan of public transport but I do hold all 3 stocks, mainly SLP but starter holdings in THS and JLP whilst I learn more about the cos. Thankyou very much for this incisive appraisal