Yü Group - the business grew 19%, the rating didn't move

[Disclosure: at the time of publication, James Fox has no position in Yü Group.]
When Ed (Croft) picked Yu (LON:YU.) for the New Year NAPS, the market cap was £253 million and the shares were on a forecast P/E of 6.8x. He labelled the stock as a strong multibagger that had consolidated in 2025.
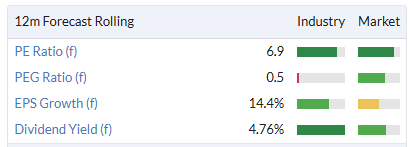
The market cap is now £288 million and the shares are still on a forecast rolling P/E of 6.9x.
In the first half of 2026, revenue rose 19%. Over the twelve months to 30 June, the forward contract book rose 45% and meter points rose 43%.
The business has grown, but the rating has stayed put. As someone who has watched this stock from afar for a while, the pattern is getting familiar. Once a multibagger, it has traded in a range for two years, with a couple of breakouts that came back.
But two years ago, the stock traded at 7.6x forward earnings and sat on a net cash position of £30.5 million – enterprise value of £228 million. At last year’s end, the balance sheet was stronger (£94.7 million in net cash) and the enterprise value now sits at £193 million.
My take, the next breakout holds.
The Pitch
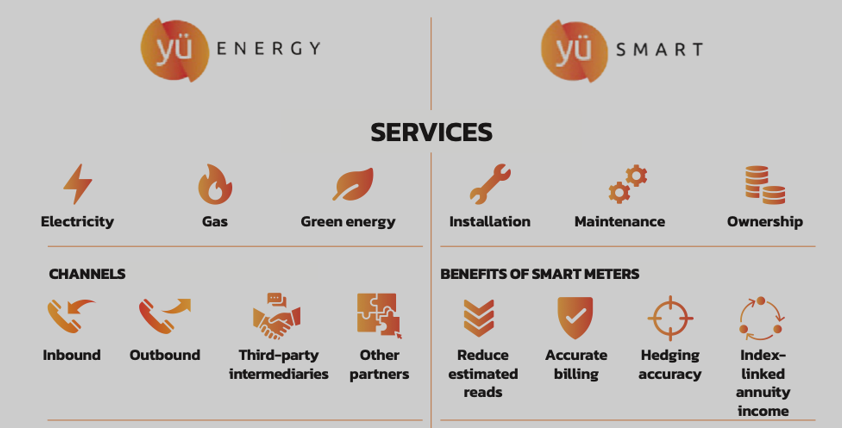
Yü sells gas, electricity and water to UK businesses rather than households. It also owns and installs smart meters, which gives it an asset generating recurring, index-linked income alongside the supply contract. Founder Bobby Kalar still runs it and owns roughly half the equity.
Two things make the model work. It buys energy forward through a hedging facility with Shell, now extended to 2032, which lets it fix prices for customers without posting collateral against commodity moves – Roland flagged this in his 21 July note as something that reduces the capital the business needs to grow. And that facility has the capacity to support annual revenue of over £2 billion, against guidance of £850-875 million this year. The runway is already funded.
A quick note on Kalar: as Roland pointed out in July, his dividend income runs well ahead of his pay, which aligns him with shareholders. But owning half the equity cuts both ways – reducing his stake would put downward pressure on the share price, and there's no takeover without his say-so.
Source: Yü Group FY2025 Results
The Big Picture
Yü is a small supplier in a very large, very concentrated market that is slowly being prised open. The structural drivers:
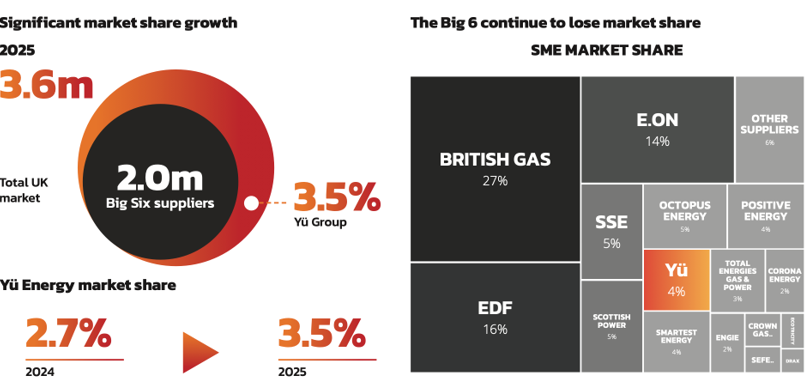
- A £50 billion addressable market. The UK business energy market covers over 3.6m meter points, with the SME segment alone accounting for 2.3m.
- The Big Six are losing ground. They still hold 2m of those 3.6m meter points. British Gas remains the largest at 27% of the SME market, with EDF at 16% and E.ON at 14%.
- Yü takes far more than its share of switchers. It acquired 11% of all B2B market switchers in 2025, against 7% in 2024. Its SME market share has gone from 0.9% in 2022 to 3.5% in 2025. Management targets 7-9% by 2028.
- The smart meter rollout has a long way to run. Around 800,000 non-domestic meters are still traditional. Yü Energy held 69% smart or half-hourly meters at the end of 2025 against a UK-wide 59% for smaller non-domestic sites, and expects to pass 75% during 2026.
- Owned meters are annual income. Meters have a 15-year life span and migrate if the customer leaves Yü Energy – the income outlives the supply contract.
Each of these should provide tailwinds. A fragmented market losing share to challengers, a regulator pushing smart meters, and an owned-meter base that turns each win into recurring income.
“Despite having grown from <1% market share to 3.5% market share in three years, the scale of opportunity remains exciting and challenging to make significant gains.”
-- Yü Group Annual Report 2025
Source: FY2025 Results
Going Deeper
Revenue has climbed from £102 million in 2020 to £700.4 million in 2025, with operating margin moving from -1.6% to 6.4%. Guidance for 2026 is £850-875 million of revenue, with adjusted EBITDA and profit before tax in line with 2025 while £9 million goes into sales and operations.
In the update of 21 July, half-year revenue was around £405 million, up 19%. Panmure Liberum and Cavendish both left forecasts unchanged.
- Yü Retail: the supply of electricity, gas and water to business customers in the UK. The forward contract book reached £1.7 billion at the half year, up 45%.
- Yü Smart: the provision of engineering and related services to install and maintain smart and other meters. Installations ran at 12,000 in the first half, up 27%. Full-year installations fell in 2025, to 16,400 from 22,900, while the division went through a system and process transformation.
- Metering Assets: the ownership and rental of smart metering assets. Yü owned around 55,000 meters at the half year, up 37%, alongside 153,000 meter points under management, up 43%. Index-linked annualised recurring revenue from those assets is projected at £3 million, against £1.8 million a year earlier.
The contract book is the line that matters. It represents energy Yü has contracted to supply but not yet delivered, with c.£700 million of it already booked for 2027. It is the nearest thing an energy supplier has to visibility.
Valuation
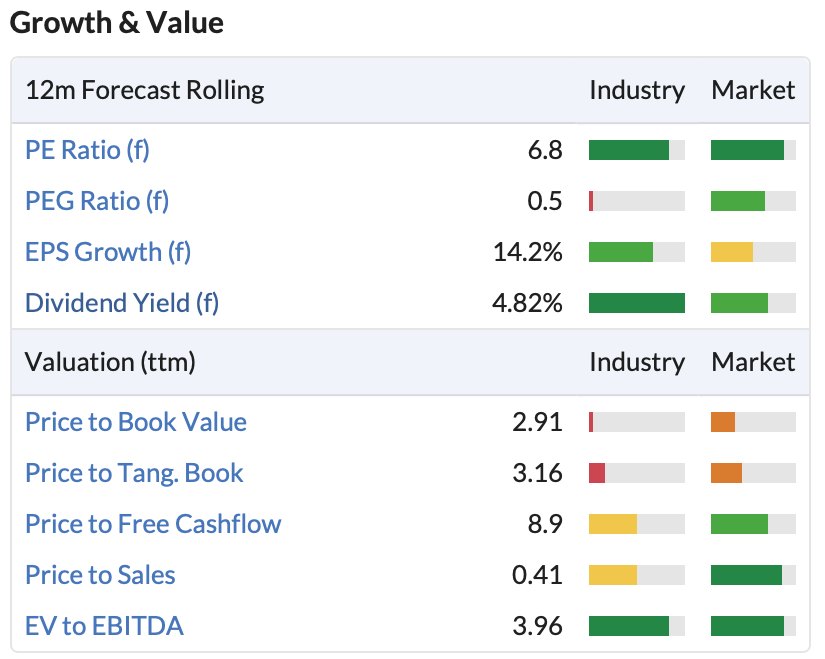
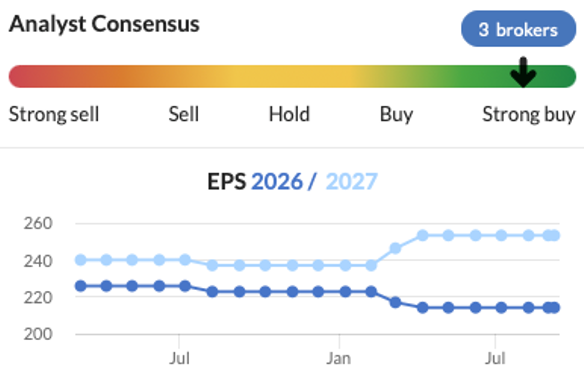
- 6.9x rolling forward earnings, PEG of 0.5: 7.7x on 2026 consensus EPS of 214p, dropping to 6.5x on 2027's 253p.
- A 4.8% yield, covered three times: the dividend has gone from 3p in 2022 to 67p in 2025.
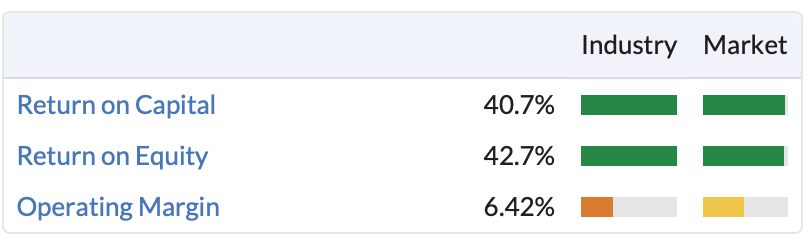
- An EV of £193 million against a £288 million market cap: that's 4x EBITDA, on returns of 40% on capital.
These figures are outstandingly attractive, and don’t appear to reflect the business I’ve been describing.
What the Brokers Say
Three brokers cover the stock with a consensus target of 2,304p, 40% above the price. Coverage is thin, and the target should be read accordingly. Estimates for 2026 and 2027 have not moved in three months. Nobody has cut numbers into the share price fall.
The Bear Case
- Bad debt. Rose from 2.1% of revenue in 2024 to 2.6% in 2025. With SME customers in a weak economy, small moves in bad debt move profit a long way in the wrong direction.
- The cash is not spare. Net cash was £94.7 million at the 2025 year end, but Roland's read is that a business like this needs strong liquidity, so he doesn't view net cash as surplus to requirements. Panmure Liberum forecasts closer to £50 million by the end of 2026 – that would make the business more expensive on an EV-to-EBITDA basis than I suggested previously, but still cheap.
- Competition. Larger suppliers with more scale can price against Yü, as Telecom Plus has reported in the consumer market. That would make the 7-9% target more expensive to reach.
- Liquidity. 17.3 million shares in issue, a free float of 38.75%, and an exchange market size of 150. Easier to buy than to sell.
The Bottom Line
Yü is a better business than it was two years ago, and the shares are no dearer. It’s a phenomenal value proposition. Bad debt is the thing that could spoil it. But the contract book is up 45%, the meter base is compounding, and nobody has cut a forecast.
Interims land on 22 September, and they're worth watching. But looking at the Stock Report, it's hard to see why this isn't trading higher already.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Surprised that no reference to the threat by Gatemore Capital at the end of August to oust the whole board unless action was made to produce a plan to turn around the business by October. This should have been highlighted. A warning should have been given, particularly as it is still rated a Stock Rank of 98!
raspamarg
Surprised that no reference to the threat by Gatemore Capital at the end of August to oust the whole board unless action was made to produce a plan to turn around the business by October. This should have been highlighted. A warning should have been given, particularly as it is still rated a Stock Rank of 98!
is that not possibly due to the fact there there is no such threat and you appear to be mixing up Yu (LON:YU.) and YouGov (LON:YOU) - you need to be careful not to get your u's mixed up :) - unfortunately they have annoying similar names.
A small-cap growth opportunity backed by strong capital discipline and structural market share gains, Yu Group presents a resilient, long-term compounding opportunity IMO, a useful dividend too.
I agree the next breakout could stick. I hold.
I've held YU for 5 years now and like many am mystified as to why the share price hasn't risen to reflect increased business and profitability, but reassure myself, rather than be tempted to reduce my holding, by looking at the meteoric climb of the value per share.
I binned them a couple of months ago.
I have held it in the past, sold out early this when over 1900p. It is tempting to reinvest. But Telecom Plus (LON:TEP) have had a poor time recently.
completely agree. A contrarian stock based on sales metrics but with strong Buffett style quality characteristics.
Great write up and quite agree.
Buy when its quiet, sell when its noisy.
Ive bought more based on this. Thanks.
Totally baffling to me, especially with Middle East/Ukraine situatuions
Thank you James, it goes into my watch list.