Good quality companies don’t necessarily stop being good when their share prices fall. In fact, lower prices can be a blessing to a strategy that combines two of the most influential drivers of investment returns: Quality & Value. A Contrarian, in the StockRank Styles, is a share whose Quality and Value ranks are both above 50 while its Momentum rank is below: good, cheap and out of favour.
It’s a strategy that has been executed with devastating success by some of the investing world’s best known names, ranging from David Dreman and Joel Greenblatt to Warren Buffett. The philosophy was best summed up by Greenblatt in The Little Book that Beats the Market[1]: “buying good businesses at bargain prices is the secret to making lots of money.”
Why quality plus value is effective
In the taxonomy of stock market winners, Quality plus Value (QV) stocks are cast as the market’s Contrarians. These are the shares for value investors who don’t get hung up about positive momentum. Often they don't have an improving price trend, which turnaround investors use to find value stocks that are on the mend. But equally, Contrarian plays are less likely to be the deeply discounted shares with no quality and no momentum, that can end up being Value Traps.
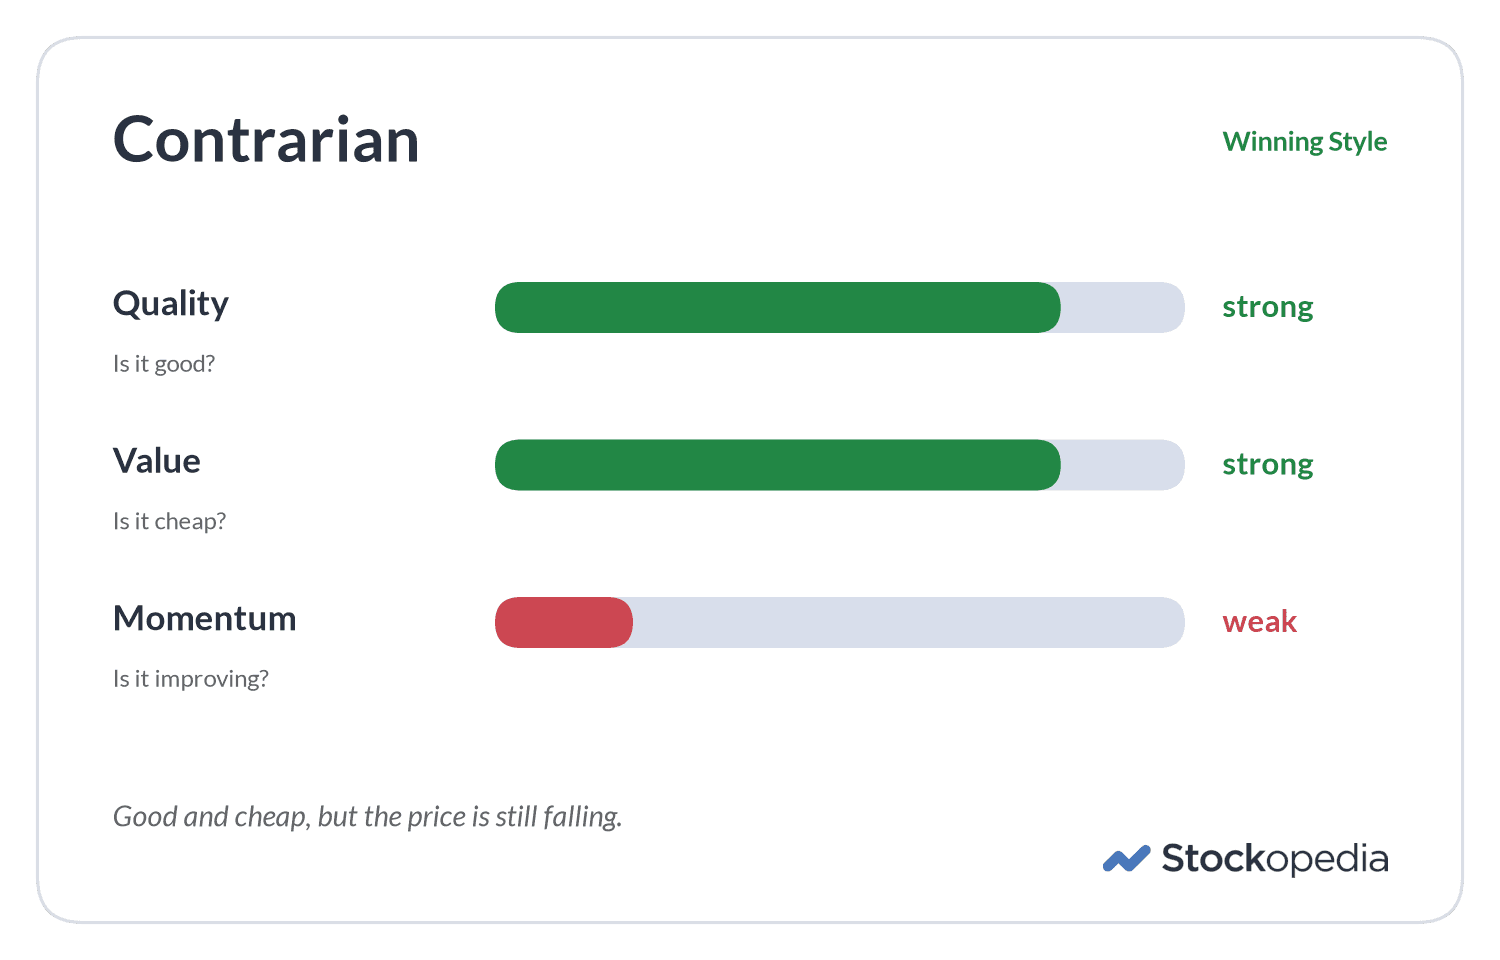
Instead, Contrarian plays need investors to be sanguine about market sentiment and concentrate on buying quality at a reasonable price. As Warren Buffett termed it, “whether socks or stocks, I like buying quality merchandise when it is marked down.”
The appeal of this approach is that it introduces an important safety factor to value methods that simply focus on degrees of cheapness. One researcher that has looked closely at this is Robert Novy-Marx, an assistant professor of finance at the University of Rochester in New York. He has written that there is a strong philosophical connection between quality and value:
Quality can even be viewed as an alternative implementation of value - buying high quality assets without paying premium prices is just as much value investing as buying average quality assets at a discount.
Novy-Marx’s investigation into the effectiveness of Quality and Value found that trading on both signals achieved the double benefit of increasing expected returns while decreasing volatility and drawdowns. He noted, “cheap, profitable firms tend to outperform firms that are just cheap or just profitable.”
What Contrarians paid
Stockopedia's own data says the same. We grade every stock in the market for the strength of its Quality, Value and Momentum in the StockRanks, and we have measured what each of the nine StockRank Styles returned across thirteen years of UK data. The chart below is the same one used in the series overview.
Contrarians returned +7.1% a year, against +5.7% for the average UK share. The quality bar is what separates them from Value Traps: cheap shares that are also deteriorating, but without the quality, returned -1.0% a year. The momentum bar is what separates them from Super Stocks, which returned +15.3%. Quality turns a cheap, falling share from a trap into a Contrarian. Momentum turns a Contrarian into a Super Stock.
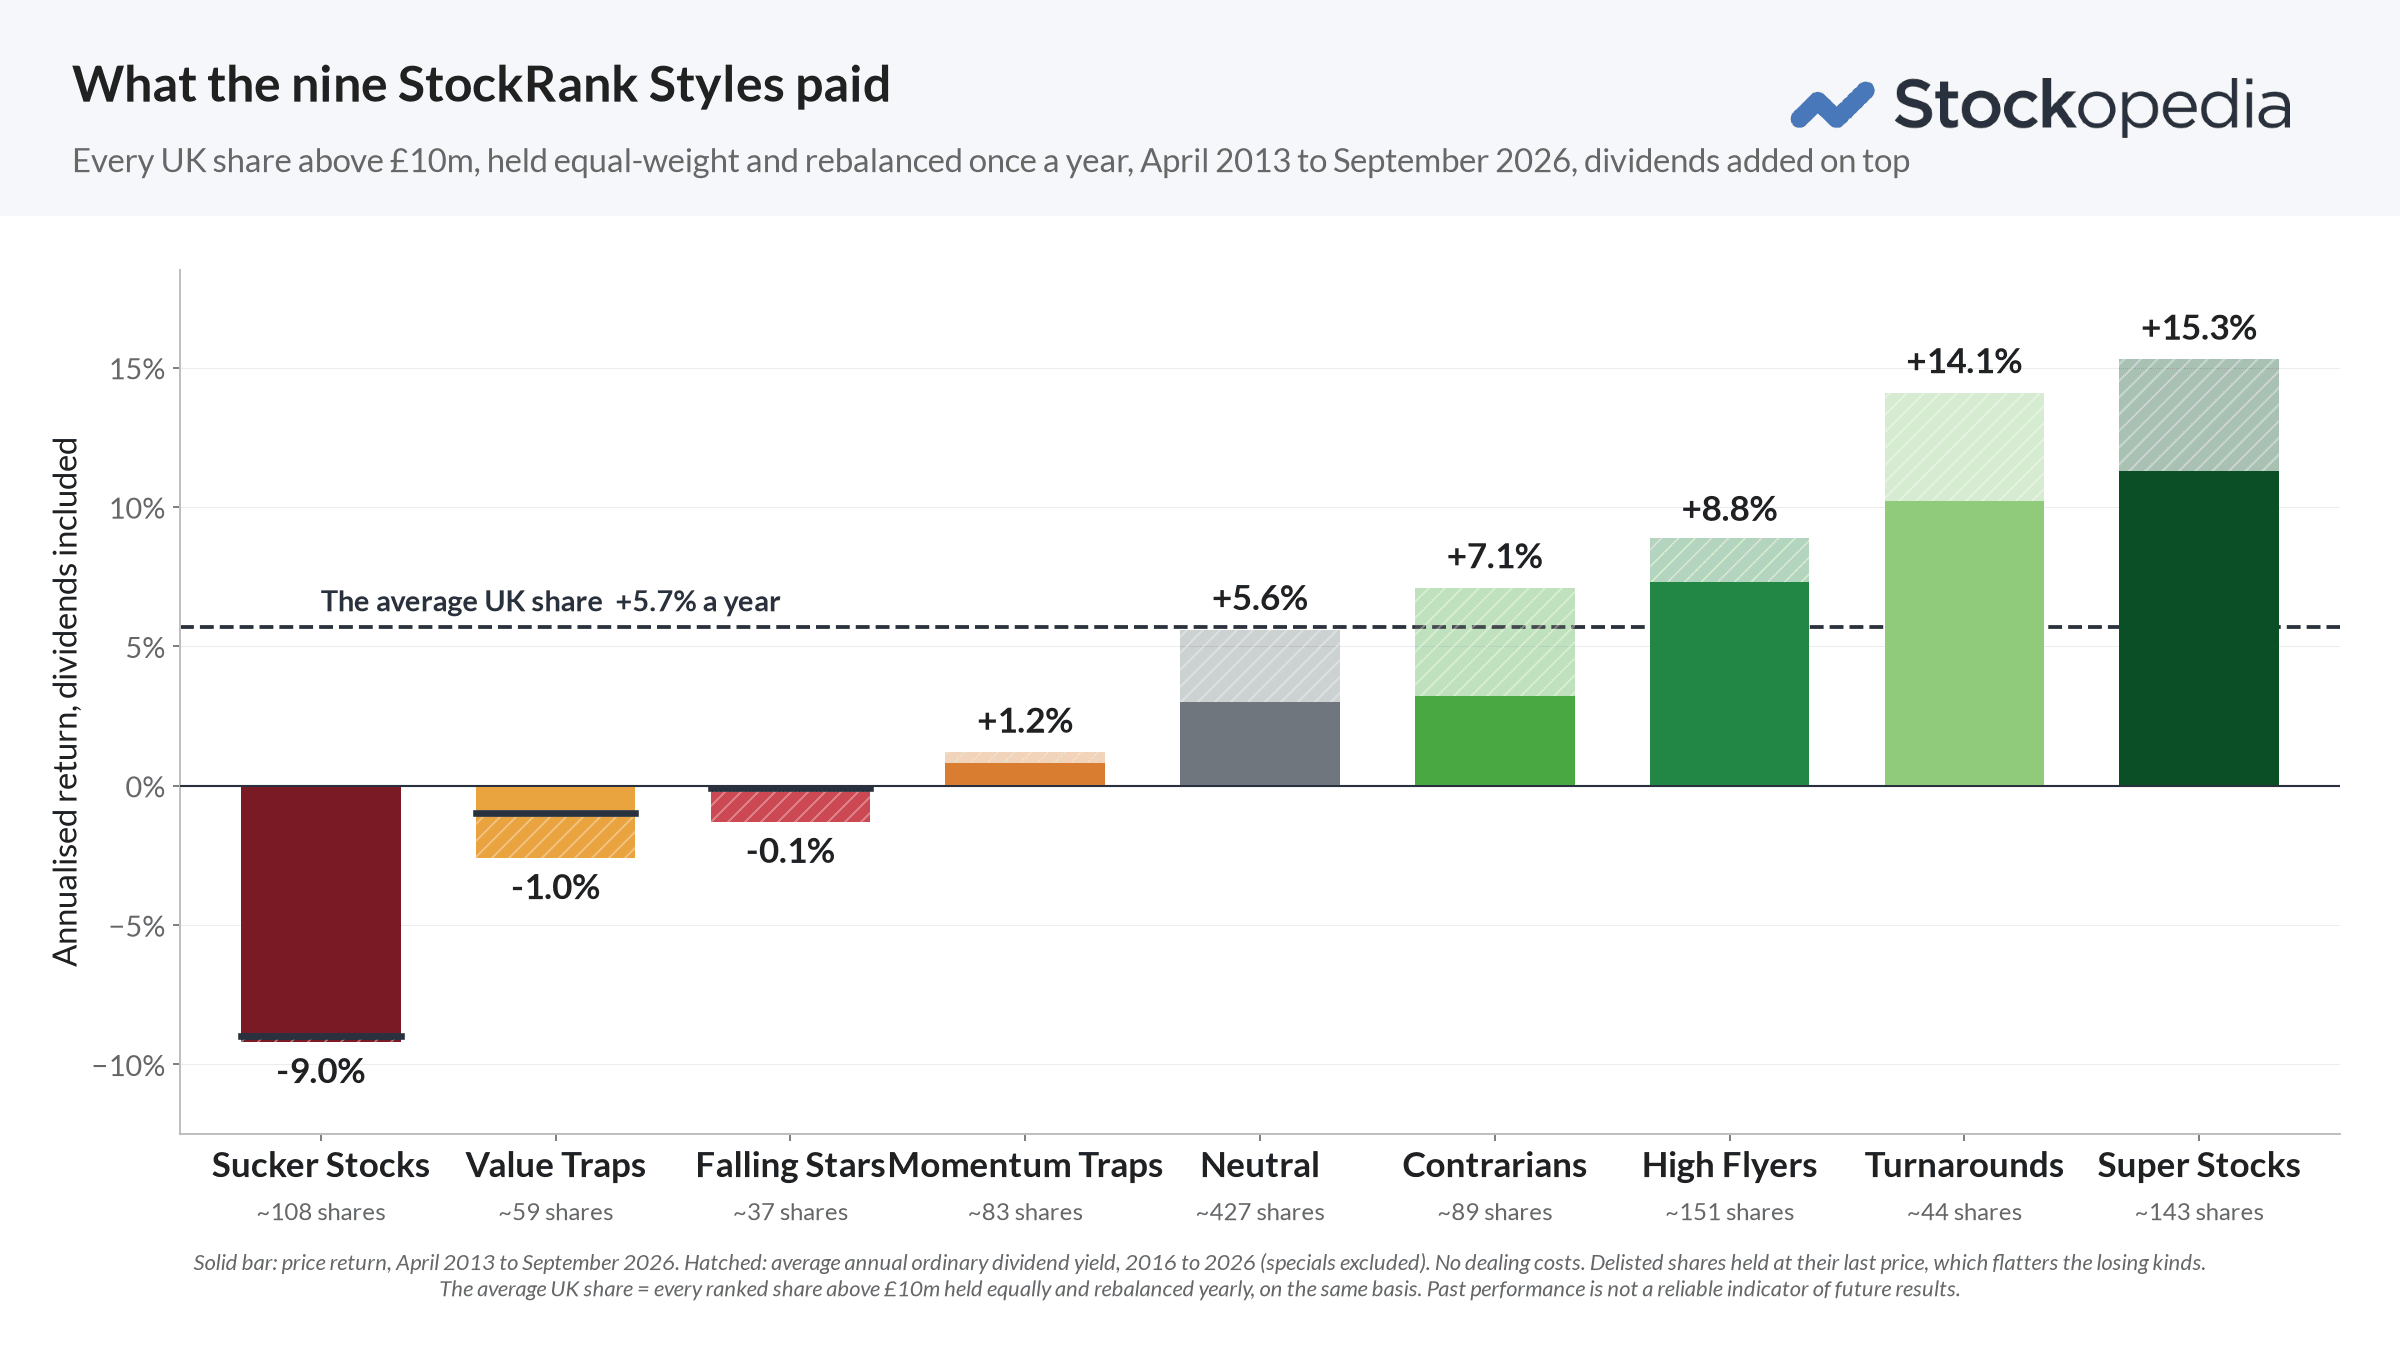
UK shares above £10m, held equal-weight and rebalanced once a year, April 2013 to September 2026, price return plus the average ordinary dividend yield measured 2016 to 2026, no dealing costs. Past performance is not a reliable indicator of future results.
There is an honest caveat. The Contrarian edge was almost entirely the dividend. In price terms alone, Contrarians returned +3.2% a year, slightly behind the average share at +3.4%. What put them ahead was an average dividend yield of 3.9% a year, level with Turnarounds and just behind Super Stocks at 4.0%. Good, cheap, out-of-favour companies pay you to wait. The price gain comes, if it comes, only once momentum turns and the share stops being a Contrarian.
Contrarians also need time. Their price gain arrives when momentum turns, and that can take a year or two, so a one-year holding period undersells them. Held over longer periods, such as two years, Contrarians have tended to do better. The case study below shows why.
A case study: Marks & Spencer
Right early feels exactly like wrong. That is the Contrarian lesson, and Marks & Spencer in 2022 is a clean example.
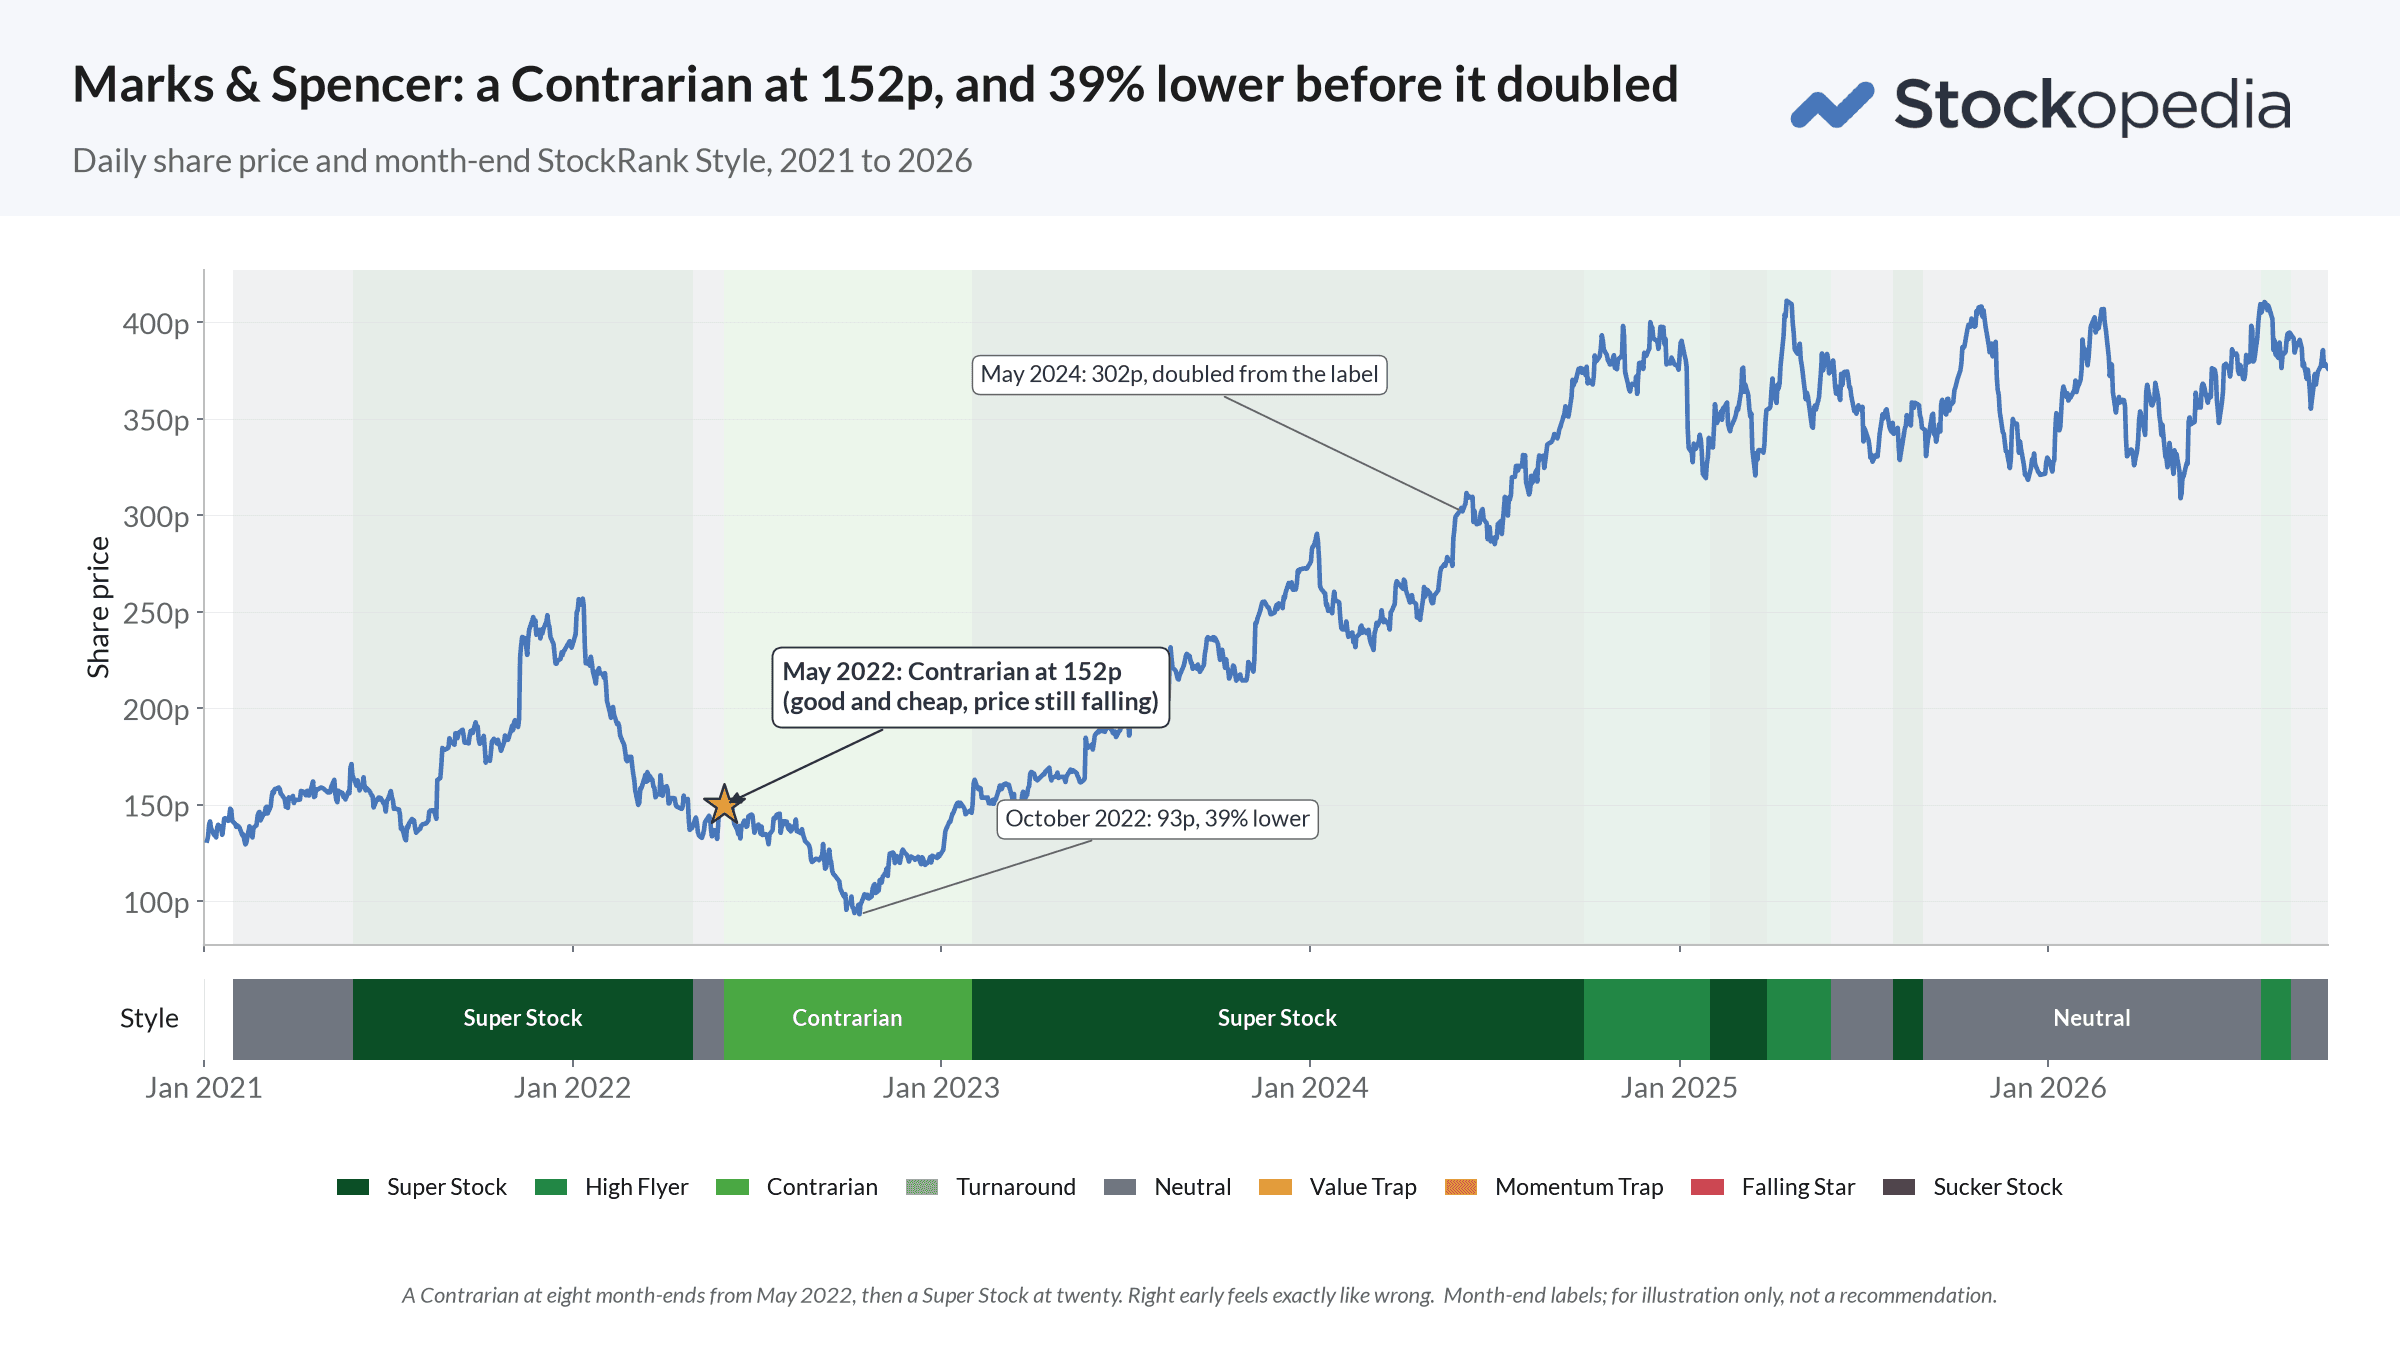
M&S had been a Super Stock for most of the previous year. By the May 2022 month-end the price had fallen to 152p, momentum had turned weak, and it was reclassified as a Contrarian: still good, still cheap, but with the price going the wrong way. Anyone buying it as a Contrarian then had to sit through a further 39% fall to 93p by October 2022. It stayed a Contrarian for eight month-ends in all. Then momentum turned, the Style flipped to Super Stock, and it stayed one for the next twenty month-ends. By May 2024 the share was 302p, double the price at which it became a Contrarian.
The point of the example is the shape: the reclassification came while the price was still falling, and the patience it demanded was paid for later.
How the experts combine quality and value
Introducing Quality to a Value strategy requires defining what Quality really means. It’s a question that’s been under the microscope of academics and professionals for decades and is still to be pinned down. Value is always defined relative to price, whether using relative measures like price-to-earnings and price-to-book or more complex intrinsic value measures like Discounted Cashflows, but Quality is much more amorphous to measure.
Quality measures often focus on profitability, earnings growth stability, cash generation, pricing power, efficiency and balance sheet health - and an absence of accounting red flags. These types of measures are often used to gauge the strength of what Buffett refers to as a company’s ‘economic moat’. These are the deeply embedded quality characteristics that can help a firm resist attacks from competitors and produce strong returns over the long-term.
As a result, a Buffett-like strategy would likely look for high industry leading operating margins and positive levels of free cash flow that can be reinvested by the company. Those investments themselves produce strong returns, which can be seen in measures like return on capital employed (ROCE) (search for > 12% ) and return on equity (ROE) (search for >15%).
Alternatively, it’s possible to take a checklist approach to measuring Quality. Back in 2000 American finance professor Joseph Piotroski introduced his nine-point F-Score of balance sheet health. It has since been adopted by finance professionals and banks like Societe Generale as a means of identifying improving fundamental trends in a business. Piotroski originally designed the F-Score as a way of picking potential winners from a basket of the very cheapest stocks in the market (where failure rates are high). He showed that over a 20 year test period, adding this quality factor to a bargain value strategy improved returns by at least 7.5% annually.
Another QV approach worth considering is American fund manager Joel Greenblatt’s technique of ranking the market using ratios that represent each factor. With his Magic Formula strategy, Greenblatt used two metrics: Earnings Yield (as a measure of cheapness) and Return on Capital (as a measure of quality). Every company is scored and ranked against each measure and the scores are added together to arrive at a Magic Formula score.
Greenblatt claimed 30%+ annual returns from this strategy in his backtests, although others have failed to recreate them. Even so, it remains an almost legendary example of how quality and value can be combined with great success.
Practical steps to finding quality value shares
There are lots of ways to screen for Contrarian shares - an investor can hunt using some of the metrics mentioned above, but the Stockopedia StockRanks provide a shortcut. Every StockReport shows the StockRank Style at the top, and the Stock Screener can filter for the Contrarian Style directly. Subscribers can also access our Contrarians Stock Screen here, a tighter version of the Style which seeks to identify stocks based on:
QV Rank > 80 (ie. cheap and good)
MomentumRank < 40 (ie. muted price strength)
Market Cap > £50m (ie. excluding nano-caps)
There is no denying that the contrarian nature of these rules picks up stocks that have felt the wrath of the market. Some languish in depressed sectors like mining and energy, while others may have sprung bad news on investors - and are now paying the price. So it is important to DYOR. Our Contrarian Quality strategy guide goes deeper on finding these shares and when to sell them.
I would argue that a Quality and Value approach captures the spirit of what investors should be looking for in the stock market. At the extreme, the strategy may help to find diamonds in the rough at the very cheapest end of the market. But it also echoes the quality-driven philosophies of fund managers like Terry Smith. For Smith, quality is a prerequisite, but he still resists overpaying for those assets. So I think the message is that quality can add a greater degree of comfort (and performance) for investors who love looking for a bargain.
To see how Contrarians compare with the other eight Styles, and to check which Styles your own shares fall into, watch the replay of our webinar Four kinds of share lose money. Do you own one?.