In May 2019, ITM Power was a 34p share with a big story. The hydrogen electrolyser maker had spent the previous six months as a Sucker Stock: weak on quality, weak on value and weak on momentum. Then the hydrogen story caught fire. The price started rising, and at the May 2019 month-end the Style changed to Momentum Trap.
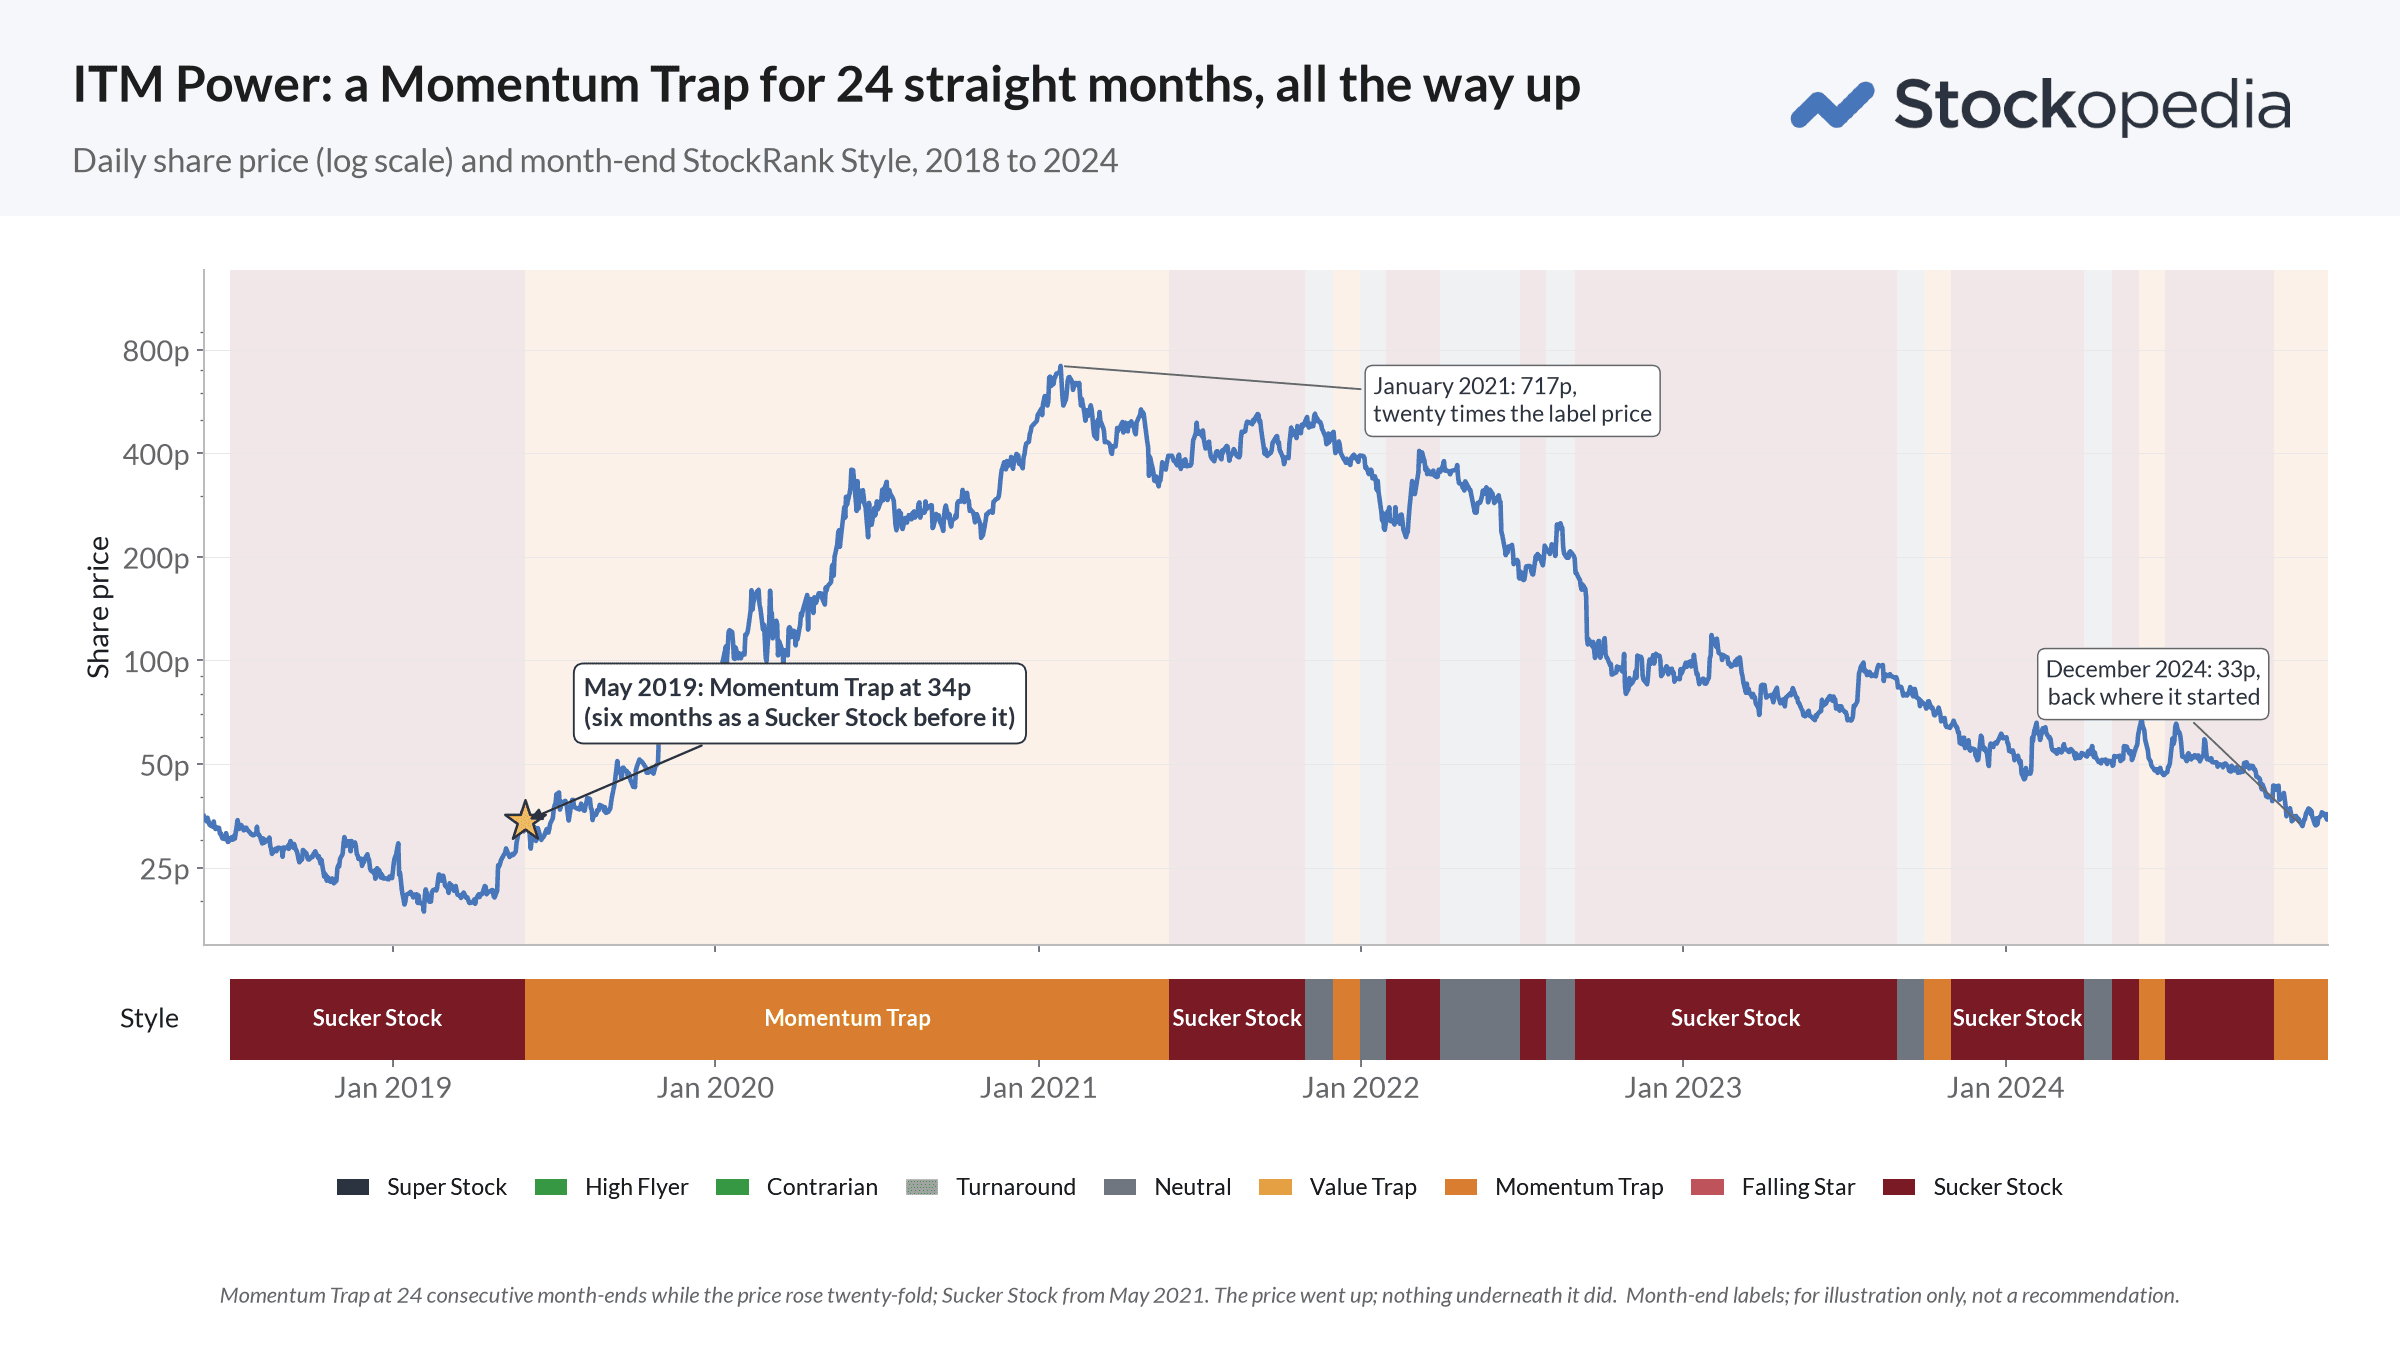
It stayed a Momentum Trap for 24 consecutive month-ends while the shares rose twenty-fold, to 717p in January 2021. All the way up, the Quality and Value ranks stayed weak. The price went up; the business underneath it didn't. From May 2021 the momentum was gone, it was reclassified as a Sucker Stock, and by December 2024 the shares were 33p, back where they started.
A note on reading the chart: the price scale on the left is a log scale, so each step up is a doubling (25p, 50p, 100p and so on) rather than the same number of pence. That way the rise from 34p and the fall back to 33p are drawn fairly, as the percentage moves shareholders actually lived through.
No one could have called the top. But all the way up, the StockRanks were saying the same thing: there were no profits and no bargain here, just a rising price.
The Momentum Trap has its own refrain: "It's off to the moon, I must buy now." At our webinar Four kinds of share lose money. Do you own one?, 14% of investors said that sounded most like a share they had lost money on.
What is a Momentum Trap?
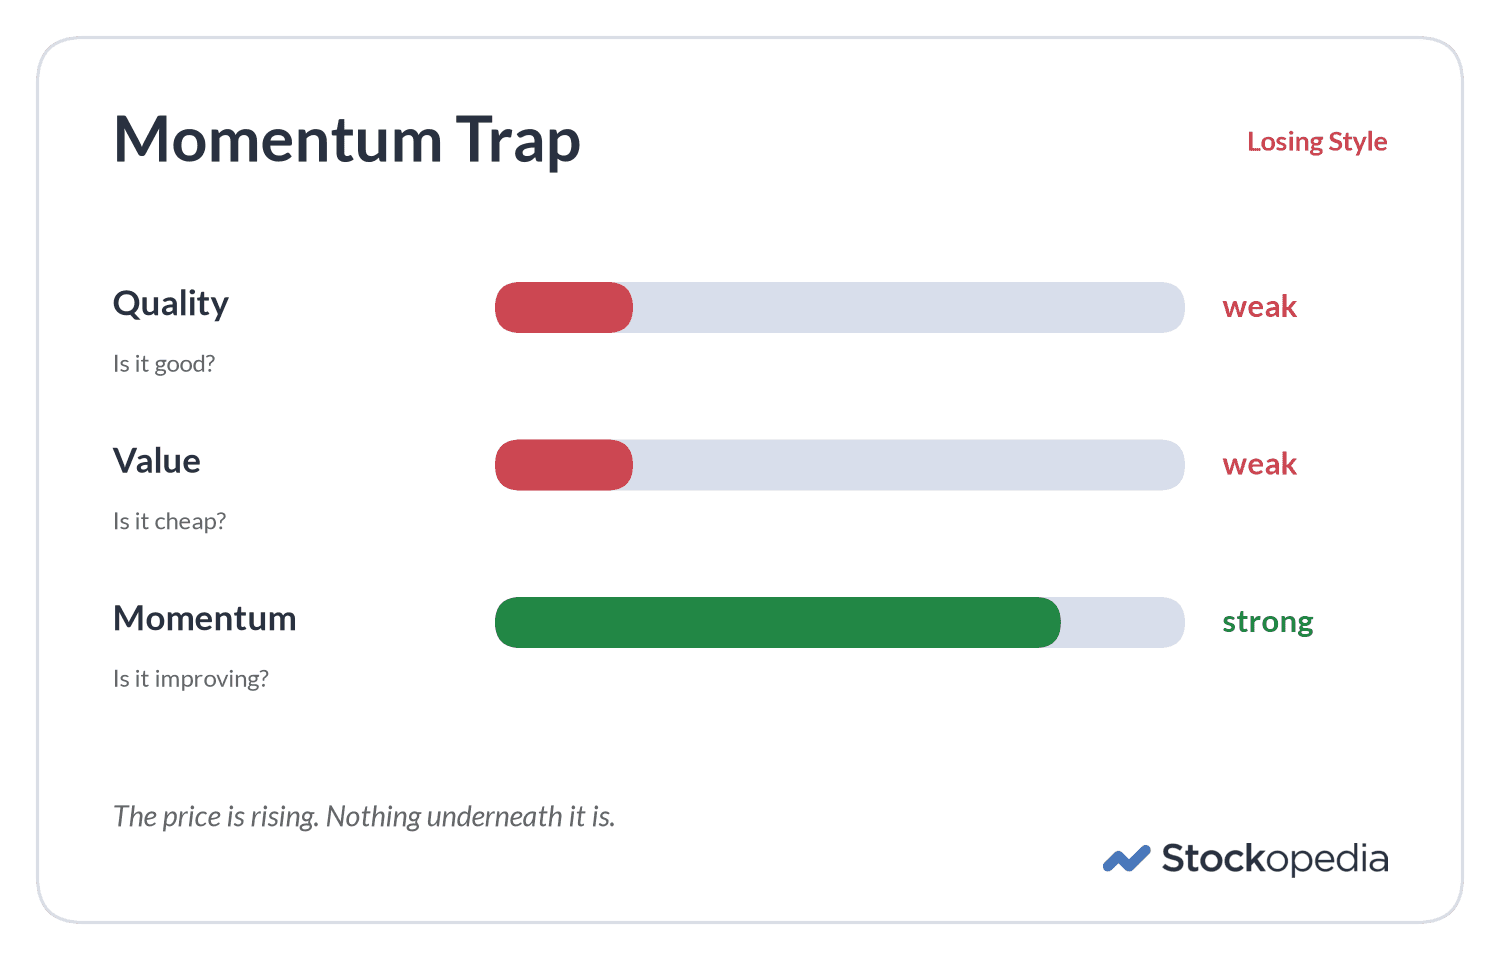
A Momentum Trap is rising, but neither good nor cheap. In StockRank terms:
Rising means a high Momentum Rank. The share price is strong relative to the market, often with forecast upgrades or an exciting story behind it.
Not good means a weak Quality Rank. The company has low or negative returns on capital and thin margins. Often it isn't making a profit at all.
Not cheap means a weak Value Rank. The share trades on a high multiple of its earnings or sales, if it has earnings to measure.
A share is a Momentum Trap when its Momentum Rank is above 50, the top half of the market, and its Quality and Value ranks are both below. It has one strong factor out of three, which makes it one of the four losing StockRank Styles.
What Momentum Traps paid
Held as a basket, about 83 UK shares at any one time, Momentum Traps made +1.2% a year from April 2013 to September 2026, against +5.7% for the average UK share. Almost none of that was income: the price return was +0.8% a year and the dividend yield just 0.4%, because expensive, low-quality companies rarely pay one. £100 became £112 before dividends. Add dealing costs and the bucket lost money, at about -3.3% a year. On average, only 39% of Momentum Traps beat the median UK share over the following twelve months.
Momentum is one of the most powerful forces in the market, so why doesn't it pay here? Line up the Styles that all have strong momentum and the answer is clear:
UK shares above £10m, held equal-weight and rebalanced once a year, April 2013 to September 2026, price return plus the average ordinary dividend yield measured 2016 to 2026, no dealing costs. Past performance is not a reliable indicator of future results.
Momentum works best when it has something underneath it: a good business, a cheap price, or both. On its own, it barely paid at all.
Why we fall for them
Faced with a $10 bottle of wine and a $90 bottle, which would you prefer? In one experiment[1], with the prices clearly marked, nearly twice as many people preferred the taste of the expensive bottle. Unknown to the volunteers, the two wines were exactly the same. Told something is expensive and special, we tend to like it all the more.
The stock market works the same way. Popular story stocks attract herds of followers and eye-catching momentum, and the excitement makes it easy to overlook the losses and the valuation. James Montier of GMO calls this the biggest danger investors face:
Of all the dangers that investors face, perhaps none is more seductive than the siren song of stories. Stories essentially govern the way we think. We will abandon evidence in favour of a good story.
In The Little Book of Behavioural Investing[2], Montier points out that value shares tend to come with poor stories, so they end up despised rather than admired:
Which would you rather own? Psychologically, we know you will feel attracted to the admired stocks. Yet the despised stocks are generally a far better investment. They significantly outperform the market as well as the admired stocks.
Academics Josef Lakonishok, Andrei Shleifer and Robert Vishny explained why in a famous study of glamour and value shares. Investors consistently overestimate how fast glamour stocks will keep growing, extrapolating the past too far into the future, and so they overpay. The three went on to run billions of dollars on that insight at their own firm, LSV.
Where Momentum Traps go next
A Momentum Trap is a share at a fork in the road. The momentum says the market believes the story. The weak Quality Rank says the accounts don't yet. Which way it goes depends on whether the story turns into real numbers.
Up: the growth and profits come through. This is the outcome every Momentum Trap investor is hoping for, and sometimes it happens. If the company starts delivering, with sales growing, margins widening and losses turning into profits, the Quality Rank rises to meet the price. A rising, expensive share with a strong Quality Rank is a High Flyer, one of the winning Styles, and High Flyers made +8.8% a year. Some of the market's greatest growth stocks started out as stories before the numbers caught up.
Down: the momentum runs out first. More often, sentiment turns before the profits arrive. A Momentum Trap that loses its momentum has nothing left: it becomes a Sucker Stock, the worst Style in the market at -9.0% a year. That is the path ITM Power took.
The difference between the two outcomes is the business, not the share price. So the thing to watch in a Momentum Trap is the Quality Rank, not the momentum.
Dodging a Momentum Trap
Every StockReport shows the StockRank Style at the top, and the Stock Screener can filter Momentum Traps out of any momentum screen. A few rules help:
Don't buy the story alone. Never buy a share with fewer than two strong factors. A Momentum Trap has one.
Wait for the numbers. If the story is real, it will show up in the results, the Quality Rank will rise, and the share will usually be reclassified as a High Flyer. Buying then means paying a little more for a lot more evidence. Momentum traders like Mark Minervini insist on the same thing: our guide to Breakout Momentum explains how to check that rising earnings are backing a rising price.
If you already own one, watch the quality and the momentum. Rising quality is the sign the story is coming true. Fading momentum with no quality behind it is the route to Sucker Stock, and the moment to get out.
Mind the costs. Momentum Traps are often small, volatile and expensive to trade, which is how a +1.2% gross return became -3.3% after dealing costs.
As Montier puts it:
Focusing on the cold hard facts (soundly based in real numbers) is likely to be the best defence against the siren song of stories.