In the aftermath of England's early exit from the 2015 Rugby World Cup came an intriguing but sadly familiar tale of misadventure in the stock market. During the tournament preparations, it was alleged that the team's kit manager had shared a tip about the "exciting prospects" of a micro-cap oil explorer, LGO Energy. Some players were apparently persuaded to put tens of thousands of pounds into the shares. Like the team's performance on the pitch, there were high hopes. And like the team's performance on the pitch, they weren't met.
It was a classic case of story over substance. The share wasn't cheap, the business was weak and the price was already falling. What it did have was vocal supporters, ready to talk up its prospects to anyone who would listen. In the StockRank Styles, Stockopedia's classification of every share in the market, this is a Sucker Stock: the worst place in the market to put your money, and somehow one of the most popular.
What is a Sucker Stock?
A Sucker Stock is not good, not cheap and not improving. It has none of the three factors that drive returns. In StockRank terms:
Not good means a weak Quality Rank. These are often blue-sky or pre-revenue businesses with negative returns on capital, little or no free cash flow, and a habit of issuing new shares to keep going. Many flag red on bankruptcy risk or earnings manipulation risk.
Not cheap means a weak Value Rank. With no earnings to measure, the valuation shows up on ratios like price to sales and price to book, and it is often stretched.
Not improving means a weak Momentum Rank. The share price is weak against the market, the company may have missed expectations, and any analysts who still cover it are cutting their forecasts.
A share is a Sucker Stock when its Quality, Value and Momentum ranks are all below 50, the bottom half of the market.

Why we fall for them
On paper, nobody should want a Sucker Stock. In practice, they are some of the most widely held and hotly discussed shares in the market. The reason is the story.
Unlike a Value Trap, which has at least been marked down, a Sucker Stock usually stays expensive, because its story keeps attracting buyers. Many are small and get little attention from analysts, so the weak numbers and stretched valuation are easy to miss. That leaves a vacuum, and bulletin board rumour rushes in to fill it.
Whenever we publish lists of Sucker Stocks, loyal shareholders come out in waves to explain why theirs shouldn't be on it. The usual suspects are:
Valuing the company on historic numbers is irrelevant, because it's all about the future.
The technology, once fully commercialised, will revolutionise an industry.
There's a transformative event coming, like a drilling result or a regulatory approval.
Our numbers are just plain wrong.
Nearly every Sucker Stock has a story that will, apparently, lead it to redemption. Like lottery tickets, a few will pay off. But almost every holder believes theirs is the one, and they can't all be right. When Ed Croft tracked the 100 most discussed shares on the UK's biggest bulletin boards, they consistently underperformed: the wisdom of the crowd turned out to be anything but. Perhaps we should take a lesson from Odysseus, and block our ears with wax against the siren song of story stocks.
At our webinar Four kinds of share lose money. Do you own one?, we asked investors which sentence sounded most like a share they had lost money on. Only 6% chose the Sucker Stock's "Long shot, but it will disrupt everything", the fewest of any answer. Perhaps it's the hardest one to admit to.
Case study: Purplebricks
Purplebricks was the story stock of 2017. The online estate agent was going to disrupt the high street, and the shares rose through that year and into 2018. All the way up, through the 475p peak, its StockRank Style was Momentum Trap: strong price momentum, but weak quality and weak value. Then the momentum went too.
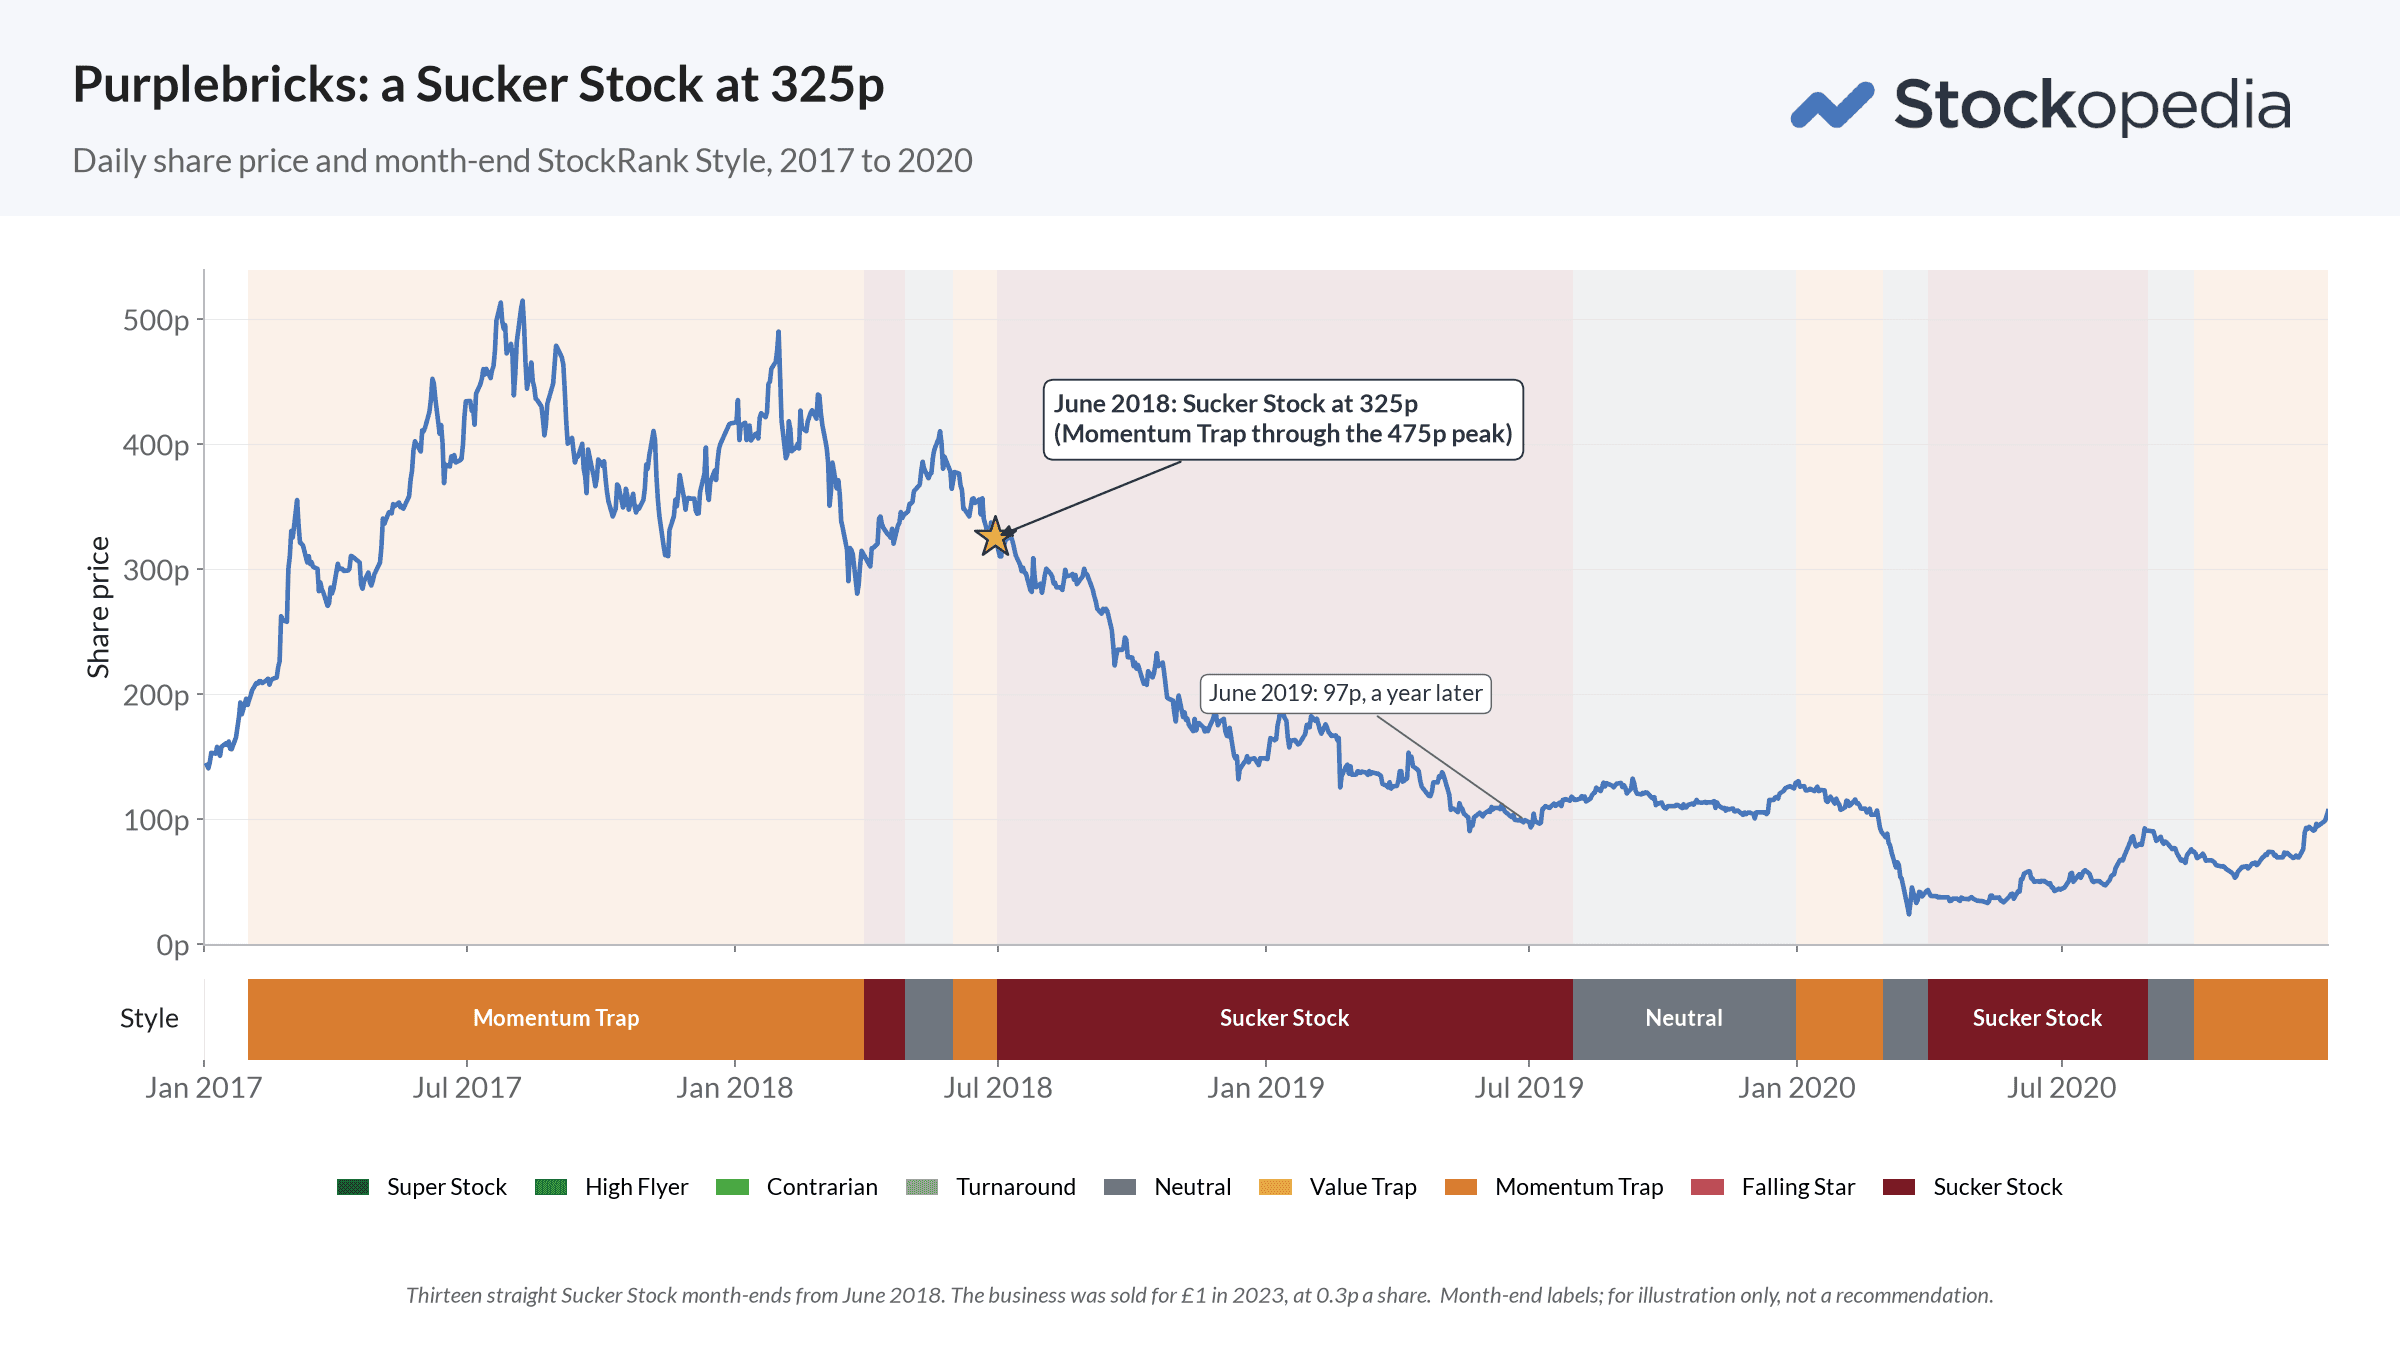
At the June 2018 month-end, with the shares at 325p, Purplebricks was reclassified as a Sucker Stock, and it stayed one for thirteen straight month-ends. A year later the shares were 97p. It passed through other Styles on the way down, briefly a High Flyer in the 2021 rally and a Value Trap at the end, but the direction never changed. In 2023 the business was sold for £1, at 0.3p a share.
Every one of the defences above could have been made for Purplebricks at the time. The historic numbers didn't matter because the model was new. The technology would change an industry. Our numbers were wrong. The label did not argue back. It simply said the share had no strong factors, and the odds that go with that.
What Sucker Stocks paid
Purplebricks was not unlucky. It was typical. Here is what each of the nine StockRank Styles returned when every UK share was sorted by its Style and held for a year at a time.
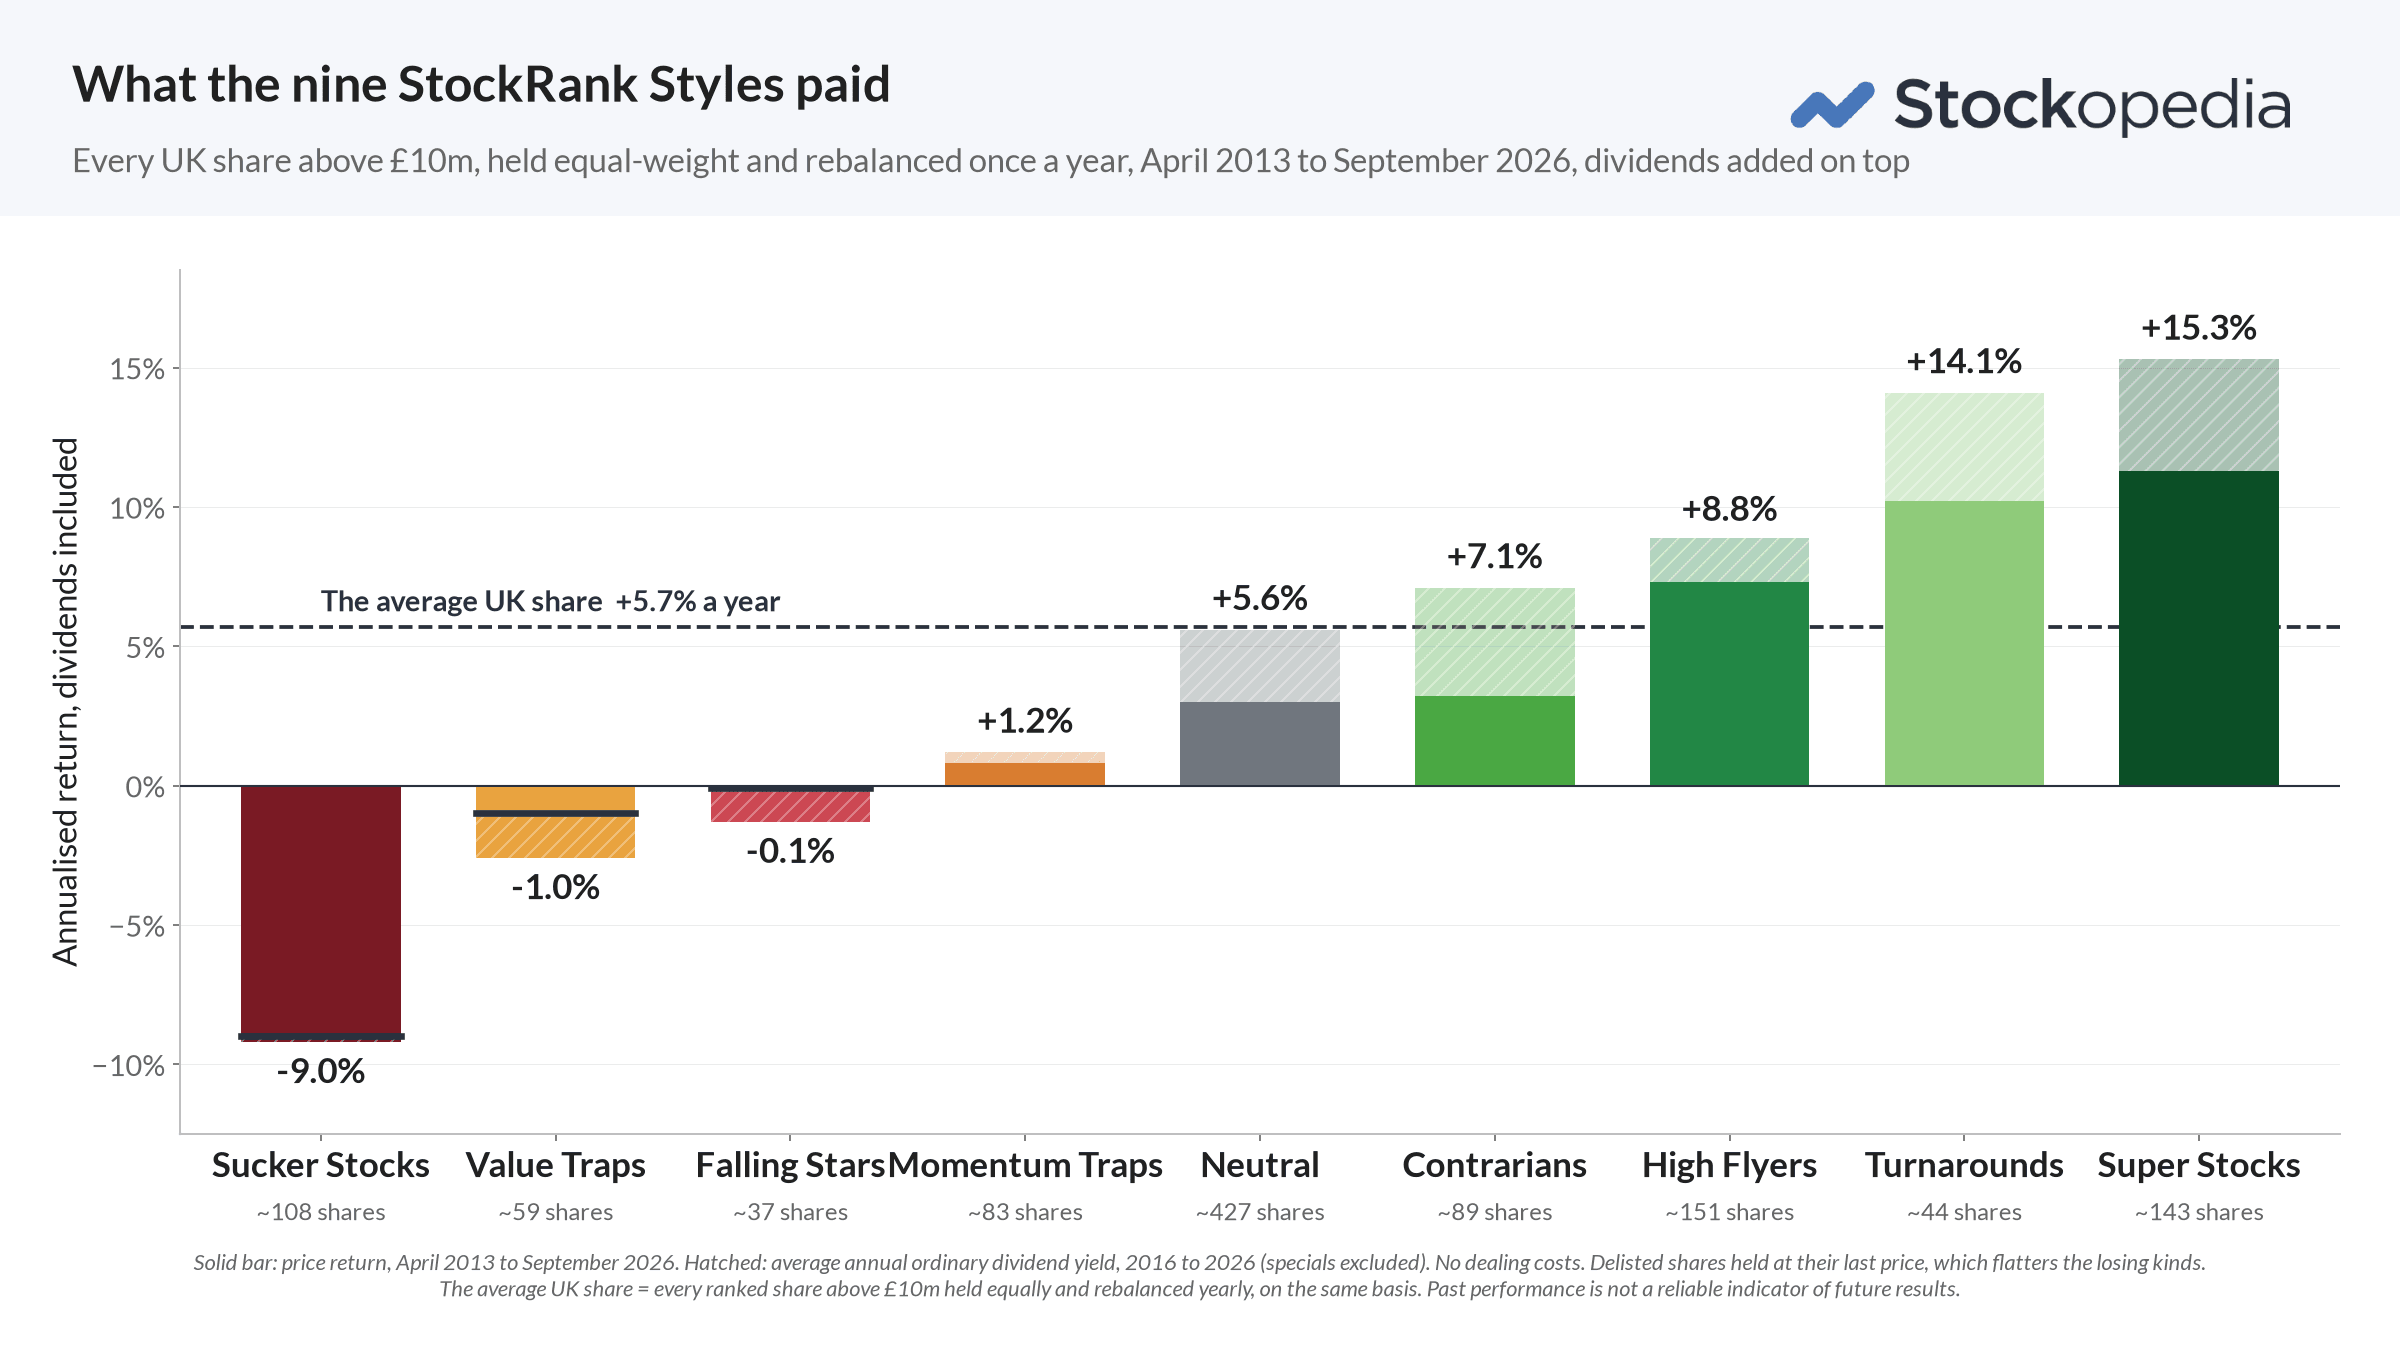
UK shares above £10m, held equal-weight and rebalanced once a year, April 2013 to September 2026, price return plus the average ordinary dividend yield measured 2016 to 2026, no dealing costs. Past performance is not a reliable indicator of future results.
Sucker Stocks are the worst Style on the chart by a distance. The bucket, about 108 shares at any one time and the biggest of the four losing Styles, lost 9.0% a year. £100 invested in 2013 became £28 by 2026 before dividends, and dividends barely registered: a 0.2% yield, against 4.0% for Super Stocks. Expensive, low-quality companies on a falling price don't pay their shareholders; more often they ask them for more money. And that result holds delisted shares at their last price, which flatters the losing Styles. The two words that separate +15.3% from -9.0% are Super and Sucker.
Risk makes it worse. Highly Speculative Sucker Stocks lost 15.5% a year, against +17.8% for Speculative Super Stocks at the other extreme. As Ed Croft puts it, taking risk when the fundamentals are against you is the most expensive thing you can do in investing.
Nor is it a UK quirk. Across roughly 10,000 global shares from 2016 to 2026, Sucker Stocks lost 6.8% a year with dividends reinvested, while the average global share made +8.5%. Of the four losing Styles, this is the one whose result replicates worldwide.
Robert Haugen's "Stupid Stocks"
Academics spotted this profile long ago. The late Robert Haugen, in his book The Inefficient Stock Market[1], found that the best-performing shares looked like growth at a reasonable price: cheap, low-volatility shares with strong growth. At the other end were the shares he called Stupid Stocks:
Relatively small, and illiquid, risky, financially shaky, negative momentum, unprofitable now and getting worse, yet selling at high prices relative to current sales, cash flow, and earnings
The link between that profile and poor returns is strong enough that some professionals use it to find shares to short. James Montier, then Global Strategist at Societe Generale, built an "Unholy Trinity" screen for exactly this: a high price to sales ratio (expensive), a low Piotroski F-Score (deteriorating health) and high asset growth (poor capital discipline). Between 1985 and 2007, a portfolio of such European shares rebalanced annually would have lost over 6% a year while the market rose 13% a year. Stockopedia's own tracking of the Unholy Trinity screen has seen very poor performance too, as it should. At the other end of Haugen's scale sit his Super Stocks, the shares our Core QVM strategy sets out to find.
Avoiding Sucker Stocks
Every StockReport shows the StockRank Style at the top, and the Stock Screener can filter out Sucker Stocks in one step. A few rules help:
Never buy a share with fewer than two strong factors. A Sucker Stock has none, so two of its three factors would have to turn before it became a winning Style.
Check what you already own. It's easy to end up holding a Sucker Stock or two, usually bought on a story. Keep them to an absolute minimum.
Treat tips with great caution, especially ones that arrive with an exciting story and no numbers.
Don't add risk to bad fundamentals. Highly Speculative Sucker Stocks were the worst corner of the whole market.
Warren Buffett once put it this way in a letter to Berkshire Hathaway shareholders:
If you aren't certain that you understand and can value your business far better than Mr. Market, you don't belong in the game. As they say in poker, 'If you've been in the game 30 minutes and you don't know who the patsy is, you're the patsy'.
For investors and rugby players alike, the prospect of quick riches from speculative story stocks is likely to end in tears, or at least an early bath.