When Warren Buffett raised his stake in Tesco in 2012, little did he know that he was breaking one of his own investment rules. He’d initially taken a position in the UK retail giant some years earlier. After a profit warning and news of increasingly fierce competition, Buffett chose to buy more shares as price started to slide. It was an error that eventually forced him to take a £287m loss on what had turned out to be a classic Value Trap.
With Tesco, Buffett showed that Value Traps can open up in front of even the smartest investors. Yet these disappointments are a particular risk for investors looking for a bargain. The bargain hunter’s favoured territory is the deepest, darkest corner of the market. It’s here that unloved, broken and misunderstood companies languish. In amongst them lie the Turnarounds and Contrarians that can deliver stellar returns if they rehabilitate. But also lurking are the value traps - stricken stocks that may either never bounce back or make you bear too much opportunity cost to make it worth the wait.
Value Traps come with a familiar refrain: "It's far, far too cheap." When we asked investors at our webinar Four kinds of share lose money. Do you own one? which sentence sounded most like a share they had lost money on, 19% said a Value Trap.
What is a Value Trap?
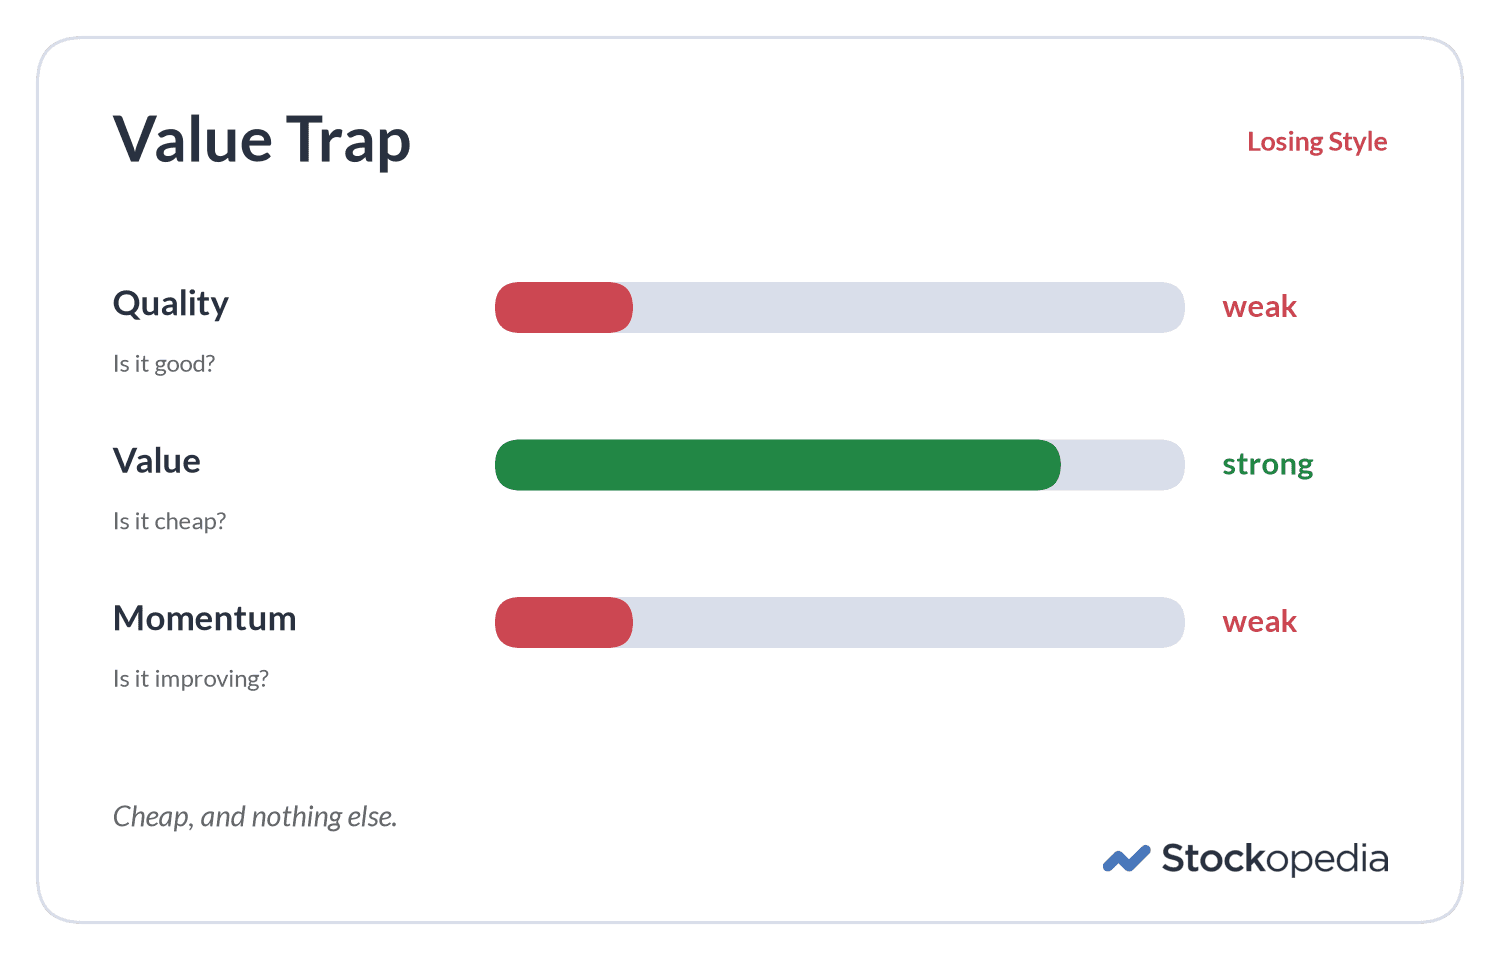
A Value Trap is cheap, and nothing else. In StockRank terms:
Cheap means a high Value Rank. The share trades on a low multiple of its earnings, cash flow, assets or sales.
Not good means a weak Quality Rank. Returns on capital and margins are low, profits are patchy or falling, and the balance sheet may be stretched.
Not improving means a weak Momentum Rank. The share price is weak relative to the market, and analysts are more likely to be cutting their forecasts than raising them.
A share is a Value Trap when its Value Rank is above 50, the top half of the market, and its Quality and Momentum ranks are both below. It has one strong factor out of three, which makes it one of the four losing StockRank Styles.
Deep value - the domain of the value trap
‘Deep value’ is an investing approach that was born in the writing of Benjamin Graham. Chastened by the losses of the 1929 stock market crash, Graham hatched a completely new brand of security analysis. He shunned the expensive ‘glamour’ stocks of the day in favour of unpopular shares that sold below their 'intrinsic value'. Importantly, he insisted that these potential dogs were priced so cheaply that there was a healthy ‘margin of safety’ in the price. With a well diversified portfolio, he reasoned that he could absorb a number of inevitable losers but ride out profitably on a wave of winners.
Graham’s value strategies have earned him a great deal of respect, and deep value still works for investors who do it with discipline. Our Ultimate Guide to Deep Value Investing covers the methods, from Graham’s net-nets to Tobias Carlisle’s Acquirer’s Multiple, and why bargain prices tend to revert towards fair value. But one of the risks of the approach is becoming overexposed to stocks that are risky and perhaps on the brink of bankruptcy, and that is where Value Traps live.
Seth Klarman is one of the best known modern day investors to have modelled an approach on Ben Graham’s ethos. He’s become a billionaire through his stewardship of Baupost Group and even wrote a book called Margin of Safety: Risk-Averse Value Investing Strategies for the Thoughtful Investor.
In his 2012 letter to investors, Klarman pinpointed the subtle risk of falling into a Value Trap. He wrote that a bargain price is necessary but not sufficient for making an investment because sometimes securities that are superficially cheap turn out not to be:
‘Value traps’ are cheap for a reason - perhaps an inept and entrenched management, a poor history of capital allocation, or assets whose value is in inexorable decline.
These hallmarks and others have long been the driver of academic and industry endeavour to find a way of weeding out Value Traps. Professors and professionals alike have looked for ways of stacking the odds in favour of finding value shares that are more likely to recover.
Joseph Piotroski, an American finance academic, did just this in 2000 with the development of his F-Score of corporate financial health. Crucially, the impetus for his work was a finding that less than 44% of a basket of the cheapest stocks in the market go on to deliver a positive return over the next two years. Essentially, Piotroski was saying that if you’re blindly picking stocks at the cheapest end of the market, your chance of picking one that will recover is well below 50/50.
What Value Traps paid
The StockRank Styles let us measure this corner of the market rather than argue about it. We sorted every UK share by its Style and held each Style for a year at a time, from April 2013 to September 2026. The chart of all nine StockRank Styles is in the series overview; the Value Trap line reads like this.
The Value Trap bucket, about 59 shares at any one time, lost 1.0% a year once dividends are counted, against +5.7% a year for the average UK share. Before dividends it was worse. The price return was -2.6% a year, which turned £100 into £70 over the period. A 1.6% dividend yield softened the blow but did not repair it. Only Sucker Stocks did worse.
UK shares above £10m, held equal-weight and rebalanced once a year, April 2013 to September 2026, price return plus the average ordinary dividend yield measured 2016 to 2026, no dealing costs. Past performance is not a reliable indicator of future results.
The gap to Turnarounds is the lesson. A Turnaround has the same cheap price with the Momentum rank switched on, and it made +14.1% a year. Losing momentum cost about 15 percentage points a year in that column of the grid.
One honesty note. Worldwide the picture is softer. Across roughly 10,000 global shares from 2016 to 2026, Value Traps returned +7.9% a year with dividends reinvested, a little below the +8.5% for the average global share and nowhere near a loss. The finding that all four losing Styles lose money is a UK finding. What replicates everywhere is the extremes: Super Stocks and Turnarounds at the top, Sucker Stocks at the bottom. So treat a Value Trap classification as a warning that the odds are poor, not a prediction that the share will fall.
Two Value Traps, start to finish
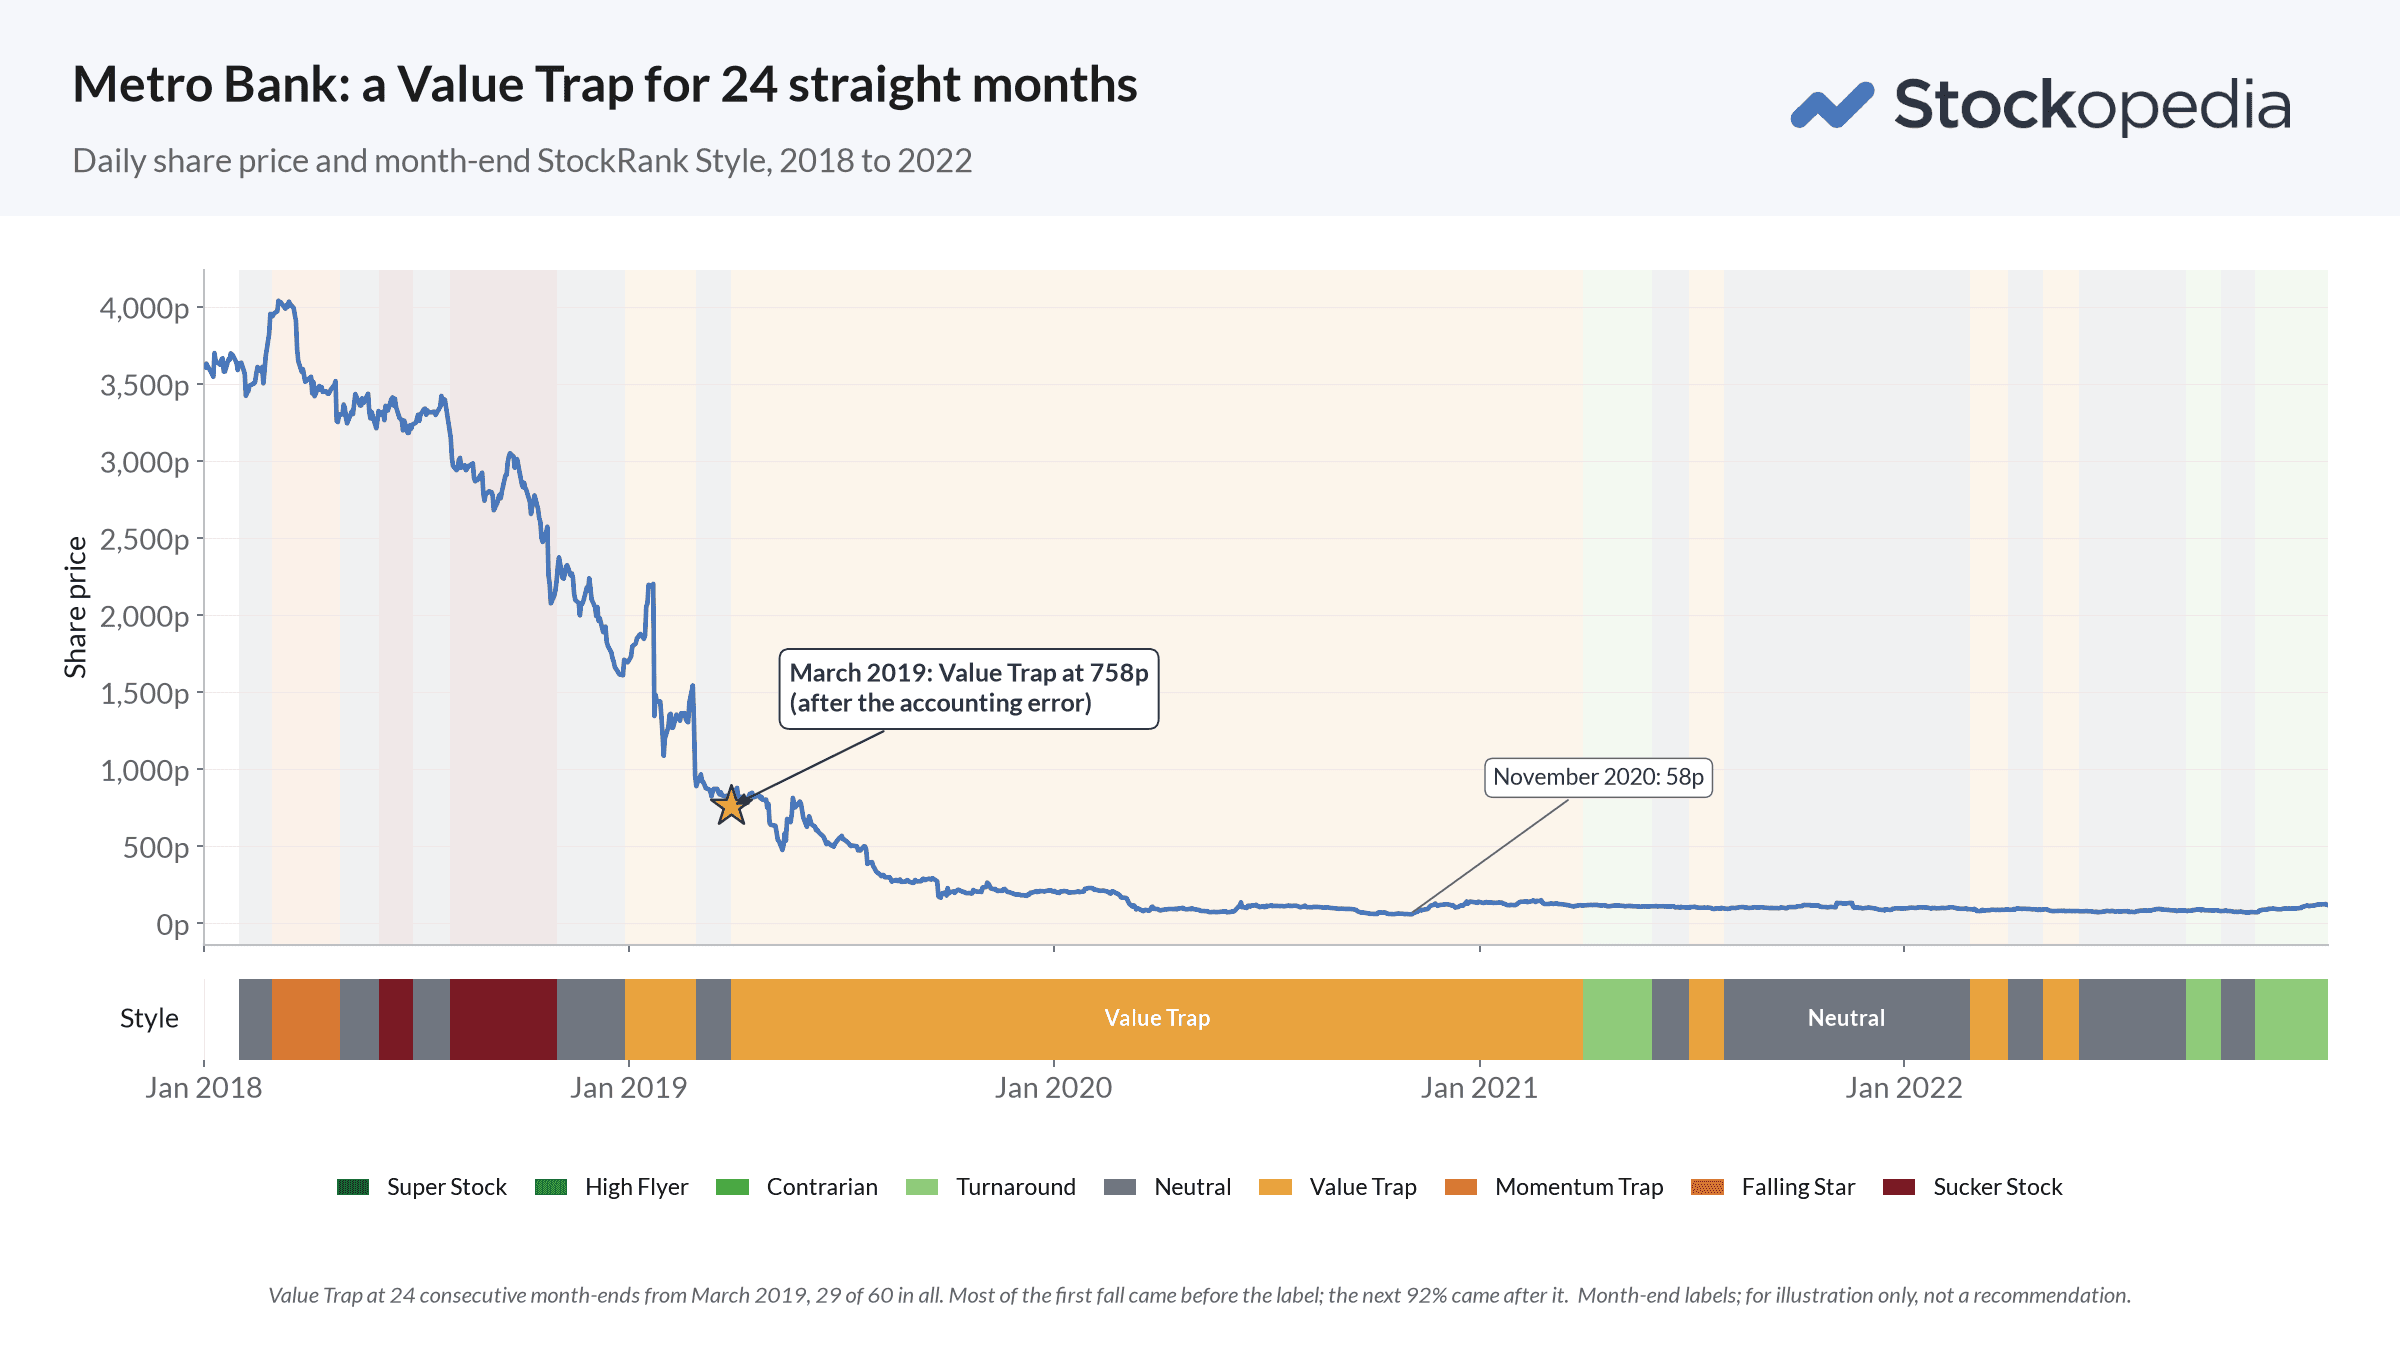
Finished stories show the Style at work better than any table. Metro Bank first. The challenger bank was a stock market favourite, a Momentum Trap in early 2018 while the shares were still riding high. Then came the accounting error, and the price collapsed. By the time the StockRank Style turned to Value Trap at the March 2019 month-end, the shares were 758p and most of that first fall had already happened. On every value measure the bank now looked cheap. It kept looking cheap. Metro Bank stayed a Value Trap for 24 consecutive month-ends, and by November 2020 the shares were 58p, a further 92% fall after the reclassification. Across 2018 to 2022 it sat in the Value Trap box at 29 of 60 month-ends. The cheapness was real. So was the reason for it.
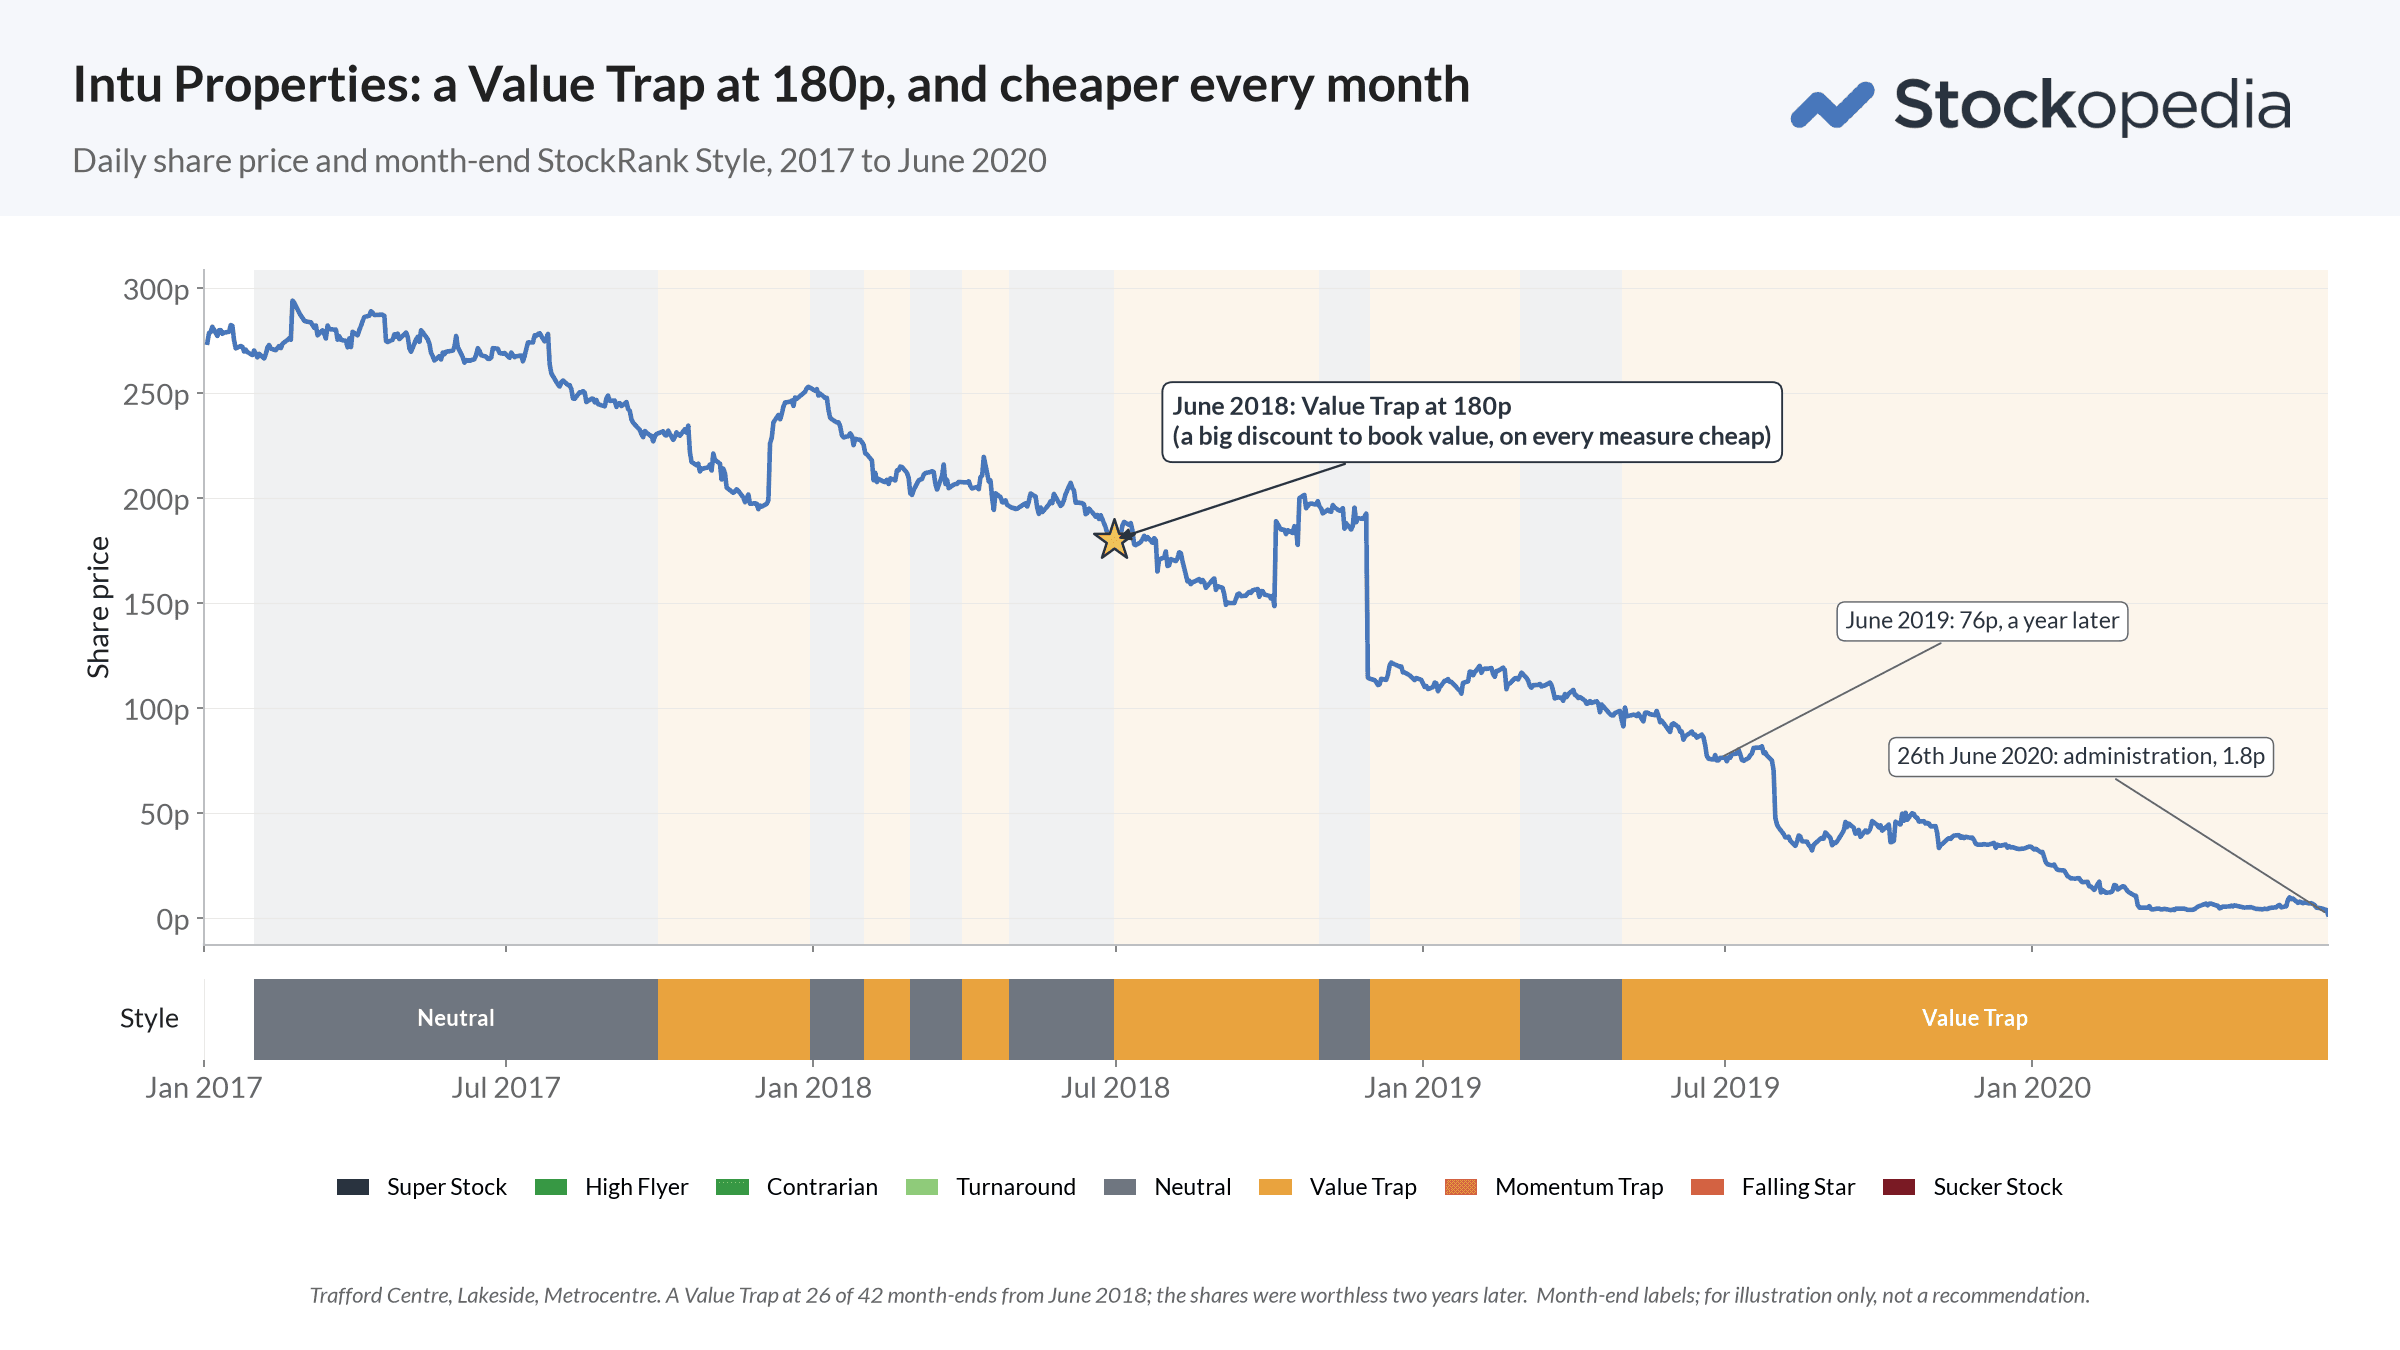
Intu Properties is the second. It owned the Trafford Centre, Lakeside and the Metrocentre, and in June 2018 it became a Value Trap at 180p: a big discount to book value, cheap on every measure, with weak Quality and Momentum ranks. A year later the shares were 76p and the Style was still Value Trap. It was a Value Trap at 26 of 42 month-ends from June 2018. On 26th June 2020 the company went into administration with the shares at 1.8p. Cheap is a price, not a reason.
How to step over a Value Trap
Of course not all deep value stocks are going to end in business failure. But statistically, this is one of the most dangerous places to be in the market - the domain of broken business models and sectors in cyclical or secular decline. Some companies will fail, while many others will simply languish for prolonged periods. The key lesson is to give loss making, out of favour, cheap shares a wide berth unless they start to show confirming factors. The two most powerful indicators of recovery are Momentum and Quality. Every StockReport shows both ranks alongside its Style, and the Stock Screener can filter Value Traps out of any value screen.
Improving share price momentum has earned a reputation as the first sign of a recovery in risky value shares. Josef Lakonishok spent decades researching and then putting into practice a strategy of using Relative Price Strength as a signal that a bargain stock was on the mend. Similarly, Joseph Piotroski’s F-Score of fundamental momentum specifically looks for an improving financial health trend.
When it comes to quality, one of the most famous Quality + Value approaches is Joel Greenblatt’s Magic Formula. Ranking the market using two metrics: Earnings Yield and Return on Capital offers a way of finding cheap stocks with strong operational efficiency and profitability (see the Magic Formula screen here). Even Buffett offers a lesson on introducing quality to a value strategy by using ROE, ROCE and margins, and examining the consistency of the financial history.
Don’t make the same mistakes as Buffett
Warren Buffett spent a good part of his 1989 letter to Berkshire Hathaway shareholders reflecting on his past investing mistakes. His message carried a warning against the folly of excessive bargain hunting - something he called the ‘cigar butt’ approach to investing:
A cigar butt found on the street that has only one puff left in it may not offer much of a smoke, but the “bargain purchase” will make that puff all profit. Unless you are a liquidator, that kind of approach to buying businesses is foolish. First, the original “bargain” price probably will not turn out to be such a steal after all… Second, any initial advantage you secure will be quickly eroded by the low return that the business earns.
Twenty-five years later, he was owning up to his mistakes again - this time with Tesco. While it may not be a classic cigar-butt share, it is another example of how an apparently cheap stock can be a distraction from the signs that a business is facing challenges on many fronts.
Everyone loves a bargain, but the lesson here is that too much focus on buying ‘cheap’ without a consideration of company quality can risk underperformance. At best it can lead to the prolonged agony of waiting for value to ‘out’ - if it ever does. The StockRank Styles turn that lesson into a rule. In Ed Croft’s words: never buy a share with fewer than two strong factors. A Value Trap has one. Switch on a strong Momentum rank and it becomes a Turnaround; switch on a strong Quality rank and it becomes a Contrarian. Those are the classes of value share worth hunting in, and the articles on each show how to find them.