#1 - City of London Investment Group - right place, right time

This is #1 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
City of London Investment (LON:CLIG) is a specialist asset manager with a focus on emerging markets, fixed income and closed-end funds. The rampant outperformance of the Mag 7 and US market have made life tough in recent years, but CLIG’s strategies have performed notably over the last 12 months. A strong cash balance sheet and near-9% yield help to limit the downside, while a StockRank of 96 hints at the potential for a re-rating if CLIG can achieve a return to reliable net inflows.
The Big Picture
CLIG has a long pedigree as a founder-led business. While the company’s original founder retired a few years ago, a merger with a similar-sized US firm meant that a new owner, George Karpus, took over the top rung of the shareholder register with a 30%+ holding. Karpus has been vocal in calling for improvements and there’s evidence these efforts have started to bear fruit. At the same time, market conditions have become more favourable over the last year as CLIG’s core emerging markets universe has performed more strongly.
Why now? Active asset managers have struggled against the passive onslaught and outperformance of the S&P 500. But conditions may be changing. The S&P has lagged the FTSE 100 over the last 12 months, while CLIG’s flagship equity strategies delivered gains of more than 20% during the year to 30 June 2025.
Fresh leadership: long-serving CEO Tom Griffith left recently. Pressure from Mr Karpus is likely to help ensure his replacement has a sharper focus on operational excellence and marketing delivery.
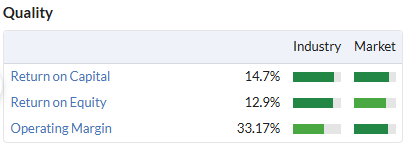
Why CLIG: there are other asset managers out there with attractive metrics. But few of them have CLIG’s combination of 30%+ operating margins, balance sheet strength, founder alignment. Very few also have a dividend that’s not been cut for 20 years and offers a near-9% yield.
Going Deeper
CLIG’s profitability and shareholder-friendly dividend are not in question.
What is still unproven is the company’s ability to achieve a return to sustainable net inflows. The last year has seen improved investment performance from CLIG’s assets, suggesting its niche strategy of seeking value in closed-end funds can still deliver the goods. Investors now need to watch for the other pieces of the jigsaw to fall into place.
Look for inflows: CLIG saw net outflows of almost $1bn last year, from starting assets under management of $10.2bn. Total AUM still ended the year higher, at $10.8bn, thanks to $1.5bn of market and investment gains. The challenge for the company is to use this success to help attract additional inflows into its strategies.
Why this matters: asset managers generate fee income as a percentage of AUM. When AUM rises, fee income rises even though operating costs remain largely unchanged. This means that much of the extra revenue drops straight down to profits. CLIG’s 33% operating margin means that the combination of net inflows and positive market performance has the potential to deliver a very rapid rise in profits.
Early signs are promising: AUM rose by 4% to $11.2bn in Q1 FY26 (Jul-Sept 25), while the majority of the company’s strategies outperformed their benchmarks.
What The Brokers Say
Broker coverage is limited, but analysts at Zeus who do follow the stock have maintained consistent estimates since March. In their latest note they described their forecasts as “prudent” with “scope to increase revenue and profits” if net inflows improve.
Target price: CLIG shares are trading close to Zeus’s target price of 365p. With little good news priced in, any upgrade to forecasts could trigger an immediate re-rating.
9% dividend yield: existing forecasts show continued cover for the dividend, suggesting a near-9% dividend yield. Unless new problems emerge, this high and cash-backed yield should help to underpin the current share price.
The Bear Case
CLIG’s share price first reached current levels about 15 years ago. There have been false dawns before and the company’s ability to deliver fresh growth is not certain:
A perma-decline: the company’s niche focus on closed-end funds means it’s exposed to a sector of the market that’s struggling to find new capital and is at risk of cannibalisation from more popular low-cost structures such as ETFs. There’s a risk CLIG’s fortunes are tied to a declining sector of the investment market.
Leadership uncertainty: the company’s previous CEO left quite suddenly and hasn’t been replaced in nearly six months. While new leadership should be positive, there may be a growing risk of a damaging leadership vacuum.
Shareholders vs employees: a.k.a. where are the shareholders’ yachts? The asset management sector has a reputation for richly rewarding its employees, even when clients and shareholders only get average results. CLIG is a somewhat collegiate business which also gives out this vibe, at times.
The Bottom Line
CLIG has visibly responded to shareholder criticism while its main strategies have delivered strong investment returns over the last year. On a broader view, there are signs of green shoots appearing across the investment sector. Our analysis in the DSMR and elsewhere in 2025 has also regularly highlighted the value available among listed asset managers.
High quality financials and founder-shareholder alignment have the potential to support an appealing turnaround and income investment at CLIG. While there are no guarantees, this business could be worth significantly more in the future, if management can secure a step-change in AUM.
Disclosure: Roland owned shares in City of London Investment Group at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Outflows are still very large here so would want to see these stabilise before getting involved. The performance of their funds is actually pretty good so not entirely sure what is driving these outflows and what could trigger a reversal. I guess a shift towards value and away from passives would help, but not sure their funds are sufficiently distinctive to stand out from the crowd.
One other thing to note on leadership is Karpus is now 80 years old. It's unclear what he plans to do with his large shareholding or whether he may distance himself from the company's operations.
I read did somewhere that his investments are in a trust dedicated to philanthropy
If you have a source for that it would be most helpful to read.
w.google.com/search?q=george+karpus&rlz=1C1CHBF
see you tube towards the end his plan is revealed
Long time suffering holder. I admire how Karpus has tried to 'shake the tree' to liven up the board strategy since his retirement in 2023. Regrettably the board have been rather cloth eared with the exception of improving cash management strategies. The company culture regarding sales and marketing has been pretty dire with new business gains being almost non existent.
A new CEO with passion and drive is badly needed. In the absence of this I can only see more of the same.
There was considerable shareholder resentment when Karpus took over CLIG. It looks to me as if the market is still bearing the weight of this ill-feeling.
I was a holder of CLIG at the time of the Karpus deal and I have increased my holding since. I would not characterise the transaction in any way as a takeover. I think that it was very much a merger and that it has been a success. Whilst I am sure that not everyone was happy - I have not been aware of any ill-feeling and I have regularly attended Board meetings.
I agree with the comments about needing to sort out a first rate new CEO (the company has said that it is making good progress, so I hope that we soon have news on that front). Stemming outflows is clearly an issue, as it is for all fund managers - e.g. Polar Capital, who I consider very similar to CLIG in many ways, albeit bigger.
Thanks for sharing, as long term holder I think shake up is good, complacency needs to routed out. I do think many older investors like me are looking reliable dividends, as such a big market niche to be enticed