2 high-return stocks from my Buffett screen

To follow up on my Warren Buffett-style stock screen from last week, I thought it would be interesting to take a look at some of the companies that appeared in the screen results.
The two stocks I’ve chosen have some characteristics in common, but they’re both also quite distinctive businesses. I think it’s possible that if Buffett was a UK small/mid-cap investor, he might be interested in both of them.
As always, the shares I’m going to discuss are only ideas for further research, not stock recommendations.
You can see (and duplicate) my Warren Buffett screen here.
Note: As I mentioned in last week’s piece, the construction of the screen effectively excludes banks. US banking stocks form a sizable part of Buffett’s own portfolio. I think that some UK banking shares also look attractive for long-term investors at the moment – this is a subject I hope to revisit in the coming weeks.
James Latham (LON:LTHM)
What it does: James Latham (LON:LTHM) is one of the UK’s leading distributors of timber, panels and decorative surfaces. It’s a family-run business that’s been importing timber into the UK since 1757.
Ownership remains heavily concentrated in family hands. Two members of the current board are Latham family members, including chairman Nick Latham:

Does Buffett own anything similar? Based on Berkshire Hathaway’s reported equity holdings on 30 September 2022, Buffett has substantial equity holdings in at least two US building materials businesses, Floor & Decor Holdings (NYQ:FND) and Louisiana-Pacific (NYQ:LPX).
Stock Review: James Latham is an AIM-listed small-cap, with a market cap of £266m. However, the company has a long record of excellent financial performance. This has been reflected in excellent shareholder returns over time – the stock has 16-bagged over the last 20 years:

Lathams also did very well during the pandemic, benefiting from surging demand for home improvement and building materials.
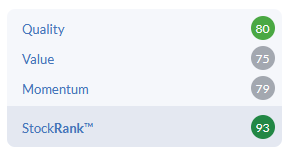
The shares qualify for eight guru screens at the time of writing. They’re also well-regarded by Stockopedia’s algorithms, with Super Stock status and a high StockRank:
Profits are expected to fall this year but still remain double those reported in FY21:

Based on this positive earnings outlook, the shares look quite reasonably valued to me, on nine times forecast earnings:

Although the dividend yield is low, this reflects a conservative payout ratio that leaves the company with ample retained earnings. These have historically been reinvested by the company to support long-term growth – a classic Buffett trait:

Another factor that Buffett might like is Latham’s consistently above-average return on capital employed:

This is backed by an asset-rich balance sheet with plenty of net cash:


What could go wrong? Latham’s products are used in housing and commercial projects, so sales could come under pressure during a broad construction downturn. The business also has exposure to energy costs and raw material prices.
Although Latham’s has a strong market share, its products are somewhat commoditised and it does face some competition from rival distributors offering very similar products. This means profit margins could potentially come under pressure, at some point.
A major warehouse fire or other adverse event might also impact trading for a significant period, although I would imagine the majority of losses would be insured.
My view: I think Latham’s is a great example of the kind of quality small-cap that’s available on the UK market. It’s a stock I’d be happy to own. My only near-term concern is that if the economic outlook worsens, I think there’s a chance that current forecasts might be downgraded. That could leave the stock looking fully priced.
Latham’s most recent outlook statement (1 Dec ‘22) appeared to include a warning of this possibility (my bold):
There are a few market sectors, such as the merchant sector, that are quieter at the moment, but many of our other customers have steady order books and remain busy, but are clearly nervous looking at the macroeconomic conditions next year.
Nonetheless, I think this stock is likely to remain a rewarding long-term investment, from a Buffett perspective.
Computacenter (LON:CCC)
What it does: Founded in 1981, FTSE 250 firm Computacenter (LON:CCC) is an independent IT technology and services provider. It primarily serves large corporates and public sector clients. The group is a leading player in the UK market, but also operates in Europe and North America.
Founders Philip Hulme and Peter Ogden remain board members and significant shareholders:

Does Buffett own anything similar? Berkshire Hathaway is the largest shareholder of computer and printer manufacturer HP (NYQ:HPQ). Although HP is a branded equipment manufacturer in its own right, a lot of what it sells is fairly commoditised.
I think that much of the value in HP’s business is its ability to deliver and support complete solutions at scale for large customers. That’s also Computacenter’s key strength, but the UK firm covers a much broader range of services, extending from desktop to data centre.
Stock Review: Computacenter has been highly-ranked by Stockopedia’s algorithms pretty much since the StockRanks were introduced. But the stock has taken a rare dip recently, perhaps reflecting the shares retreat from their pandemic highs:
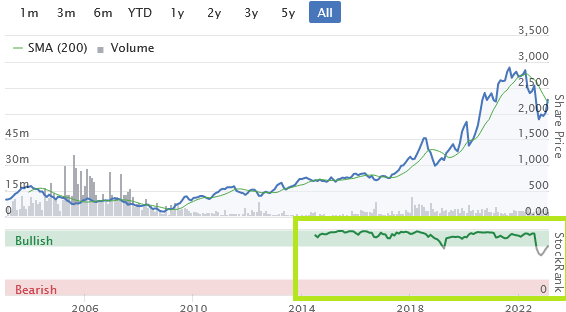
Notwithstanding this, the firm’s StockRank score does not suggest any obvious cause for alarm to me:


Computacenter shares have doubled since 2019 despite their recent slump. The stock is now worth six times more than it was 20 years ago, thanks to a very strong and consistent record of profit growth.
According to the company’s latest trading update, this year should be the “eighteenth consecutive year of underlying adjusted diluted earnings per share growth”. That’s an adjusted metric, but Stockopedia’s data suggests that for the last 10 years at least, unadjusted earnings have also risen fairly consistently:

Given this positive outlook, the stock’s current valuation doesn’t seem unreasonable to me:

As a large-scale reseller, Computacenter benefits from favourable credit terms with its major suppliers. Stock levels appear to be kept low and moved fast – the StockReport Efficiency graphic tells us that Computacenter turns its stock almost 15 times a year, or roughly every 24 days:

This helps the group to operate with relatively modest levels of working capital and maintain strong cash generation, providing good support for the dividend:

Average dividend cover is more than 2x, meaning that Computacenter typically retains at least 50% of its earnings each year for reinvestment.
Returns on capital have always been high, suggesting that the company has not struggled to find good quality growth opportunities. This also seems to suggest that periodic acquisitions have been reasonably price:

These long-term results suggest to me that Computacenter also benefits from excellent management. This is another of Buffett’s priorities, but one that’s sometimes harder to measure.
As it happens, chief executive Mike Norris is something of a legend in this industry. He started work at Computacenter as a salesman in 1984 and became chief executive in 1994, when the founders stepped back. This makes Norris the longest-serving CEO of any FTSE 350 company, according to this FT article (£).
Finance boss Tony Conophy has been in post since 1998, and has worked at the firm since 1987. Most of the other members of the group’s executive team are also long-serving staffers, albeit younger.
The combination of management stability and consistent success is attractive to me, although I wonder if it might create some succession risk, when Norris eventually retires.
What could go wrong? I can see a couple of potential risks here. In the immediate future, an economic slowdown in western markets might see companies pull back their IT spending after splurging during the pandemic. That wouldn’t concern me, but it might create a more attractive buying opportunity.
On a medium-term view, I wonder if the firm’s acquisition-led US expansion could lead to an erosion of its profitability, as it competes with larger and more established rivals. However, I don’t see any sign of this yet.
My view: Computacenter is without doubt one of the biggest missed opportunities on my long-term watch list. It’s a share I’ve repeatedly wanted to buy, but have been deterred by the price – or else I’ve been unable to take advantage of periodic dips.
I am still interested in adding the shares to my portfolio and may yet do so this year. Certainly, the current valuation does not seem unreasonable to me, with an earnings yield (EBIT/EV) of 9% – above the 8% threshold I use as a rule-of-thumb for good value.
Computacenter isn’t immune to macro risks, but I think this is a well-run and reasonably priced business. From a Buffett-like long-term perspective, I wouldn’t have any problem buying the shares today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Before that they had spun off Agilent. I worked for Agilent in the late 90s and still have my employee bonus shares.
Before that they had spun off Agilent. I worked for Agilent in the late 90s and still have my employee bonus shares.
I have an outsized holding. Expensive, but defensive, quality growth is never cheap.
Thanks for the article Roland. I think an additional reason why James Latham did well during the pandemic/logistics crisis was that its size and well-established purchasing and distribution network allowed it to maintain stocks when other companies were running out. I also think that wood engineering techniques (including techniques involving adhesives) are expanding its structural uses in buildings. My guess is that the sustainability of wood must also be creating a tailwind for the company where it competes with materials which need more energy input.
Like Rusty2 I have looked at Computacenter (LON:CCC) but was put off by the low margin. I did, however invest in Softcat (LON:SCT) when I noticed that K A-L's Buffettology fund had bought in. They are very similar companies in what they do. Both companies qualify for the 'Buffettology-esque Historical Growth Screen' so why not yours? The answer:
Softcat passes 9 out of 11 of this checklist's rules:
Like sharw, I am a follower of Keith Ashworth-Lord and those considering Computacenter might also like to have a look at Bytes Technology which is one of KAL's holdings. I am also attracted to Bytes because the NHS is a significant customer and I would expect increased sales here if the polls are right and Labour gets in at the next election.
I have looked at Computacenter (LON:CCC) in the past but was put off by the low margins, I din't usually invest in stocks that are under 5%.
I do have a small holding in James Latham (LON:LTHM) , never grow because of recession fears, I note timber prices have dropped back recently, which should help them.
Great report - Thanks Roland - I hold both these largely from monitoring them here. They both have sensible PE and pay a reasonable dividend. Agree anything could affect James Latham (LON:LTHM) but there is the added bonus that they are eligible for IHT relief.
Always considered buying James Latham (LON:LTHM) but never got round to it, but Computacenter (LON:CCC) I do hold and am happy with it.