4 stocks generating high returns at a reasonable price

One of my eureka moments as an investor was when I really began to understand profitability. Not just profit margins, but the concept of return on capital employed and how this supports the process of creating shareholder returns and sustainable growth.
In his recent multibagger webinar, Ed also highlighted return on capital employed as one of the key factors that’s normally required for long-term compounding. Alongside this, one other trait common to most of the big multibaggers in Stockopedia’s database was that they started out with quite reasonable valuations.
Ed explained both of these factors in detail in last week’s masterclass, “The Engines of Multibaggers”, which I’d strongly recommend.
Obviously, I have no objection to holding some multibaggers in my portfolio. But as a dividend growth investor, I also want my portfolio to contain a proportion of more mature companies that are able to pay out attractive levels of surplus cash as dividends.
For this reason, I aim to own a mix of companies split across the top two categories in this chart, which I’ve lifted from the masterclass slides:
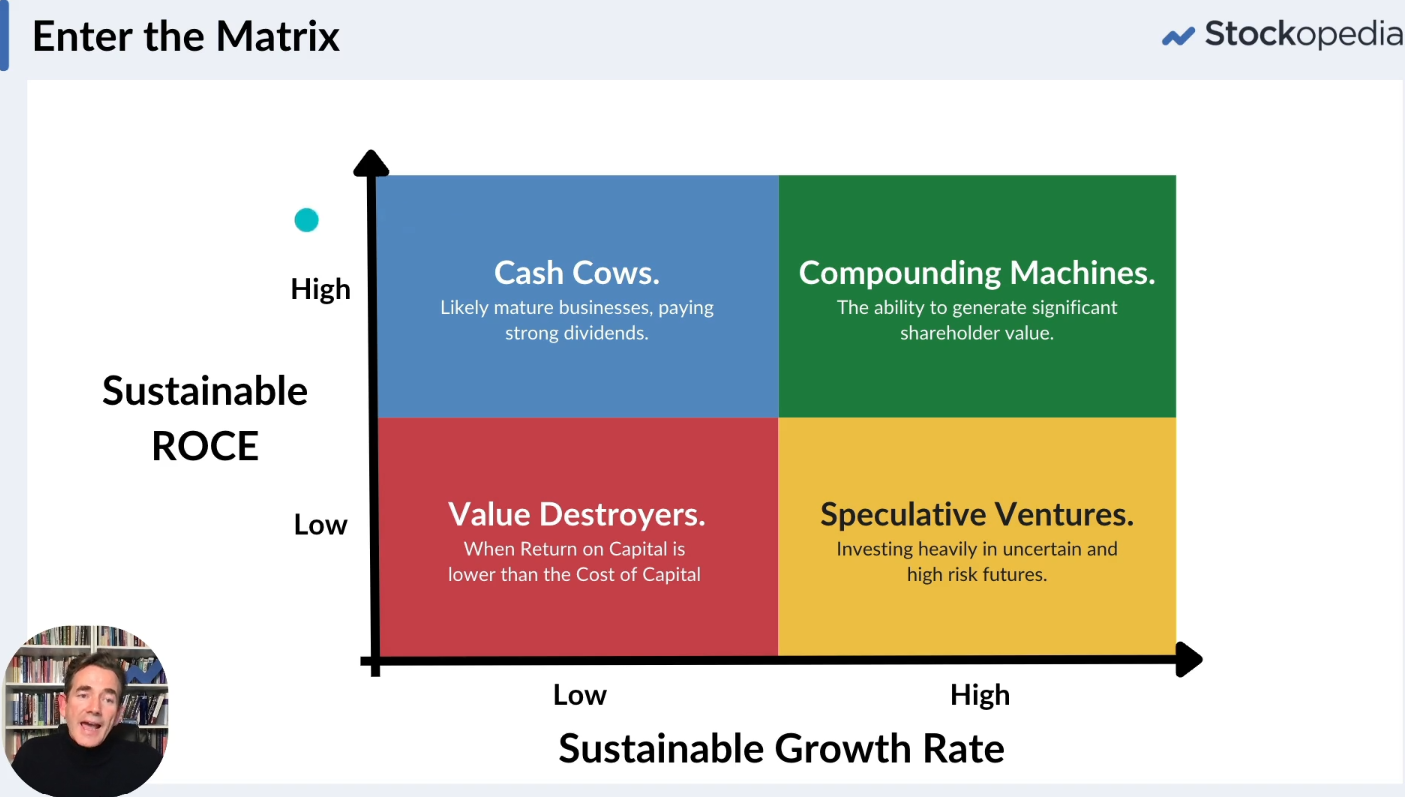
With this in mind, I thought it would be interesting to try building a simple screen to look for high-ROCE companies that might be either cash cows or compounding machines.
For the avoidance of doubt, I’m not suggesting all the firms in my screen results are potential multibaggers (although some might be). But in general, I think that investing in highly profitable and cash-generative businesses is likely to lead to an acceptable outcome for shareholders, even if they don’t multibag.
High returns at a reasonable price
I won’t spend too much time talking about the construction of this screen, as it’s fairly simple and I’ve discussed how I build screens many times before. Here’s a recent example.
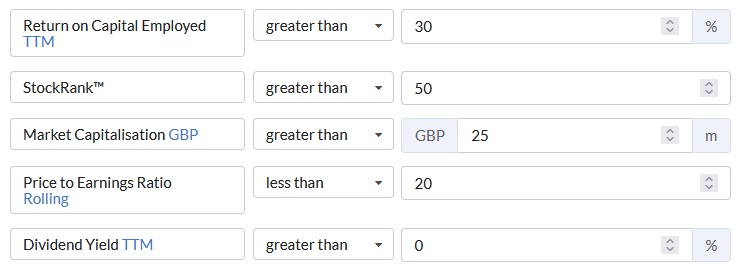
This is the screen I’ve created to try and find shares with high returns on capital employed and reasonable valuations:
You can see/copy my High Returns at a Reasonable Price screen here
The rules are quite simple and there are certainly plenty of ways this screen could be changed or perhaps refined. But as always, this is only intended to be a starting point for further investigation. I don’t want the criteria to be overly restrictive.
As it happens, my requirement for ROCE of over 30% and a P/E of less than 20 means that only 20 shares qualify for the screen at the time of writing:

In the remainder of this piece, I’m going to take a look at four shares I think look potentially interesting today. This isn’t exhaustive by any means – I’ve tried to choose a balance of different types of business to look at, rather than focusing too much on just one sector.
SThree (LON:STEM)
This recruitment group is focused on STEM sectors (science, technology, engineering and maths). Although it’s not immune to the cyclical slowdown being seen in the recruitment sector at the moment, I would expect it to benefit from strong structural demand trends for the foreseeable future.
Although the shares are down by around a third from their 2021 highs, anyone who has bought at past lows may still be sitting on a double bagger.

There have been some attractive dividends over the years as well. I estimate that dividends since SThree’s IPO have provided a c.100% return on the original flotation price.
This is a very capital-light business, so return on capital employed and cash generation are excellent, despite the low margins typical of this sector:

Net cash of £83m at the end of August should provide protection against any short-term headwinds. I think the shares are very attractively priced at the moment.
(Another company I like in this sector is Pagegroup (LON:PAGE), which I recently covered in more depth in this Stock Pitch.)
Somero Enterprises (LON:SOM)
I suspect this US concrete-levelling specialist may be more of a cash cow than a true quality compounder. Although it’s extremely profitable, I think this business will always be tied to the cyclicality of the construction sector. In addition, I’m not sure how much further it will be able to scale outside its core US market.

Fortunately, in my view, Somero’s management has avoided the temptation to expand sideways into areas where the business lacks a competitive advantage. Instead they simply focus on executing their core business well and maintaining a strong balance sheet. Excess cash is returned to shareholders when it’s not needed.
Of course, there are a few potential downsides. Cyclicality in the construction sector can be brutal. Somero’s recent results alluded to contractors (the company’s end clients) being forced to re-tender for projects in the US, as developers face higher financing costs and other headwinds.
Supply chain issues relating to concrete also persist in the US, apparently due to strong demand and some continuing labour shortages. I think many of these risks are already reflected in the share price, but there’s no doubt in my mind that if the US economy really slowed, Somero could have further to fall:

Keystone Law (LON:KEYS)
I’m generally sceptical about listed legal firms, as I believe partnerships are better suited to this type of business. However, Keystone does seem to have a differentiated business model, providing a centralised IT infrastructure and branding for self-employed lawyers.
Recent trading guidance was fairly confident:
The Board is confident that the business will continue to trade well for the rest of the year and that FY 2024 results will be comfortably ahead of current market expectations.
Keystone’s operating profit has risen much faster than its revenue since its IPO in 2017:

This has resulted in an impressive improvement in returns on capital employed:

I think this business may be showing signs of delivering the kind of operating leverage Ed discusses in the masterclass above – one characteristic of a multibagger.
One final attraction is management ownership – founder-CEO James Knight still owns almost 28% of Keystone. This should align his interests closely with those of shareholders.
I don’t find it too difficult to imagine this business doubling in size again. However, it’s not the cheapest stock in this selection and I don’t know the business all that well, so I’d want to do further in-depth research before considering a purchase.
Record (LON:REC)
As with Somero, I am not completely sure if this specialist financial stock is a cash cow or a compounder. Record is certainly extremely profitable:

However, the group’s growth record is less consistent:

Record’s core currency management services appear to be quite sophisticated and successful, but growth has often been weak. The company is attempting to address this by expanding into the asset management market, with a number of specialist funds.
I am not yet convinced by this strategy, as it seems to me that Record might be at risk of expanding into areas where it lacks a compelling competitive advantage. But I could be wrong.
The company has a new chief executive coming on board next year and recent interim results did not suggest any serious concerns for me. The shares have sold off sharply this year, increasing the value on offer:

Record’s dividend yield is now over 7%. Given the group’s net cash balance sheet and impressive long-term profitability, I’d suggest that the business is priced for zero growth at this level. As a result, I think Record shares could perform very well over the next few years, if management can deliver a decent run of growth.
Disclaimer: at the time of publication, Roland owned shares in Somero Enterprises.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Cash cow:
1) Generating consistent high FCFF return on capital employed. The business generate a lot of leveraged free cash flow either because they are not investing for growth or they required minimum investment to grow their sales or profits.
2) Capable of keeping competitors from entering its markets. This might be due to the low attractiveness of their industry such as tobacco or printers.
3) High dividend payout rate, high yield and frequent shares buyback.
Compounders:
1) Generating consistent high FCFF return on capital employed because the business is require minimal investments to grow.
2) There are still scope for its to re-invest its cash flow at high rate of returns.
3) It is capable to fending off competitions and keep its high returns.
4) Don't overpay.
When I'm looking for potential multibaggers;
As well as looking for a low PER < 20, Market Cap > £20million, ROCE above 15%, etc, I am also looking for companies who are announcing EPS Upgrades and are also increasing their ROCE year on year because I believe both of these values are strong trates for companies which will become future multibaggers.
Today Rolls-Royce Holdings (LON:RR.) has announced it plans to quadruple profits over the next 5 years and cut costs by £400-£500million. In my opinion, if RR achieves these targets then it is set to increase its EPS and ROCE, which in turns means it could multibag over the next few years.
I Hold.
David.
An update for anybody who owns shares in Rolls-Royce Holdings (LON:RR.) . On Friday 15th December 2023 the company announced that Turkish Airlines will be placing an order for 100 Rolls Royce Trent XWB-84 engines and 40 Rolls Royce Trent XWB-97. This should boost RR's revenues in the coming years. RR shares are up 220% YTD. This implies its reported earning will be increasing, which should lead to an EPS upgrade and also an improving ROCE.
I Hold. David.
I have 4 on the list - CNA SMWS SQZ REC.
REC showing a slight loss, SMWS +25% but CNA & SQZ have 3 bagged so far!
Been looking at POLAR recently, but yet to pull the trigger - feel they could go lower yet
Interestingly I have 6 of the 20 stocks thrown up by this screen Somero Enterprises (LON:SOM) SThree (LON:STEM) Renew Holdings (LON:RNWH)
I only have 5, apart from Yu (LON:YU.) they are all showing a loss, I think most will recover but may take some time.
One of the 'strategies' I am trying to follow is seeing where companies pay decent dividends, have a good rate of ROCE and are also buying their shares in (without excessive debt, and preferably because of excellent cashflow). A below optimum PE ratio helps make it an attractive prospect
Of course there are individual weaknesses and potential traps in any such selection. An example is:
IG group (LON:IGG) P/E 6.7, Dividend Yield: 7%, ROCE: 18.4 -sits in a volatile sector, subject to regulation, has exposure to US & UK
Thanks for your thoughts. HL seems an interesting one in that, like IGG, it seems to be struggling from market declines and investor caution. So it maybe they'll be some pickup if/when sentiment returns to the market.
Somero Enterprises (LON:SOM) have huge export potential outside the US. They have only just started to exploit this. They are also a very likely takeover target at their current price.
Also look at the industrial construction charts in the US. I suspect that current trading will be going well in their main market