#9 - James Cropper - a possible multibagger

This is #9 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
James Cropper (LON:CRPR) is a family business containing a legacy Paper & Packaging division and a much more profitable and fast-growing Advanced Materials operation. This latter unit serves customers in high-tech industries such as aerospace, defence and energy.
A StockRank of 98 that’s led by high Quality and Momentum scores highlights the potential of the business. If management can return the Paper & Packaging business to sustainable profitability, then investors have the potential to profit from continued growth in the exciting Advanced Materials division.
The Big Picture
James Cropper has been through a difficult period in recent years. Losses in the Paper & Packaging (P&P) business have offset growing profits from Advanced Materials. However, progress is being made restructuring P&P and securing new volumes to replace lost business.
Management is forecasting a return to breakeven for P&P in the final quarter of the current year. Achieving this could allow the value and growth potential of the Advanced Materials business to really shine through:
Growth market opportunity: the Advanced Materials business has a growing presence in a number of nascent markets such as green hydrogen electrolysers and fuel cells. These are smaller businesses at the moment but have high potential growth rates.
Established markets offer revenue security: alongside these nascent markets Cropper generates much of its Advanced Materials revenue from slower-growing but more secure markets such as aerospace, defence and medical. Products are typically designed into OEM products and often have long specification cycles, resulting in reliable repeat revenue once established.
Balance sheet repair: the business has been significantly de-risked by a reduction in net debt over the last 18 months. Leverage and debt levels now look sustainable with increasing headroom to support investment in Advanced Materials and – eventually – the reinstatement of dividends.
Going Deeper
For its size, James Cropper is a somewhat complicated and unusual business. The standout opportunity for the future is the Advanced Materials division. But a closer inspection reveals a number of other areas where small improvements could lead to material gains for shareholders:
Unusually low valuation: the shares look unusually cheap on a historic view, trading on a single-digit forecast P/E for the first time in many years. If profits can be sustained and increased from current levels, a re-rating seems very possible.
Pension deficit opportunity: a chunky £13m pension deficit currently requires additional cash contributions of around £1.5m per year. That cash would support a 5% dividend yield at the time of writing. Management has committed to a long-term strategy to eliminate this liability. Success could result in a significant improvement in free cash flow each year to support shareholder returns.
Opportunity in paper? It’s easy to deride Cropper’s Paper & Packaging business as a capital-intensive, legacy business with marginal profitability. But this division has a heritage of innovation and generates sales of more than £60m per year. A return to modest levels of profitability could provide a material boost to the group’s annual profits.
What The Brokers Say
Broker coverage is limited and it’s worth highlighting that this is an illiquid stock. This isn’t a share to trade in and out of. However, Cropper does have broker coverage from Shore Capital which is available to private investors through Research Tree. This provides additional insight and detail to complement forecasts on the StockReport.
Upgraded forecasts: earnings estimates for both the current and following years were upgraded following October’s half-year results. We like to see this because our research has shown that upgrades are often cautious, with analysts raising forecasts incrementally. For this reason, broker upgrades can be a prime driver of momentum and market-beating share price gains.
Improved margins in FY27: Shore’s current forecasts suggest Cropper’s pre-tax profit margin could rise from 4% to 5% in FY27, with further gains pencilled in for FY28. Improving profitability was highlighted by our multibagger research as a key factor in long-term share price gains.
The Bear Case
James Cropper is a small company with a relatively large asset base. Controlling family ownership and heritage considerations may limit the ability of the company’s newish CEO to make decisive changes to the business.
Paperweight: it’s possible that producing paper and packaging at a relatively small scale with high energy costs is simply not a viable business anymore. While the Paper & Packaging business might struggle on close to breakeven, it may continue to act as a drag on the growth and valuation of the group as a whole. In theory it might be more sensible for the company to dispose of its Paper & Packaging business, but a 180-year heritage as a family firm means this may be unlikely.
Management risks: newish CEO David Stirling was previously in charge at Zotefoams, where he oversaw a heavy investment programme in a speculative new technology that ultimately failed to win commercial adoption. While family ownership and debt levels mean spending is more constrained at James Cropper, effective spending on new capital projects will still be an important element of long-term growth. It’s too soon to say if Stirling’s initial strategic decisions are bearing fruit.
The Bottom Line
James Cropper’s Advanced Materials business is probably undervalued and almost certainly has attractive long-term growth potential. If the company can resolve the profitability issues in the legacy paper business and address its pension deficit, the group could become much more profitable and cash generative.
In that scenario, shareholders could benefit from a significant re-rating driven by the trinity of revenue growth, higher profit margins and a higher valuation multiple – the classic formula for a long-term multibagger.
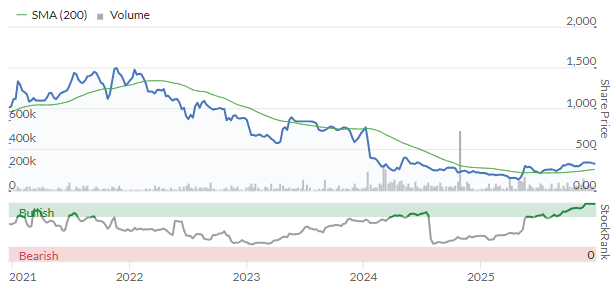
Recent share price action suggests a bowl may be forming and highlights a sustained upgrade in StockRank – potentially an attractive setup for a momentum play.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Just looking at the interim results on this, why is the IAS 19 pension adjustment considered an an adjustment?
Further to this, if you use the adjusted PBT of £2.115m (including the IAS 19 adj), it gives an EPS of 15p for H1, resulting in a current adjusted P/E of 13.3 (based on current share price of 398p, and I have doubled the H1 EPS to 30.0p to account for a full year). If you remove the pension adjustment, adjusted PBT falls to £1.720m and adjusted EPS for the full year falls to 21.7p (10.9p x 2) giving an adjusted P/E of 18.3. Both seem a bit high, considering two thirds of the business is breaking even and not growing, although is it right to remove the pension deficit in the way I have?
Great article. Very little liquidity in James Cropper (LON:CRPR). I hold.
I’m not sure you expected it to bag today!!!! Is it just illiquidity or is something going on?
All the shares recommended recently have risen sharply.
Not sure that's true - most of the other picks haven't moved much. Would be amazed if this pick has caused it to rise 27% - surely must be something else going on. I guess it is very illiquid so that could be a factor.
The only reason l can find is "Recommended as a buy on Stockopedia today."
Many stocks featured in NAPS were up strongly this morning, Gattaca (LON:GATC) finished up about 17%, bet those directors, wish they had not sold the other day.
This is getting like some magazine tips.
With a market cap of £31m it doesnt take much to move the share price. If you check the volumes from today there isn't anything crazy, most trades are £2k, £3k, £5k and some £9k. Not inconceivable that the Stockopedia community driving the majority of those.
everyone buying tips
Happy to see this one which I bought two months ago. Nice bowl if you like that sort of thing!
An interesting and balanced summary, thanks Roland.
One lesson experience has taught me is that holding significantly more shares than the EMS in an illiquid stock can be stressful and adds downside risk.