A practical guide to keeping losses small

I remember the first stock that I recommended for purchase across all our client accounts in my private client group at Goldman Sachs. I was 22 years old and had to comply with the "process". That process meant that shares needed to have been recommended by one of our research analysts, who sat on a different floor to our investment team. I had been watching an Ed-Tech firm with the ticker symbol, CBTSY, and for no apparent reason, it had fallen about 30%. I applied the process, phoned the analyst who confirmed he had just spoken to the CFO very recently and that there was no change to the story. We bought it across all our client accounts.
The next day, the shares slumped dramatically on a profit warning. My boss, with more experience than I, immediately sold, and we took a £1 million loss across the accounts. There were many lessons that I took from this. I rarely trusted research analysts again, but more importantly, learnt the lesson of taking losses quickly. CBTSY continued to fall over the coming months.
As much of the stock market grinds lower, more and more shares are reaching bargain valuations. But markets can stay irrational longer than you can stay solvent. If you buy stocks, you are going to pick some losers, no matter how cheap they seem. This creates a quandary. What should you do with your losers?
In this article, I will illustrate the importance of keeping losses small with a few mental models and some practical guidance on loss management.
Fighting the inclination to hang onto losers
Daniel Kahneman and Amos Tversky extensively studied human behaviour towards differently framed opportunities in their famed “Prospect Theory”. What they found is that we have a tendency to be risk-seeking in our approach to holding losers, but risk-averse when it comes to holding winners. They found that we feel pain of losses more than twice as much as the joy of gains.
The chart below is a handy illustration of this effect.
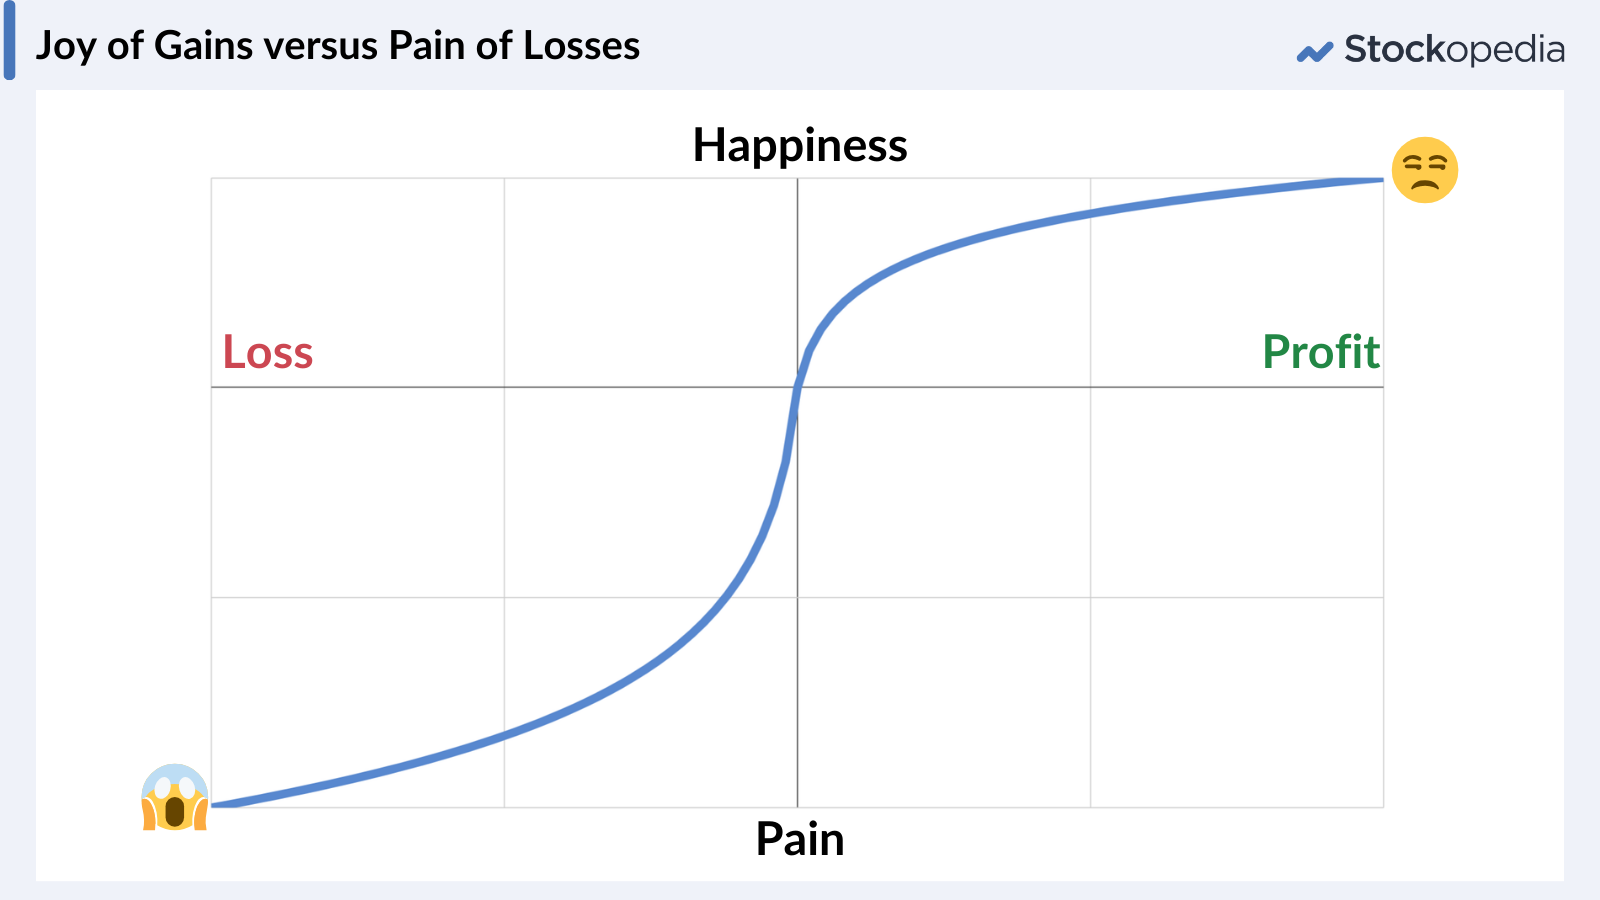
Psychologically, we don’t believe we’ve taken a loss until we’ve sold a share, so we avoid selling as we think “it might come back”, but we tend to sell gains too quickly, as we say to ourselves “we might lose our profit”. So we snatch at gains, and hold losers. This is the completely opposite behaviour to the age-old winning investment maxim to Run Winners and Cut Losers.
If you don’t fight the tendency to hold on to losers, and fight the tendency to sell winners, making any money in the stock market is an uphill battle. Just remember, our psychology is not well adapted to this behaviour, so we have to force ourselves to learn this habit through practice.
The larger the loss, the ever larger the recovery
The value of keeping losses small is no better illustrated than in the graphic below. If you lose money, the gain required just to recover the loss grows by a power-law. If you lose 50% on a position, that position will need to double just to return you to breakeven. If you lose 90%, it needs to gain 900%.
This is such an important mental model. Burning the below graphic into our minds helps considerably when thinking about what to do with losers.

Instead of thinking about cutting losses as an admission of a mistake, or as an unnecessary commission to your stockbroker, think about them as an insurance premium. There’s great comfort in paying car or home insurance, so why not consider small losses as a premium paid to preserve your capital?
More than this, if you think “keeping losses small” is just a trader’s maxim, think again. None other than the great Warren Buffett has hammered home two rules of investment. Rule #1: don’t lose money. Rule #2: don’t forget the first rule.
Buffett is of course the greatest investor of all time and has an incredibly high hit rate for identifying long-term, compounding winners, but if he makes a mistake he gets out. It’s not exactly easy when you invest at the scale he does, but his Tesco investment is a good example. Bought in 2006, the business deteriorated through 2013. He was mostly out in 2014. While Tesco hasn’t slumped more since, the opportunity cost of having his capital in an underperforming stock was significant. He had better uses of the funds. Don’t hold losers.

Of course, Warren Buffett’s approach to avoiding losses is to ensure that all purchases are made with a significant Margin of Safety between the price paid and the true intrinsic value of the investment. This lesson was taught by his tutor Benjamin Graham, the “Father of Value Investing” as the most important principle of investment. If you buy with a high Margin of Safety the likelihood of significant losses is reduced. He also espoused broad diversification across undervalued stocks to ensure the risk of losses on a single investment could not impair capital to a significant degree.
Whatever your style of investing, not losing money is the most important principle for ensuring strong gains. If you keep your losses small, the gains take care of themselves.
What to do with losses
The book “The Art of Execution” by Lee Freeman-Shor has a useful model for what to do with losers. He studied the results of many fund managers over a multi year period. He identified the habits of fund managers handling losing positions and classified them as assassins, hunters and rabbits.
- Assassins - those that act quickly and cut their losses on losing positions.
- Hunters - those that bought more, averaging down when prices fell.
- Rabbits - those that did nothing on losers. Stuck in the headlights.
He found that out-performing fund managers were decisive - either Assassins or Hunters - whereas Rabbits were consistent under-performers. So you only really have two options when you are present with a loss. Cut losses or average down. Doing nothing is not an option.
As an amateur investor, your ability to identify the right stocks to average down on may be more limited. If a share really does have a strong Margin of Safety, then purchasing more can make sense, but it's easy to become extremely overconfident on even a limited amount of research. You may well be wrong. Not only this, but if a share price falls, it has negative momentum and many investors will have regretted their purchase at higher prices. These present headwinds to share price recovery. This is why I personally believe taking an assassin approach is quite a sensible approach for many investors.
Using stop losses to keep losses small
Much of the professional investment community rejects stop losses, mostly because they are hard to use when deploying large scale funds, but individual investors, deploying smaller capital, have no such constraint.
The mistake that most investors make with stop losses is to use the same stop loss level for all positions. They pick something arbitrary like 10% and wonder why they get whipsawed out of their small cap positions regularly. There’s nothing worse than selling your position on a 10% loss only to see the stock bounce back above your purchase price the next day.
The key is to set stop loss levels in relation to a share’s price volatility. More volatile shares are more likely to hit tight stop loss levels. So use wider stop levels for more volatile shares.
A reasonable shortcut is to use Stockopedia’s RiskRating Classifications or the “6 month Volatility” metric which is available to add to tables. I find that using the 6 month share price volatility (or less) to be a reasonably effective stop loss level for many shares.
In terms of coupling stop loss levels to the RiskRatings, I’ve found the following rules of thumb quite useful. We applied these in our Staff Investment Club to good effect, one example being LoopUp which we were stopped out of at 192p for a 22% loss. LoopUp’s shares now trade at 2p.

The RiskRatings are published at the top of all StockReports in the Classifications section.

If you can’t stomach stop losses…
And just to finish off this piece, if you don't use stop losses then there is one final rule. It was first promoted by Peter Lynch in his essential "One Up On Wall Street" and reiterated by Jim Slater in his excellent "Zulu Principle" pair of books.
Sell when the story has materially changed.
As a stock picker, whenever you buy a share, it's imperative to have a strong grasp of the "story". Peter Lynch will try to write a two-minute monologue about a share’s narrative, which he would use to clarify his thinking, and refer back to through time. Keeping a journal, or record, of the reasons why you bought a share can help you reassess the continued investment case when things change.
Things do change. Profit warnings. Management mistakes. Di-worseifications. Competition. Limits to growth. External disasters.
The great lesson I learned very early on with CBTSY, was that you should cut your losses as soon as the story has changed. Even if it’s the very next day.
I am sure that many in the community have their own rules for keeping losses small. Ultimately, the best is to buy with a good margin of safety and time the buy well - arts in themselves.
Please let me know your own thoughts and principles, and I'll try and reply when I can.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
This practical guide has been most useful advice.
So if you've used stop losses (and I'm not knocking anyone who has) you're now sitting on 50%+ cash and the market has just bounced a few percent, what do you do now? Is it a dead cat bounce, or the start of a new bull?
I know I'd be highly uncertain about what to do in these conditions so just riding the volatility works for me. I have sold some stocks that disappointed operationally but not those who have just fallen with the general malaise. That has left me sitting on some large drawdowns & paper losses for sure but almost still fully invested, and no big decisions to make.
So, genuine question, when do you get back in?
Great article Ed.Robbie Burns the Naked Trader often says “lots of small losses are a good thing”
D
I follow Slater and Lynch in writing down the reasons I have bought a share and, provided those reasons are still valid, I hold pretty much regardless. With most stocks, I am buying a trend, so I set a price when I buy, of where the price would have to fall to to break that trend, and that is my stop loss.
Very useful article and very much needed as the 'when to sell' is often not answered well. It is great to have Eds view on suggested stop losses linked to volatility since they act as guidelines for us with less experience. I think one question I have is in relation to the story changing point about 'external disasters' - does this mean a war or pandemic or ? I am still unsure what to do in these circumstances since often there is a massive fall and then a big bounce shortly afterward
One of the best articles I’ve read on Stockpaedia
This is a very useful article and I'm already taking the lessons from it onboard.
Basic question. You can buy a stock with a wide buy-sell spread, with a transaction cost, stamp duty and possibly forex charges. As soon as you've bought the stock you can automatically be down 3-5% sometimes. Do people set their stop loss from the putative sell price at the moment they bought the stock or from the price they paid?
When I started, for example, I sometimes tried to apply a tight stop loss of 7-8% as per Bill O'Neill's book but if I was instantly 3% down on the purchase then effectively it was a 4-5% stop loss. Which proved ridiculous. Hence I don't own ScS any more, but let's gloss over that....
It's always from the price you paid. The spread is an additional risk you need to factor in, but I would recommend you stick to the more liquid names, ideally with a average long term spread of 0.5% or less. In the UK, this will broadly limit you to the FTSE 350, a handful of mid cap stocks on AIM and small caps which were former mid cap stocks (e.g. Boohoo (LON:BOO) , Iqe (LON:IQE) , Saga (LON:SAGA) )
This of course pushes you away from where most of the alpha performance in the UK market comes from.. the small caps!
I had to smile when I read your comments in Stop Losses. That is exactly what happened in my first attempt: price bounced back up.
So now set alerts a few points below my target and monitor it.
Your Risk Table was particularly useful so will be using this.
Hi Ed,
The stop loss % you have shown how applicable are they when you have an overall slide on the markets such as the problems in Isreal at the moment and the concern a lot of investors have about higher interest rates. I have quite a lot of stocks which due to market conditions are minus 20% or more. It is quite difficult to sort out what is down to market conditions and what is down to the stock itself, a lot of my minus stocks have very good fundamentals.
regards
Melvyn Frewin
Quite rightly the article focusses on selling bad investments because this causes the damage of drawdown.
A second article could be on selling winners. Buffett may say that he holds forever, but this is obviously absurd if the price is way above value and you can buy back two years later at half the price.
Perhaps sell when the value or quality rank falls below 80 is a good rule.
Hi Ed
I got attracted to your site and have stuck with it because of your objective quantitative approach, in particular through the NAPS method. This article appears to drift towards 'story share' territory. There are other sites that go in more for the 'story' approach (e.g. Motley Fool). I think your NAPS performance beats them? I thought I read on one of your NAPS articles that it's best to stop fiddling and resist over-complicating (e.g. with stop losses) - just stick to the simple rules and leave it at that. Am I recalling correctly?
@London2000 - there are different approaches to the top of the mountain. Whats important is to find an approach that suits your psychology.
The late Van Tharp once said that "you don't trade the market. You trade your beliefs about the market. ". I think this is brilliant wisdom.
What you find in discussions such as these is that people end up counter pointing different belief systems. It is possible for everyone to be right, even when they have diametrically opposed views.
So the "hold forever" crew are right in the sense that their belief system is based on a long-term holding period, owner-earnings analysis, and that quality compounds capital. The cost of this belief system is deep investment in fundamental analysis, over attachment. plus fully invested drawdowns.
The "stop loss" crew are right in the sense that capital preservation is key, the market is right, there is an opportune time to buy, and not to fight the tide when it's going out. Thats another belief system. The cost of this belief system is more activity, higher costs, being prepared to hold cash in bear markets and being bold enough to re-enter when the time is right.
The "systematic equity" mindset (a la NAPS) is also right in the sense that there are equity return drivers, that rebalancing keeps you exposed to them and that a hands off approach reduces the need for emotional control. The cost of this is periods of underperformance, a proportion of errors, and system fiddling.
Personally, I gain greatly from knowledge of all approaches, and use them where I see fit. I buy discretionary based selections, run systematic equity selections and use stop-losses where capital preservation is key.
All in all, what matters is knowing that you trade your beliefs, ensuring that your beliefs are sound (and ideally empirically backed), and ensuring emotional control.
At the end of the day, I believe statistics beat stories... but stories drive most of the fluctuations in equity prices from year to year.
Good question! Thinking, Fast and Slow is essential reading, IMHO, for anyone involved in making financial decisions.
I think it is important not to confuse 'Fast thinking' (i.e. heuristics) with fast reactions.
The time for slow thinking is before purchasing any financial instrument. How much do I hope to make? How much am I prepared to lose? Is the purchase price right? etc.
Once the purchase has been executed, then it makes sense to stick to the pre-purchase plan. Even if you have sell a few hours later.
If one reviews the carefully laid plan in order to justify increasing the loss, that is fundamentally 'Fast thinking' (i.e. loss aversion) rather than rational slow thinking. Even if one spends a long time thinking about it.
Paradoxically, thinking slowly is not the same as Thinking, Slow. It is an inefficient form of Thinking, Fast.
At least that's my view. (And I've hit rather a lot of stop losses recently. Painful, yes. But no regrets.)
Excellent advice. I am currently reviewing my portfolio and although Ying is staying "its too late to get out" Yang is saying " get out now" Capital preservation is what its all about. The Canary in the coal mine for me has been Tesla Q3 this week. Tesla is one of the greatest companies in the world 27billion in cash, no debt, overall margins of 15% and growing at 50% per year. Elon Musk told the truth this week about the head winds we face and it does not look pretty. Its just a pity the market makers always seem to walk away ahead. Ahhh that's Capitalism.
Some observations.
I don't use stop losses as it doesn't suit my approach/personality. Peter Lynch also eschewed stop losses. For a patient investor in a bear market such as now, especially small caps, the use of stop losses often results in perfectly good companies being jettisoned for no reason other than sentiment. The opposite of the rising tide anecdote
One can never fully plan for 'black swan' events' such as the pandemic, Russia/Ukraine conflict or even cyber attacks, Volex (LON:VLX) one of my larger holdings being an example of the latter. However I seek to mitigate the risk as best as possible by avoiding companies that are overly indebted (the majority of my small cap portfolio has no or minimal gearing) and as Ed mentions keeping up with the 'story'. If there is a fundamental change in the 'story' from that on which my purchase was predicated I will sell.
I like to buy good companies when they are historically cheap relative to the investment metrics they have sold on in 'normal market conditions'. The cheaper the better. For example I have recently added to positions in Sanderson Design (LON:SDG) Palace Capital (LON:PCA) IG group (LON:IGG) Jet2 (LON:JET2) HgCapital Trust (LON:HGT) Harbourvest Global Private Equity (LON:HVPE) Polar Capital Holdings (LON:POLR) Porvair (LON:PRV) .
I have also opened positions in Jupiter Fund Management (LON:JUP) and Card Factory (LON:CARD), given the battering the former has taken and the very much improved performance of the latter
I accept that they all may get cheaper but to my eyes these and many more UK shares are sweets in the candy shop. I expect to get some decisions wrong, but given the market cycles I believe that this is a good time to buy, rather than commit money to cash or various money market accounts. Regarding the latter I would draw attention to the yields on cash rich comapanies like IG group (LON:IGG) and Polar Capital Holdings (LON:POLR), In excess of 7% and 11% respectively.
Patience is an obvious pre-requisite and a little luck is also helps.
All the best
The article talks a lot about the % decline before you sell but not much about how often you should review your holdings. Selling the minute a stock hits your stop loss gives you a very different result from reviewing every month or quarter and selling anything at or below your stop loss. Could you give us your thoughts on this
The closing paragraphs of this piece seem particularly poignant to the relevance of what I consider to be Stockopedia's chief product, the StockRanks. When the story changes and it's time to sell, this is effectively communicated to subscribers through the ratings, which should go down, particularly the Quality Rank, within 24 hours of the point of inflection.
Should I sell or should I hold? Losses well in excess of 20% on Liontrust, Central Asia Metals, DotDigital, Eurocell and Ferrexpo but with QR of 96,93, 91,90 and 87 respectively.
I would go by the StockRanks: Hold Liontrust Asset Management (LON:LIO) & Eurocell (LON:ECEL), and Sell dotDigital (LON:DOTD) & Central Asia Metals (LON:CAML)
I am embarrassed to say some of my holdings I have let slip to 50 and 60% (bad management on my part ) at the stage were I feel it almost too late to take this loss even though I could lose more . New holding I will need apply more discipline . Any thoughts ?
Tony, I feel your pain and have been there. My feeling is that, as the article says, it is better to accept where you are, not avoid selling to "avoid the loss" since it is already real (yes, it really is) and use that capital that is then freed up to buy a better quality, value momentum share, perhaps by using the StockRanks to guide you and not (for me at least) the story.
Today, before I came to Ed's article here, I was going through my portfolios and while doing so noting the Lowest of the Lows which still pay a dividend. There are 15 of them, obviously they are in there with the most underwater stocks that I hold. The question was When to Buy and I resolved to construct a virtual porfolio made up purely of those companies. A pity that Stocko does not allow more than the 10 virtual portfolios that I already monitor so how about it Ed?
More Folios please!!
Thank you for an interesting article. In reply to Acounsell's comment you say that the article is about ".... loss management on your purchase price", surely this implies that when purchasing a stock one need's to pick the bottom or within x% of the bottom, that is time the market? If you don't by definition any stock where you don't time your purchase within x% of the bottom, the cut your losses rule will cause you to exit the stock. And yet if your own analysis tells you that the stock on a say five year view is undervalued by 100% the market selling it down further is irrelevant? You believe it is worth £2, you by for £1 and subsequent to purchase it declines to 80p, so one sells. The logic escapes me, though I suspect I am missing something. Even Buffett talks about him wanting a stock price to decline further after an initial purchase, so he can but more as it goes further "on sale". I can't find the prices that he paid for Amex back in 1963 but suspect the bottom caused by the salad oils scandal, was probably well below his first foray in to the stock and because he believed the market was wrong he kept buying.
I tried to do this back on March 19th 2020 (when everything I held was way down on its purchase price) and though I scraped back to level at the end of the year it cost me 35% of my portfolio value. i.e. If I had done nothing and "held on" to my losses I would have been up 35% on the year.
I am afraid I haven't the time to analyse my holdings but my gut tells me that in this current market I would have sold many of my holdings at some point, if say I had a rule of sell on a 20% pull back from my purchase price. Further if I had followed this course of action when would I have found the courage to get back into the market? As things stand (inflation, Ukraine, Israel, Taiwan, general uncertainty) probably never!
And while the old saw of if it drops 50% the stock has to come back 100% to make your money back is mathematically true, stocks do that all the time. Amazon.com (NSQ:AMZN) has done it, Berkshire Hathaway (NYQ:BRK.A) has done it, the S&P did it in 2008/9.
I think the situation is more nuanced. If the decline is caused by news flow e.g. loss of a court case like XP Power (LON:XPP) or a profit warning Sos (NYQ:SOS) (As your guide advises) then the argument probably holds but on a general market decline, which I believe is what we are experiencing at the moment, then I am not sure that cutting purchases whose share price has declined below one's purchase price, is the best course of action, especially if you believe your original thesis holds good.
Both your own Megan Boxal and the David Gardner of the Motley Fool expound a "never sell" philosophy and I think that this has a lot of merit, as long as position size is controlled. This has been my error, not in not selling stocks whose prices has declined but having far too large a position size in a particular stock, which causes me to become a rabbit, when it does decline.
If I need reassurance I tend to look at this and it helps keep me level headed.
Regards
Michael
PS I should add I have lost far more money on not selling winners that had made me good paper profits but I thought were going to continue to grow to the sky. Fevertree Drinks (LON:FEVR) Anglo Asian Mining (LON:AAZ) to name two
Hi Michael,,
Excellent analysis with which I agree 100%.
@Michael.
"the article is about loss management on your purchase price", surely this implies that when purchasing a stock one need's to pick the bottom or within x% of the bottom, that is time the market?
I think if you re-read the article you'll find the thoughts are more nuanced than this. It's easy to over-index on the stop-loss section due to the graphic. Exit strategies (and loss management) should pair with your investment approach.
I do think for investors who are approaching the market with either a deep "margin of safety" or compounding quality long-term investing approach, then it can make sense to average down losers (if you are right in your analysis, and as long as the story is unchanged). It does take significant security analysis skill.
The real challenge for those that use capital preservation techniques (like stop losses on purchase price) is ensuring you don't become a different form of rabbit - one who never gets back in. It's imperative to have clear re-entry strategies.
That's where market timing does help considerably. Small caps especially have a strong tendency to trend over larger time frames. The lions share of stock market profits come in periods where the market uptrends. That's obviously not the case yet.
Hi Ed
Thank you for your reply.
I have re-read it a few times and still can't quite see any contradiction in what I have written.
I have not used stop losses and if the fall is caused by a change of story rather than a Mr Market Hissy-Fit, then ones active following of the company should cause you to exit the company.
But if a company declines because of a buyers strike (few buyers than sellers at any particular price), then I am still not convinced that selling out is necessarily the correct course of action, and while buying more at the lower price might strictly be the correct course of action, it assumes that one has fresh cash to deploy, because if you don't then by definition it will necessiate selling another company.
I also think that this could lead (in a market that we are currently experiencing) to over activity and while it has not been comfortable I have almost done nothing this year (apart from selling Ergomed (LON:ERGO) ) because there just seems to me to be a lack of visibility (Ukraine, inflation, interest rates, Israel, Taiwan) and at the moment I am not prepared to go to cash.
Regards
Michael
Yep I agree with this. I don't use stop losses and never will.
I'm an investor - I'm not a trader!
I try to buy good quality businesses at reasonable valuations and strongly believe that time in the market will usually beat timing the market.
The problem with stop losses, is when do you get back in? You could literally end up losing 50% of your portfolio and have zero holdings - it is actually very dangerous imo in this type of market - it ends up being 'death by a thousand cuts'. You could literally lose a fortune on the same stock just because we are in a volatile market and your entry price wasn't timed to perfection, because your crystal ball broke that week and the market sentiment drove the SP lower (nothing to do with the quality or the value of the company). A volatile stock bouncing about could stop you out several times - without a very precise re-entry strategy - this makes the strategy very floored imo.
During tough bear markets - I always ask myself this question - Would I rather keep my portfolio or would I rather have my looses back (obviously with the caveat that I cannot invest again!) My answer is always that I would rather keep my portfolio of companies. I might need to make some amendments to ensure I have the correct balance and quality of holdings - but the actual ticker price movement is irrelevant during times like this when prices are mainly driven by sentiment rather than the individual businesses fundamentals. I sleep at night knowing that I own some great businesses that have very bright long term futures. If I kept taking losses on business that I liked, and kept seeing my portfolio going down in value without anything tangible to hang on to - I personally would find this intolerable. The reason I can stomach the losses is because I believe in the long term success my portfolio of companies - and therefore I do not need to sweat every daily move.
For those that would rather take their (refund) losses back - I think you need to improve the quality of your portfolio or perhaps invest with a fund manager. Because this is the key to being an investor. Invest in good companies and be patient - Buffett keeps telling us how simple it is - it really is not rocket science. So if you are not comfortable with the volatility of a bear market - then perhaps the personal management of your money should be left to an expert fund manager / asset manager.
Ed,
In the article you discuss using volatility to help set a stop loss percentage.
I have been collecting volatility data from Stockopedia for some time now. In my screens the column is labelled "1 Year Volatility %". Between 4 March and 1 April 2023 there was a step change in the mean volatility of my sample of over 500 shares.
Was there a change in the way volatility was calculated by Stockopedia at that time, or do you think this represents a genuine change in the market?
The chart below is generated from monthly data and clearly shows the effect.
@DWit199 - just circling back to your query. The volatility dropoff is because all our volatility measures are based on a daily volatility calculation over a 3 year lookback period. The pandemic was obviously an extreme event and it increased the volatility for stocks across the market. That event purged itself out this March, so volatility measures for all stocks fell.
There are always arguments over the "right" lookback period on stocks for calculating volatility. Some say 1 year, some say 5, but anywhere in that range is fairly normal.
There is an argument to say that the pandemic crash was anomalous, and therefore could be excluded. But black swan events do happen!
Here's a longer-term picture of the median LSE share volatility over the last 7 years (calculated each October). Given the market excitement through 2020-2021 I wouldn't be surprised to see the median annualised volatility drop further towards the lower 40% region.
Thanks Ed, that makes sense and explains what I have been seeing.
I have been doing some work on a trading system in python that uses forecast volatility (next 30 days) as a measure of risk and to size posistions. From a price history I use a long and a short exponentially weighted moving average, averaged with a 30:70 weighting long ewma:short ewma. This takes account of "grey swans" in the short term but forgets these one off and short duration events quite quickly in the long term. Unfortunately, I don't have the resources to calculate voatility in this way for the whole market.
Great article Ed again and great timing. Everyone is fearing their losses, questioning their strategy, and contemplating a sea of red. Hence an article at exactly this time about keeping losses small.
All of which encourages me to think that, with cash positions at record percentages (correct me if wrong on this) and with the AIM All Share at a serious historic low, and with all news bluntly negative.....it has to be the time to buy.
There is a wonderful money manager here in Australia Geoff Wilson, who is sometimes referred to as the Australian Warren Buffett. He loves a punt on the horses also. Once in an interview he was asked why he likes the share market so much. His reply was something along the lines of - investing in stocks is not like betting on horse races, if you back the wrong horse you cannot take the bet off mid race, as with the stocks if you back the wrong stock you can sell and stop the loss and get the remainder of your money back and start again, you don't have to ride the stock to the bottom like a horse.
Ed,
At the moment if I followed this strategy I would pretty much be 100% in cash!! With a portfolio mix of individual shares, Investment Trusts (nothing short of catastrophic!), ETFs and OEICs pretty much everything except anything related to oil & gas, defence and gold related is down by high teens or more. I don’t need to raise any cash and to cite one example Albemarle (NYQ:ALB) which I bought in 2017 - it has been down by close to 50% and up by 50% and has lost close to 20% in the last week. I would much rather continue to hold rather than try to time the market by trading in and out. I might be a Rabbit but when the entire market is in a downward spiral I will just hold on for dear life. After all don’t they say ‘time in the market’ is what counts?
@ACounsell - to be clear - this article is about loss management on your purchase price, rather than selling on a profit. I'll be writing on the latter next week.
Really not trying to be controversial, but why would you hold any stock that’s in a solid downward trend? I’d rather cut losses of stocks that move downward and apply the resources to those that move upward
Really not trying to be controversial, but why would you hold any stock that’s in a solid downward trend?
Because some investors think like business owners, not like traders. Owning a business comes with ups and downs. And if it’s a good business at its core, in good markets, it will end up worth a lot more in the future. And only then do business owners sell.
To be clear, I’m not claiming this is a more profitable approach. Trading certainly has its appeal. But it’s a valid one and preferred by a certain W Buffett, who states you should be prepared to accept a 50% loss along the course of any investment - or you’re not really an investor at all.
Of course, the ideal scenario would be to own only great companies, but only when they’re in an uptrend. If only it were that simple!
Excellent article, and the Assymetry of Loss is fascinating
I would add an obvious obvious reason that might encourage investors to be brave about selling a fallen share. It is very likely that the headline damage can be reduced by offsetting the loss against Capital Gains. So less pain than might at first appear.
You quote the sensible maxim: Run winners, cut losers. A broker once recounted a similar maxim to me: "Fertilize the flowers; pull out the weeds". This splendid metaphor really sticks in the brain!
"Fertilize the flowers; pull out the weeds" is a Peter Lynchism.
I'm looking at my portfolio and pondering what my stop loss should be based on the risk rating. Some shares are under water so I can set my stop loss relative to the entry price. Some of my shares are well in profit so I don't want to use my entry price when determining the stop. Does anyone know if it's possible to mimic a trailing stop loss on the alerts section? I can only see an option to fix against the price on a date of my choice.
Thanks Ed, great timing as am currently considering potential actions in the portfolio.
The biggest factor I keep coming back to with most of my holdings (ignoring a couple of very small speculative positions) is that the business is still performing even though the share price is not, couple that with that fact that in general those shares are also relatively cheap. Possibly wrongly but in some of these positions I'm holding on for the re-bound.
Part Hunter, part hunted LOL
I've absolutely turned my investments around over the last 3 months. I was more of a long term Buffetology investment type, in the last few years that hasn't worked for me all and the losses mounted. Change of plan; worked out at first in paper portfolio. Select candidates from a minervini-eque list which is published on one of the articles on this site. Look for candidates with the following characteristics.
Rinse, repeat. It's a little hands on but picks stocks growing in Stage 2 lets the winners run until they become losers !
Of course not investment advice but a system that has the edge of momentum and losses being cut quickly
Congrats on adapting your approach @Birdiemachine.
Minervini wrote about keeping losses small. He changed his approach to try to never take more than a 6% to 8% loss, which transformed his upside returns. To achieve such small losses needs absolute discipline / timing on entry, moving upstream towards mid/larger caps, and watching positions like a hawk.
Thanks it is though just the discipline to enforce the plan that is important. In my portfolio there are so many cases of positions that would have gone horribly wrong if it terminated early
Hi, why does the 1 Year Price Volatility have to be with in a range? For example, am I wrong in thinking that if I have a Speculative share that has a 20% rating on a 1 Year Price Volatility, then it should be sold as its outside of the 45 - 75% range?
The volatility is not within a range. Those ranges define the upper and lower bound values for that particular risk rating definition. For example, if a share has a 1 year volatility of 42%, then Stockopedia will assign that share a risk rating of Adventurous. The 20% suggested stop loss is not because it is outside 45-75. It is because 20% is the suggested stop loss for shares with adventurous risk rating. There's a great eBook available in the Learn section of the Stockopedia site.
Hi Edward
Thanks for a really interesting article. I intend to re-read it carefuly and ponder the points you've made. But, off the top of my head, it seems to me to raise the issue of market timing. Take AIM for example, it's down close to 50% from its peak, ie an average 50% loss across all stocks. Therefore, using your 'volatility adjusted' stop loss rules would stop one out of all but the most conservative stocks. So, when does one re-enter the market, bearing in mind that the rule of thumb seems to be that returns are cut by up to 50% if one misses approx 10 of the best up days. I think Boon's response is most relevant here.
PS I'm definitely a rabbit who's been hunted!
I have taken the advice from the article and dropped my holding in Rightmove (LON:RMV) today for a 10% loss. With the offer for OnTheMarket (LON:OTMP) the investment case has changed. Hopefully the shares I purchased with the proceeds won't follow suit as the article suggests I would then have to make 25% to recover my losses.
I don’t hold Rightmove (LON:RMV) but if I did I think I would have taken the same course of action because, as you say, the investment case has changed or potentially changed. The uncertainty makes it very difficult to value. But where a price declines because sentiment has just moved away from the company or shares in general, to sell for no other reason than the price decline is a mistake.
If we accept that in the short term share prices move down because there are more sellers than buyers, then we cannot use this to justify selling of a stock. It just doesn’t makes sense in the context of “we are buying a piece of a company” not a tick on a screen.
Regards
Michael
As humans, we hate to actively use our brains. The book Thinking, Fast and Slow is a good read. Most of our days we go through life making decisions that are autopilot / rules driven.
Therefore, when it comes to investing, it is very tempting to do the same. "Ah! I want to find a set of fixed rules that work, so I can go on autopilot and not have to expend effort thinking about my investments".
Ed's proposed approach is the "fast" way - fixed rule, autopilot. Great if you want minimal thinking effort.
The "slow" approach, would be to continuously evaluate the current SP versus your knowledge, conviction, etc. As the share price goes lower, a continuous re-evaluation "would I still be a buyer at this price if I didn't hold? Has the information changed?". Obviously, one can see this is more time consuming, more effort.
Which approach is better? Fast or Slow? I'd love to hear thoughts!
I think that it might depend much on the individual, also on the time commitment he or she is able to make, and also their personal propensity to risk.
However, surely making a rule involves some thinking, there's plenty of guidance in the article to keep one busy all weekend reviewing whether, how and with what criteria to set your own strategy for dealing with losses.
I believe It all depends on how well diversified you are.
For example, if you are fully invested and you have 20 stocks in your portfolio, a couple of profit warnings (even if they go to 0) will not really impact your performance; whether you are an assassin , a rabbit or even a turtle , BUT never a hunter!
Also you need to learn to run your winners, Facebook trebled this year , even M&S doubled.
As for the analysts estimates I couldn’t agree more with you. One should know their estimates and be aware for the market expectations but never to be used for an investment decision.
I think the analyst research community is vastly under-funded in the UK now ( due to European Mifid II regulations), which makes the value of forecasts quite suspect.
The good news is that the government has conducted an "Investment Research Review" with some promising reforms suggested:
Apparently these have been accepted, and may lead to significant government induced action. Unwinding the blockers to better research is key imo.
What to do when nearly everything is running at a loss? Go eat some ice cream maybe.
Hello Ed, my own experience is that the current market is very helpful in figuring out one's own approach to losses, in fact it makes it compulsory. I may be in a group of one but have personally sat in the headlights, compounded with great effect, (unfortunately in the wrong direction by averaging down), and averaged down to great effect, (but wished I could have timed an initial purchase better); however I'm learning by experience and your article is beautifully timed!
I think the only thing I do well is having strict observance of 1) profit warnings, and 2) changes to the investment narrative where I have learned to be ruthlessly risk averse. That's the one area I can say I'm truly emotionless, expletives aside.
The market recently I've found particularly interesting, with price falls on good news, or a rise followed by a fall back after good news, and plenty of examples of sudden price falls on no news. I employed a stop loss recently and of course sold at precisely the bottom and regret my sell decision even though I would still have been facing some loss had I held, and here I've found myself asking whether a stop loss should always be deployed because for the stock in question the investment case had not changed and if anything is now more solid. However I imagine I only regret it because the SP has partly recovered, it might well have gone the other way, as your example with Loopup (LON:LOOP)) brutally illustrates.
The main things I take from this article then are to develop my stop loss rules, and to think further about Assasins v Hunters, (and to re-read 'The Art of Execution'). I know I'm not (currently behaving like) a Rabbit though I do hold one stock to serve as a reminder of what being a Rabbit looks like, and fully intend to hold until it hits zero as a reminder to self. In this particular case I first followed the crowd in buying in (something I'm now much better at avoiding), secondly I behaved like a Hunter in averaging down and then later on failed to spot I'd turned into a Rabbit. Obviously by then my loss was much worse. Would you agree Hunters can find themselves Rabbits down the line, because averaging down increases the stakes, and can magnify the loss, making it even harder to sell once one has doubled down?
How and when (or whether ever) to average down I agree is a very worthy topic, I see it a bit like not selling on a loss and selling too soon on a gain because I find it much easier to buy into a falling SP than a rising one, I know you have also commented before today on this topic, backing winners and cutting losers.
Thanks for the excellent article,
TEIN.
Yes, it is much easier to buy into a falling SP than a rising one, but that's again due to this hard-wired behavioural psychology that predisposes us to shirk at "paying up".
From the momentum research, there's a phenomenon called PEAD (post-earnings announcement drift)... which basically is the opposite of a profit warning. If a stock announces better than expected earnings, it often spikes a bit on the day, but never by enough. Many investors bank a quick profit, while others refrain from buying due to the price spike. It then often gradually drifts upwards as people re-anchor with a new price frame. A stock like Yu (LON:YU.) this year is a good example.
In this market though, positive surprises have rarely been met with strong PEAD. That's more due to the persistent pension and investment trust selling of UK stocks. Fund outflows are dominating at the moment.
This does though act in reverse too. Weak announcements don't get sold enough and tend to drift lower. In this market, many in-line announcements are treated similarly.
So it's important to be careful with averaging down when the market is tricky. As Marty Zweig once said "Don't fight the Fed. Don't fight the Tape".
A perfectly timed article - thank you. Def. a rabbit!
A very timely article, and just what I needed to hear. Thanks Ed.
Great article. Yours truly Mr Rabbit :)
Perhaps I should have added, that although I am certainly more of a rabbit than an Assassin or Hunter, my portfolio has still outperformed another portfolio of mine which is managed by a professional!! Must send him a copy of the article :)
Hi Ed, this all sounds like good common sense. I will use the Stockopedia charts to apply to my own stocks.