Stock Pitch - LoopUp (LON:LOOP)

[UPDATE - the club stop loss was triggered on November 20th at 172p. The Club sold for a loss]
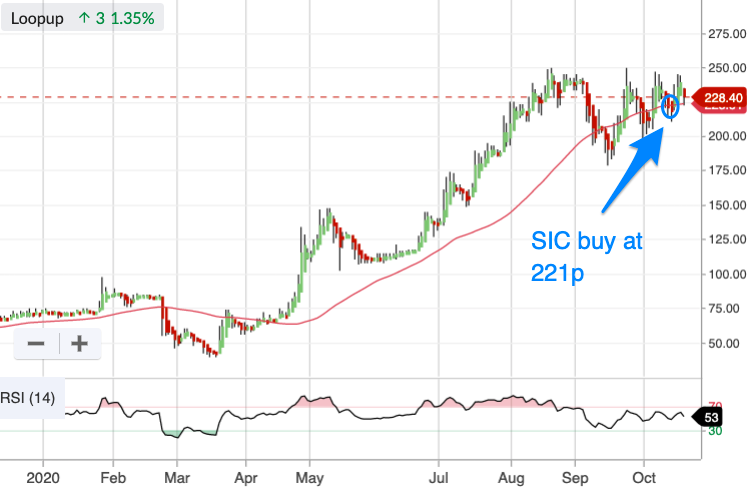
Loopup (LON:LOOP) was pitched to the Stockopedia Staff Investment Club in early October and shares were purchased on Monday 12 October at 221p.
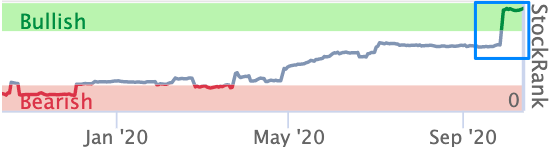
LoopUp has seen a big gap up in StockRank this past month, from 59 to 93. This jump in Ranks is driven by some eye-catching half-year results which show it has directly benefitted from accelerated work-from-home trends in the first half. This performance was covered in Paul's recent SCVR update, here.
The group generates around £50m of annual revenue but is targeting a multi-billion dollar market. This opportunity, coupled with recent strong trading, has led to impressive one-year relative strength of +301%.
There might be profit-taking along the way - Jupiter Asset Management has been selling shares - but if the group can translate its 'healthy new business pipeline' into additional H2 sales then there is a fair chance of further upside surprises.
This is not a given though. Analysts are being cautious and the company has disappointed in the past. It's a Highly Speculative software company benefitting from a once-in-a-lifetime opportunity, but can this temporary tailwind be converted into more lasting value?
TLDR;
LoopUp's half-year results are striking - its best ever by some distance - so can the group use this as a springboard to future success, or is it just a flash in the pan?
- Bull Points: LOOP is a covid beneficiary, it is targeting a growing c$2bn professional services remote communications market, and has an influx of lockdown cash being deployed into a potentially a Microsoft Teams opportunity that takes its total addressable market to an estimated $10bn by 2024.
- Bear Points: The company has a patchy profitability record and there is the threat of technological obsolescence (for example, the rise of Zoom). The group's pivot to a recurring revenue model might reduce near-term revenue (but improve visibility). A COVID boost now might lead to moderating growth rates later. It is an illiquid, volatile small-cap, with a premium tech valuation. There may also be profit-taking after a recent strong run.
Profile
Loop Up is listed in the Technology sector and makes enterprise conference call software that integrates with Microsoft teams to provide straightforward and secure external communication.
It trades at 223p, with an exchange market size (EMS) of 2,000 so liquidity might be an issue for some.
Opportunity Type: It is a Highly Speculative, Small Cap High Flyer currently benefitting from a lockdown boost to trading.
The opportunity beyond this is whether it can invest these profits into longer term, high return, profitable projects and take share in a growing remote communication market.
Its biggest upcoming project by far is a major extension to its flagship LoopUp product that will allow it to provide global cloud telephony via 'Microsoft Teams'. According to forecasts, this will increase its addressable market fivefold to $10bn by 2024.
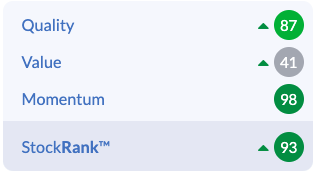
The StockRanks pick up on improving fundamentals, with the Quality Rank up by 35 and the Value Rank up by 22 over the past 30 days.
Business & Model
Company History
LoopUp provides a fully managed global service with customer support from 15 offices around the world. It is a Microsoft Global Partner with deep expertise in voice solutions, and has built a reputation for quality solutions, premium service and reliability over the last 15 years.
More than 5,000 organisations around the world use LoopUp’s global voice network, including 20 of the top 100 global law firms.
Clients have historically paid one-off fees for its services but LOOP is getting more business in recurring revenue. Its latest update says clients are typically signing up for 24-month contracts and that 30% of business now comes from committed term contracts.
Business Model
LoopUp removes pain points in corporate conference calling by providing cloud communication services, remote meetings functionality, and operator-assisted events.
Cloud Communication - LoopUp's Microsoft’s Phone System integration and premium voice network allows users to make and receive external calls from Teams.
Remote Meetings - LoopUp video conferences are simple for guests to join and audio is reliable. It’s available as a native app for Microsoft Teams, or as a standalone solution.
LOOP pairs the potential of collaboration software with the simplicity and reliability of traditional audio conferencing. No training or downloads are required for guests.
Operator-Assisted Event Calls - LOOP has experienced operators in the US and UK that manage corporate conference calls. The service is secure, reliable, and global, with high levels of call quality. It runs hundreds of Event Calls every month for some of the world's largest companies.
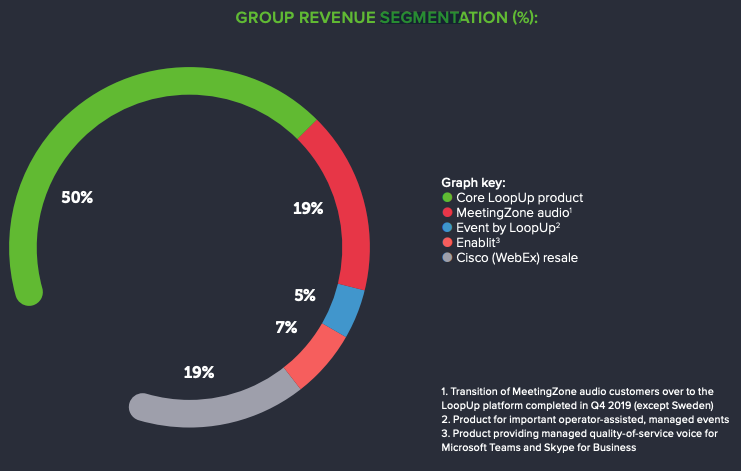
Source: Company accounts
Market & Competition
LoopUp states its addressable market size will be about $10bn globally by 2024. This is against their current TTM revenue of GBP 52m.
Wainhouse Research sizes the 2019 cloud telephony market at $13.7 billion, and projects growth to $25.8 billion by 2024. The addressable segment of particular relevance to LoopUp is cloud telephony integrated with ‘Teams’ UC platforms. This is forecast to grow from $1.5 billion in 2019 to $7.6 billion in 2024, a 38% CAGR. When combined with our existing professional services remote meetings market (approximately $2 billion in 2019 and $2.8 billion in 2024), this leads to a total addressable market of $3.5 billion in 2019 and $10.4 billion in 2024.
LOOP's target market is in large part determined by Microsoft Teams' market. Teams has seen a 70% increase in DAU since the start of lockdown.
They have recently landed a few major deals, with a magic circle law firm and a couple of top 100 legal firms. The magic circle firm may be rolling the solution out globally after a successful trial in a regional practice.
Competitors
The 'cloud telephony' space is relatively crowded. There are a number of competitors such as 8x8 and Microsoft itself.
LOOP's competition includes large, well-funded tech disruptors like Zoom that could totally revolutionise corporate communications with external guests. Although Microsoft Teams is entrenched in many corporations, and there are switching costs, this is a risk to be aware of.
Strategy & Competitive Advantage
Strategy
The group's strategy is to optimise the LoopUp product for the distinct needs of the Professional Services market, rather than a jack-of-all-trades approach for the entire market.
On this note, the group says in its FY19 Annual Report that it has 'an increasingly strong brand awareness in these legal, financial, and other client-led sectors, which account for approximately $2bn of the global $7bn market' and services 'more than 20 of both the world's top-100 law firms and top-100 private equity firms.'
And then there is the announced major extension to LoopUp flagship product to include global cloud telephony via 'Direct Routing' integration with Microsoft Teams. This is set to drive a five-fold increase in addressable market by 2024 to more than $10 billion
Other initiatives to generate profitable long-term growth include:
- Pod investment - LOOP is organised into team-based 'pods' for new business acquisition. The group expanded the average number of sales pods from 7.5 in 2018 to 10 in 2019 and opened new offices in Chicago, Dallas, Los Angeles, and Madrid. Going forwards it intends to increase sales focus on Professional Services 'for which LoopUp’s simple, reliable and secure product is optimised'.
- Product development - the heart of corporate strategy continues to be LoopUp product development to enhance the customer experience, with a renewed emphasis on optimising for the $2bn Professional Services market.
- Grow existing base - many customers acquired in recent years have transformed into major revenue contributors, reflecting the value of LOOP's proposition.
Competitive advantage
'Simple, reliable, and secure product' - Corporate clients want something simple, secure, and robust so that they can communicate seamlessly in private and with external clients. LOOP's strategy is increasingly tailored towards meeting this demand and it already has some top customers in the bag. Recent wins have gone on to become significant revenue contributors, suggesting they value LOOP's offering
Group management - co-founders, co-CEOs and c9% combined shareholders Steve Flavell and Michael Hughes are experienced in corporate finance and the VoIP software market.
Durable advantages? Using the moat framework - LoopUp has built up its own proprietary software and it also appears to be building a brand reputation for security in the Professional Services market. There are signs of switching costs, in that corporations take a long time to decide to switch communication vendors with the potential for risk to reputation if they do switch and get it wrong.
Financials & Ownership
It has shown strong sales growth over a number of years: Just under 40% CAGR of sales growth over the past six years. 46.4% sales CAGR over the past three years and 43% growth year-on-year as of the most recent interim update.
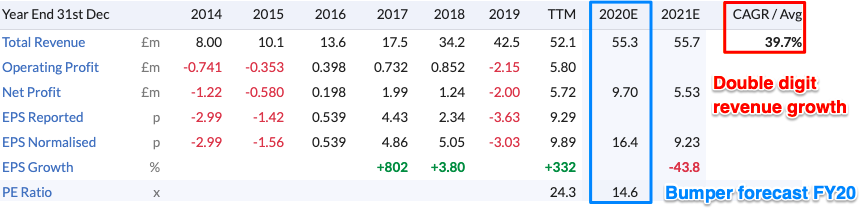
Brokers are forecasting c30% sales growth in FY20. This is high and above the 24% achieved in FY19 but less than the 95% the year before that (although this was boosted by a sizeable £61.6m acquisition).
Profitability, operating margins, returns on capital, and free cash flow have all been patchy in the past, so this isn't a slam dunk. Even though LOOP is benefitting from a one-off COVID tailwind, there is certainly execution risk.
Balance Sheet Strength - looks strong, with an F-Score of 9, a safe Z-Score, and a low M-Score. Net debt spiked up in 2018 as a result of its c£60m acquisition but was materially reduced to £5.3m by H1 2020 and stood at just £3m by the end of August.
Share dilution - There is evidence of share dilution in 2017, 2018, and 2019. This does raise questions regarding LOOP's organic cash generation in the past and is something to keep an eye on, but is also skewed by that large acquisition in 2018.
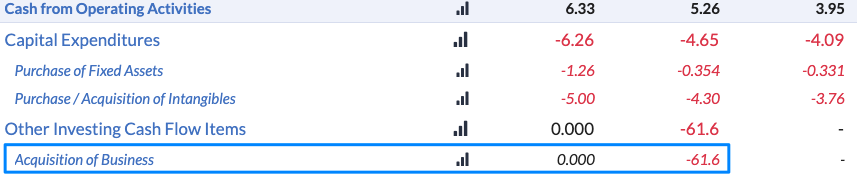
H1 2020 cash generation was strong, with £9.95m of net cash from operating activities and just £3.62m of capital expenditures.
Ownership structure of the company, and do management or founders have significant stakes? See here.
- Top 10 holders have 37% of the shares and are a mix of institutions and private shareholders.
- Nico Goulet - non-exec director - 12.56% shareholder and managing partner at Adara Venture Partners.
- Andrew Scott - angel investor - 12.02% shareholder.
- Jupiter Asset Management - Below 5%. Jupiter has been reducing its stake in the company.
- Stephen Flavell and Thomas Hughes - co-founders and co-CEOs own about 4.7% each.
Valuation
The company has a ValueRank of 41/100. This indicates it's reasonably expensive on historic data, but the Value Rank has increased by 22 over the past 30 days. This might be in part due to LOOP's increasing cash balance - up from £3m on 31 December 2019 to £8.28m on 30 June 2020.
LOOP's StockRank is further bolstered by an improving Quality Rank, up 35 over 30 days to 87. That paired with a strong Momentum Rank of 98 make this stock a high QM High Flyer.
The forecast PE Ratio of 22.4x is pricey but not by Software standards - see the 'Industry' vs. 'Market' bar below.
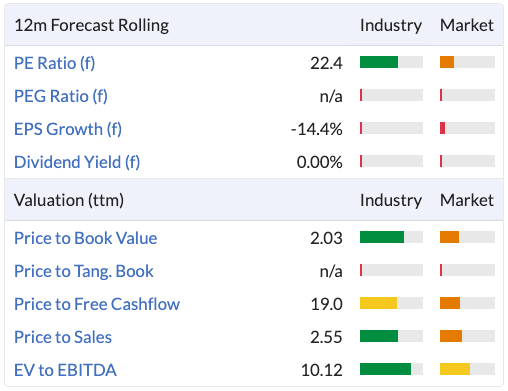
Forecasting LOOP's performance is complicated by an ongoing shift towards recurring revenue. This is a trade-off between higher sales visibility and lower pricing.
If the group can continue to gain share in a multi-billion dollar market, then 22.4x forecast earnings might end up looking cheap in hindsight.
LOOP is also valued at just 13.7x forecast 2020 normalised earnings. True, this is set to be a bumper year, but if the group can capitalise and use current tailwinds to invest in future profitable growth then that bodes well at current levels.
Ultimately, though, given the ongoing shift to recurring revenue, unknown length of time of current work-from-home drivers, and the only recently announced Microsoft Teams extension opportunity, forecasting LOOP performance is challenging.
Recent Trading
What is clearer is the strength of recent trading, with earnings per share up 1,164% to 13.9p. LoopUp reports significant revenue growth, margin expansion, high cash flow conversion, and the group's 'strongest ever new business performance'.
If LOOP could match that performance in H2, that would be 27.8p of earnings per share and an FY20 PE ratio of just 8.1x... But brokers are prudently forecasting a less strong H2 and full year earnings of 16.4p.
This leaves the door open for earnings surprises - the company itself says it 'enters the second half of the year with major new customer wins set to roll out' and a healthy new business pipeline - yet it needs to make just 2.5p of earnings per share to hit expectations.
Trends & Catalysts
Strong trading as a result of lockdown but also a longer term trend towards better and more frequent remote corporate communication.
Net debt is coming down - from £14.7m at FY19 to £5.3m at H1 20 and £3m just a month or so later.
Microsoft Teams - this major extension to LoopUp flagship product will include global cloud telephony via 'Direct Routing' integration with Microsoft Teams. It should increase LOOP's addressable market fivefold to $10bn by 2024.
Are there any catalysts could drive a rerating in the short or medium term?
It is possible that the market is underweighting LoopUp's near term growth prospects, given the extremely strong growth rates reported in the first half. The duration of this boost to trade is uncertain, however.
What are the biggest risks?
Valuation Risk - It is on a premium rating and, though recent results are strong, the previous track record is patchy. Covid may prove to be a temporary boost rather than a structural shift towards work-from-home.
Technology Risk - Technological obsolescence is a real risk. LOOP's differentiated strategy of targeting the Professional Services sub-sector and emphasising simplicity and security increases its chances of effectively competing against larger software competitors - but they're still out there. Microsoft could probably roll out of bed and squash LoopUp without even realising it.
Execution risk - LOOP has disappointed shareholders in the past and it has a patchy track record in terms of profitability and cash generation. There is a real risk that it fails to capture the opportunity facing it - at least in the eyes of investors.
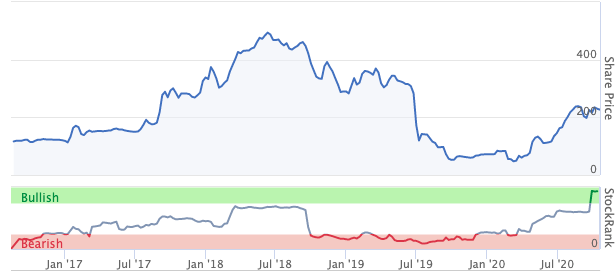
Institutional selling - Jupiter Asset Management has been reducing its stake in the company and this has been weighing on the share price.
Sentiment
Progressive Equity is the only broker covering the stock and its research is commissioned by the company. The analysts are enthused following a 'highly profitable and enormously cash generative' first half - but they have reduced their FY20E revenue by £1m to £56m to reflect the ongoing migration of large customers to fixed-price licence deals.
This would still represent c32% year-on-year top line growth.
Private investor sentiment at the moment is a positive thanks to the very strong half-year figures and subsequent StockRank appreciation. The community has been buying but Jupiter, one of LOOP's few institutional holders, has been selling. This may be weighing on the share price.
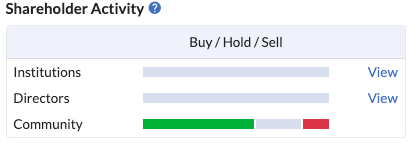
What would the person selling to us be thinking and who are they?
- Profit takers given LOOP's strong year-to-date share price performance.
- Some might question the historic lack of statutory profit and free cash flow generation.
- Others might believe LOOP is at risk of being outdone by a larger, better-funded software company.
- Although, on balance, the risk might be to the upside there are still unknowns - namely the duration of the current tailwinds boosting figures and the top line impact of a shift towards recurring revenue.
Conclusion
After the pitch, how did the investment club vote?
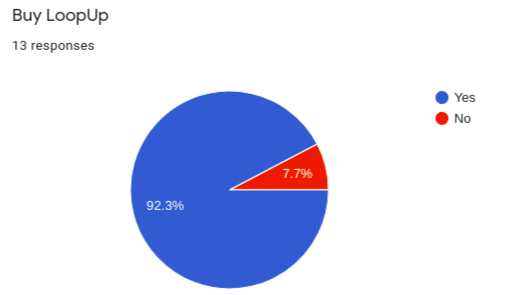
In the end, a clear majority voted to purchase shares at 221p, with strong recent trading figures outweighing historic losses.
As ever though, it's not a clear cut decision so if you have any insights or observations please do leave a comment.
Disclosure of interest - I hold shares in LoopUp
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
Compelling argument for Loopup (LON:LOOP) being oversold heavily on IC by Simon T. Precisely at noon today led to a big bounce. Having read his piece, I tend to agree. At current prices, I think market is baked in all worst case imo.
GLA
Where's the Moat?
other than client inertia, I'm struggling to see what the competitive advantage / niche is. The other providers could easily roll out a premium security enhanced offering and could afford to undercut Loopup (LON:LOOP) indefinitely. Takeover is a possibility but doubt any big player would overpay as they could develop their own product easily.
You could say that about most IT services. Even the Microsoft desktop isn't immune to this line of argument, losing market share to Chromebooks and other tablet type devices.
What one needs to remember is, the overall market is growing, so you can still grow sales and bottom line whilst losing share.
Very much admiring Ed's self-control in not saying "I told you so" :-)
RE: Loopup (LON:LOOP)
Pulling the numbers apart is a bit like pulling teeth (painful, but necessary) - I don't think it's possible to work out the full year breakdown, but given we know there are quite a lot of bonus pandemic earnings in there it probably doesn't matter. There's a £16 million one off windfall bonus in the FY numbers which means, at least, that they're less indebted than they were.
What we can look at are the figures for 2019, H1 2020 and the projected ARR for 2021 and see how the mix of business is changing. It's quite dramatic, this is not the same business it was a year ago.
That won't be accurate, but I reckon it's good enough (no guarantees, though, DYOR). The 2021 ARR can only be a projection of the full year, with windfall earnings stripped out.
The startling figure is the collapse in non-professional services (NPS) work. That's a combination of the fact that for most businesses Zoom is good enough plus a lot of those customers are facing very difficult times. I'd expected this to happen but not at anything like this speed - I guess times are tough out there. That drop - which was visible in the H2 figures - was the canary in the coal mine for anyone who wanted to see it.
Which leaves the professional services (PS) business which is going very well - but clearly can't compensate for the fact the company will have lost 40% of last year's business. That can't happen again because PS is now 70% of the revenue, up from 32% last year. If we factor in the 6% growth in PS and the 32% fall in NPS mentioned in the trading update that roughly gets us to the Numis forecast of £35 million revenue for next year.
Is the PS business at risk? Probably not, at least not immediately, as the customers in that space will tend to be sticky and the move to longer term subscriptions, while it reduces revenue in the short-term, will help with customer retention.
Should this have been flagged at the half-year? Yep, you'd have thought so. That was two months ago, midway through the second half:
This instability makes it difficult to provide more specific guidance on near-term market expectations beyond our July trading update, other than noting recent forex changes and continued momentum towards committed term contracts.
The July trading update noted merely that revenue tends to be H1 weighted, but otherwise was blank on current trading. And, at that point, it probably was too early to know much.
So how does this look now, as an investment proposition? Well, I don't think the 50% fall in share price was unwarranted. There's certainly the possibility of growth that was thrown out at the end of the trading update but it's cashflow not forecasts that drive businesses forward and Loopup (LON:LOOP) will almost certainly make a loss next year. Still, the stickiness of the PS customer base ought to make the Numis £35 million revenue forecast easy to achieve - and if it's missed then you have to reckon that the proposition is a bust.
Put it this way - having run these numbers I wouldn't buy more. On the other hand, if you believe in the PS business then you probably don't want to sell either. There's not much left to lose in the NPS business, at at the current rate of attrition that will be contributing a negligible amount towards earnings by the end of 2021. Overall it's a better business than it was pre-pandemic, with less debt and an enriched sales pipeline but also a baseline of lower but more sticky earnings.
You have to think that they should probably have raised money while the going was good, I'd much prefer to see them going into the next stage of development with a full war chest.
Could there be another profit warning? Well, not on the same basis. Something else would have to go wrong for that to happen. Which is clearly not impossible, but is also not predictable.
Hey ho, investing is a game that punishes hubris like no other. Nothing is ever certain and risk management is always essential. But I still don't like automated stop losses ... :-/
timarr
Thanks Timarr. Whilst I agree with most of the analysis, the ARR for next year assumes no new business, including the PoC with the bank going on now, which they may convert. You'd assume Cloud Telephony will bring something more into the hopper too. So I d argue that ARR is perhaps worst case.
Moreover, the PS sector with enhanced focus now, can only get bigger I'd have thought? With the permanent shift (perhaps!) to ways of working, I would've assumed a lot more of that pie to target, hence tap into that 2bn+ market.
At sub 50m market cap, will there be a bid from anybody in the sector I wonder? Is there anything proprietary worth bidding for? Who knows anymore. Sigh.
The Directors, as terrible as they are, have some skin in the game too, so I really hope they do something about current state of affairs. Ridiculous erosion of shareholder value, and the lack of transparency in the last few months is appalling.
So I d argue that ARR is perhaps worst case.
Not necessarily. The NPR and Cisco business could go lower than predicted. The PR business could come under attack from richer competitors.
I think the former's quite possible, the latter less so in terms of existing customers, who don't appear to be price sensitive. Could impact future growth though.
As a wise man once told me - no matter how far a share has fallen it can still go down another 100%.
timarr
timarr,
I'm not sure how you get the numbers you have for the breakdown of the 2019 revenue. The 20.8 for NPS looks very high to me.
I'm not sure how you get the numbers you have for the breakdown of the 2019 revenue. The 20.8 for NPS looks very high to me.
Hi dodge
You may be correct, it may be that I'm not comparing like with like.
However - Loopup (LON:LOOP) had total £42.5 million revenue in 2019. In their full year results they state that Professional Service revenue was £13.6 million and that Cisco revenues were £8.1 million. So, naively, subtracting 42.5 - 13.6 - 8.1 gets me to £20.8 million.
It's possible that some of the other lines they mention in the 2019 report, but not in 2020, should be allocated to PS rather than NPS. Those are "Event by LoopUp", "MeetingZone Audio" and "Enablit" which between them come to £13.3 million and are, I think, the outcome of acquisitions.
My guess is that some of those revenues should be allocated to PS rather than NPS but I can't see anything that allows me to do so intelligently. Certainly the FY20 H1 results seems to differentiate PS and Event by LoopUp suggesting the latter is in NPS. Enablit also looks like an integration capability so I'd be reasonably confident of allocating £5 million of that 13.3 to NPS.If some of that revenue can be reallocated then the fall in NPS isn't as great and, commensurately, the rise in PS isn't as great. I think I'd rather be seeing more growth in the target area than a lesser reduction in legacy business.
There's great fiction, and there's accounts. At least great fiction bears re-reading ...
timarr
I'm sure a lot of investors are utterly baffled by the way LOOP have presented their results. But if you look at the chart on p7 of the 2019 annual report, they have £7.6m for NPS. In fact, the 2021 ARR numbers look like an acceleration of the trends seen in the 2017-2019 period. It seems that a lot of NPS customers signed up in 1H 2020, and then decided to go elsewhere, which is perhaps the main disappointment.
I'm sure a lot of investors are utterly baffled by the way LOOP have presented their results.
Indeed.
The 2019 results show £13.6 for PS and £7.6 for NPS which, plus £8.1 for Cisco gives a grand total of £29.3 million, which leaves £13.2 million unaccounted for. Which is pretty much the same figure I previously calculated for the other lines. So the relative performance of the PS and NPS lines depends largely on how those are allocated.
If all of the unallocated revenue is switched to PS then that shows that PS revenue is forecast to fall next year and probably this - which I don't think makes any sense on any reading of the trading update. But who knows?
It seems that a lot of NPS customers signed up in 1H 2020, and then decided to go elsewhere, which is perhaps the main disappointment.To give the management a tiny bit of credit, they've been clear that the PS side is the core to the business. The NPS boost in the first part of the pandemic was a windfall, presumably companies that were desperate to upgrade their video conferencing capability and weren't too particular about price at the time.
Basically, if you're competing with Zoom et al you're in a commodity market where scale is critical because price is the key differentiator along with security and functionality as secondary differentiators.
timarr
Tim,
That is an excellent view (if accurate).
I have to admit that, despite having a telco background, I still have not gotten around to working out precisely what LoopUp (LON:LOOP) actually do. So what follows is just based on your breakout.
This looks like a company that could post-rationalise it's strategy as :
I have no idea whether this may be :
a - totally inaccurate.
b- accidentally accurate. (Covid accelerated the demise of NPS & the growth in PS)
c - The original plan all-along (but accelerated by covid)
or
d - something I have not thought of.
What does seem apparent to me though (and I have to repeat my almost total ignorance of this company) is that this business is a substantially different beast than it was thought to be a few days ago,
It is starting to intrigue me now - but I am doubtful that the past numbers can be much of a guide,
Hi Gromley
What does seem apparent to me though (and I have to repeat my almost total ignorance of this company) is that this business is a substantially different beast than it was thought to be a few days ago,
I don't believe it is. However, this then becomes a discussion about the story rather than the numbers - so to be clear, as far as I'm concerned it's the numbers that tell the true story, not management spinning narrative webs, which is why I'm trying to figure out what the underlying financial trends are.
However, to discuss the story - in simplified terms the two lines of professional services and non-professional services can be considered as two different types of business.
NPS is operating in a commodity market where they're competing with Zoom, Teams, et al. That market is characterised by low prices and high volume and very low barriers to entry - essentially a laptop and a broadband connection. The majority of my clients use these platforms and they're perfectly adequate for most situations.
PS is operating in a higher value market where the customers require high quality and guaranteed security. There are higher barriers to entry - basically building out a switching and routing system and providing access to it without requiring internet or mobile connections.
There is a small, but very valuable, subset of customers who want that type of service - if you're a lawyer or a private equity fund manager you don't want your call cracking up at the point someone is making a critical point. So in the PS market customers are less price sensistive and ought to be less likely to churn.
However, the stickiness of PS customers comes at a price in terms of cost of sales. This isn't an easily reversed decision so customers will tend to spend more time analysing, probing and trialling the solution.
So, to my eye, the underlying story that the LoopUp management are telling has the ring of truth. The early part of the pandemic saw customers signing up for the LoopUp NPS pay-as-you-go service without much thought or analysis. They then found they were paying for a premium service that they simply didn't need and migrated away to the commodity platforms. Existing NPS customers went with them because it became apparent to businesses that Zoom was perfectly adequate for what they needed.
Basically, after the initial boost to NPS volumes the pandemic has accelerated the decline in that business.
On the other side there's also a boost to the PS side but that's a much slower and more difficult sales cycle. Revenues are growing, customers are moving and sticking but it takes time - much more time than transient shareholders are willing to allow.
All of this is happening as Loopup (LON:LOOP) moves from a pay-as-you-go-service based on minutes to a subscription model. In the longer term, if we assume call minutes will drop anyway as the pandemic ebbs then it's the right move amd promotes customer stickiness. In the short term it further reduces earnings.
So much for the story. The question is, do the numbers match it? And if they match it, is there an underlying profitable business here? And if there is, is it one that better funded competitors could come in and steal?
And even if there is a potentially valuable business here, do they have the capital to exploit it? If they'd raised money three months ago I, like, many other shareholders would be even more unhappy than we are - but the forward business case would look better and they would be funded to scale up their sales efforts.
Anyway, that's enough effort devoted to this particular topic. There comes a point when it's simply easier to think about something else :-)
timarr
I think you've been a bit unfair to Teams. It is almost zero comparison to Zoom. It's like comparing a cheap £15k hatchback to a premium sport estate vehicle.
Sure they both meet their design briefs, but one has much more capability, capacity and premium 24/7 support. I don't think there's much in the Loopup (LON:LOOP) solution that can't be achieved in Teams except the dial in / out functionality. But that secure dial in / out facility could be a gold mine.
Happy to be wrong.
I did buy in to Loop on Wednesday - I think the dial in / out capability is where the money is if marketed properly. Remote meetings is not what I would personally put my faith in.
I sold Loop Friday, I didn't spend enough time researching the sales mix and got burnt for that. I might look to buy back after more research and understanding of the sales model.
Also, as I stated Friday, there's loads of articles on Stockopedia that states selling on profit warnings is most often the right thing to do, even if some stocks do bounce back fast.
Also, as I stated Friday, there's loads of articles on Stockopedia that states selling on profit warnings is most often the right thing to do, even if some stocks do bounce back fast.
It's ...
The Profit Warning Survival Guide" ... you can catch up on all the content in our quick read eBook, 30 minute Webinar and accompanying set of slides.
Strongly recommended, it's saved me a ton of money.
timarr
Thanks for sharing :)
I think the non professional services market has plenty of scope, depends on how it's delivered.
Most companies have tons of complicated Cisco and other vendor's kit, they're paying network engineers to maintain VOIP dedicated VLANs, providing QOS limitations on other services to maintain those VLANs - but I think the Loop solution can help remove a large chunk of that complexity. Get rid of all those silly phones on desks and other dedicated video conferencing terminals and just have people with £100 headsets that USB directly into their workstation.
That's a little bit brutal. I was thinking about to enter when stock was at 220.
Now it did fall to 78p.
I am thinking, is it worth buying it now or it will drop more..
Yes - I also have problems logging into Stockopedia. At this stage it is an annoyance rather than a major problem. Hopefully it does not get any worse.
Interesting piece on the Bloomberg news flow about the Salesforce acquisition of Slack. I would guess that the video conferencing market will eventually be dominated by a few large players. It will also be interesting to see if the free secure messaging apps (e.g. Signal) make a move into the market aimed at the super secure users – perhaps on a subscription basis.
For what it’s worth, I don’t use automated stops on share trading platforms as I see little value in such an arrangement. Gap downs and platform limitations will probably mean that they won’t get you out during a meltdown like the Loop situation today. Much better in my view to have your own stop rules which you can execute when the market can absorb your trades.
Trading Statement today - guiding expectations moderately lower.
"We are seeing an acceleration of churn in non-PS sectors, where our Meetings capability is less differentiated and competition is more intense. Here, we expect trading to remain challenging, although this now represents just 14% of total LoopUp Platform2 revenue.
In light of this, the Group now expects FY20 revenue to be no lower than £50 million (c.18% growth on FY2019) and EBITDA to be no lower than £15 million (c.134% growth on FY2019), moderately below current market expectations."
Might be a case that the market already 'sold on the rumour' ... but we shall see.
Ouch - brutal reaction - -38% at the open.
Ouch - brutal reaction - -38% at the open.
Ouch indeed :-)
Interesting, though. If Loopup (LON:LOOP) are seeing attrition in their non-PS business exactly how painful is it out there?
Looking at the bad news around I can't help wondering if markets are getting ahead of themselves. The Spending Review has an 11% fall in the economy, 2.5 million unemployed next year and economic scarring until 2025 and the only discussion on Stocko was about CGT ...
I know markets look ahead, but there's an awful lot of optimism priced in right now.
timarr
It probably the first of many many Covid trades unraveling.
BSV
Well that is a kick in the teeth. I'm trying to work out how you get from £32m revenue in H1 to c. £18m in the H2? Despite the factors they cite it is difficult to account for such a huge slow down in revenue progression. As I write the share price has collapsed 43% to 88p - investors will treat this as a profit warning - and have been taught to sell immediately. LOOP is now priced at less 1x annual revenue.
First up, it has regularly been demonstrated I’m an idiot. not investment advice and don’t listen to me!
Second, went long £LOOP today. I work in IT for a major services provider and use Teams extensively. Never heard of this company at the start of this year, but I’ve seen Loop’s solution deployed as part of Teams and stand-alone recently and have been impressed with it through both interfaces.
Currently, the all too frequent response when attempting to access Stockopedia.com
The facility to contact the support team is also u/s.
Bonitabeach
It’s not just me then. I did report it some weeks ago but since then it is getting more frequent.
That's strange. I've never had an issue with connecting to stocko
Happening more frequently lately, only started about 2 months ago, not just on one device either happens on iPad and pc, Apple and Windows.
To be clear this is not when going into Stocko, it occurs when already on the site, you click on say a share or anything and get this message about the server.
Fantasy funds trading did not work some days last week, all trades were lost.
not sure if this has been discussed.... my firm uses Teams & it is excellent. Virtual conference calls are simple, far easier than Zoom which seems clunky in comparison. If we are using Teams for 1-1 v or larger group meetings both internal & external does this negate the need for £Loop type services as we are not using a phone system ?
I believe Loop adds the ability to dial out using Teams, but also for people to dial in to your Teams meetings.
What a gent Mr Ed is. If I remember he was the only member of the investment club not to vote for a 'buy' recommendation. So, I am particularly impressed that he has come back to the post to inform us of the 'stop'. And probably the best course of action.
Meanwhile, for the 'die hards' a reward-risk table:
... For die hard believers who are aggressive short term traders: A stop below 153.5p and hoping to hit 'green' reward-to-risk ratios corresponding to the Fibonacci extension levels. Remembering, of couse, that you have resistance at ~197p and ~176p.
... For a scaredy-cat skeptosaurus such as myself a successful re-test of yesterday's low might add confidence? Or even a break above previous automatic reaction at 185p?
M.
I see LoopUp (LON:LOOP) are now up 5%, that is what usually happens when I sell out.
The Investment Club sold Loopup (LON:LOOP) today as it hit our stop loss level.
Just as it's become a Stockopedia Super Stock Ed?!?
@maddox - yes indeed. We have our investment philosophy. We run volatility based stops using the RiskRatings and they have served us well. Nothing wrong with the company, but there’s something wrong with the stock right now - as per our risk management principles.
just joined, where is this portfolio to view, as i cant find it?
Ed,
Does Stockopedia Staff Investment Club now hold 10 shares?
Or are there some I missed or some others that have not been reported yet?
There was 8 in the original report plus I have seen Reach (LON:RCH) and Novacyt SA (LON:NCYT) reports.
Hi herbie47, at my last count (if you ignore Loopup (LON:LOOP)) I believe the Investment Club currently holds 12 shares but I could be wrong because although there have been many articles published on the homepage informing subscribers which shares it has bought, I haven't come across any articles on the homepage which informs subscribers which shares the Investment Club has sold.
These are the shares which I think it currently holds:
B&m European Value Retail Sa (LON:BME) Best Of The Best (LON:BOTB) Codemasters Group (LON:CDM) Ergomed (LON:ERGO) Ig Group (LON:IGG) Novacyt Sa (LON:NCYT) Reach (LON:RCH) Shanta Gold (LON:SHG) Sylvania Platinum (LON:SLP) Venture Life (LON:VLG) Volex (LON:VLX) Wey Education (LON:WEY)
Fortunately, I have never held Loopup (LON:LOOP) so todays drop doesn't affect me but I never saw any article on the homepage informing subscribers that the Investment Club had sold Loopup (LON:LOOP) .
Hi Ed,
I imagine a lot of subscribers read and follow the actions of the Investment Club. As a suggestion, I was wondering if it would please be possible for the Investment Club to publish updates, either on the homepage or even a brief paragraph within SCVR informing subscribers of when it has sold a share from its portfolio?
As an observation, I couldn't help but notice over the past few months since the inception of the Investment Club, but due to the the shares which it holds, as each month goes by it looks more and more like my own portfolio, which is reassuring.
We were stopped out of Shanta Gold (LON:SHG) recently but we also now own a position in Polar Capital Holdings (LON:POLR) which I pitched recently. I haven't written up my notes due to time constraints, but I hope either I or another will.
I think POLR is overdue multiple expansion.
Many thanks Ed for the update.
Polar Capital Holdings (LON:POLR) has been in my Watchlist portfolio for a couple of weeks due to its low PER of 12 amongst other metrics. However, because its price is currently around 12% above its 50 day MA, I have been waiting for a pull back before I buy. Last week I almost sold some of my Liontrust Asset Management (LON:LIO) to raise some funds to buy Polar Capital Holdings (LON:POLR) because of the fact that LIO is on a much higher multiple (and 25% of my portfolio) and also to spread my rise in the financial sector because I also hold Jarvis Securities (LON:JIM) .
Hi Logical David, Thanks for that but they did not buy Volex (LON:VLX) but it was pitched. I thought they would be stopped out of Shanta Gold (LON:SHG).
I do hold 7 of those, unfortunately LoopUp (LON:LOOP). Some I held for a while such as Sylvania Platinum (LON:SLP), IG Group (LON:IGG) and Codemasters Group (LON:CDM). I looked at Wey Education (LON:WEY) but the spread is over 10% at times.
Yes herbie47, you are not wrong. The Investment Club did vote for VLX but when it came to a head to head vote between Volex (LON:VLX) or £BME , the Investment Club voted in favour of B&M. by 7 - 6 votes. I believe at some point VLX will be included within the IC portfolio.
Yes I think you are right about Volex (LON:VLX) Ed is keen on it and I think it will be repitched soon.
The Investment Club sold Loopup (LON:LOOP) today as it hit our stop loss level.
I absolutely detest automated stop losses. You put hours of research in, think through the opportunities and the threats, buy some stock and then the market has one of its periodic glitches - in this case "OMG a vaccine's here, everyone's going back to the office tomorrow and no one is ever going to use video conferencing ever again, sell, sell, sell" and the shares are thrown overboard when, rationally, you should probably be buying more.
John Lee has the best approach to this I've seen - he review and sells if the company falls 20% below his buying price unless the market as a whole is having a seizure. In which case he makes up his own mind. You need mental discipline to do that, but you don't get caught by temporary spikes down in price.
It's worth noting that the research on stop losses shows that they work - for less experienced investors:
https://oro.open.ac.uk/44069/1...
"...this paper shows that stop losses used as part of investment decisions are an effective tool for inoculating against the disposition effect. We also show that investors who use stop losses have less experience and that, when not using stop losses, these investors are more reluctant to realise losses than other investors."
Ultimately stock investing is about risk and reward. If you take time out of the equation then the odds are stacked in favour of long investors. Stocks can only fall 100%, they can go up to infinity. Ditching companies whose actual performance fails to meet expectations is fine, ditching companies because the market - aka a bunch of algorithms and itchy fingered day traders - has dropped isn't.
At the moment analysts' forecasts are expecting a big fall in earnings next year as the pandemic effect wears off. Is that realistic? Will competition start to eat into margins? At what point will the costs of customer acquisition start to rise and act as a drag on growth (they're insanely low right now)?
I don't know. Not a clue. We should expect a lot of volatility over the next few months, we're clearly on the path to a speedy vaccine deployment which will whipsaw sentiment and the share price all over the place. Realistically it'll probably be two years before we know how valuable - or not - Loopup (LON:LOOP) actually is.
But the worst case, from here, is clearly above the baseline 60p or so it was trading at pre-pandemic. It's a far more valuable company, with less debt, better product and more paying customers, most of whom aren't in price sensitive industries and many of whom are switching to longer term contracts.
Anyway, time will tell. If the fundamentals were to change I would sell in a shot. But they haven't, not yet.
timarr
@timarr - I always respect your opinion, but generalising negatively on the use of stop losses without respect to portfolio, strategy and environmental factors is a bit reductive.
The club had positioned itself aggressively into high QM thematic shares, most of which have done well. If stops are being hit on shares in that strategy, the capital can be redeployed into areas or themes in the market that are actually working.
The opportunity cost of holding a share for 2 years that you don’t necessarily have high conviction in is great. Especially in a portfolio that is concentrated - the club targets 12 to 16 holdings.
We lost 30% on LOOP - it’s a highly speculative small cap. I’m sure it may bounce back... but do we have higher conviction in other shares given the market rotation? Yes.
PS - There’s nothing to stop it being re-pitched in another meeting.
Hi ed
I always respect your opinion
And I yours. But to be clear, I was specifically referring to automated stop losses. I made no comment on stop losses in general.
I profoundly dislike automated stop losses, particularly when applied to volatile small caps. They can easily get triggered during bouts of market instability which don't signal anything at all. The best research I've seen on stop losses is Klement's whose stop loss strategy even on a "fast-out" strategy is averaged over 3 months.
Personally I think the stock pitch series is hugely valuable for subscribers. There are too few real-money portfolios being described and everyone only ever talks about their successes - one of the reasons Paul Scott is a breath of fresh air is that he doesn't only dwell on the highs, he also discusses the lows.
But if you're going to do this then you need to at least explain (or reference) the logic to the selling decision when you announce you're out. Because 2,500 words on the analysis leading up to the buy decision (at 221p) versus 12 words on the sell (at roughly 155p) isn't exactly equivalent. If I was new to investing I'm not sure I'd take the right message from that without some more explanation.
timarr
It’s a club with a risk management approach agreed in advance. The stop loss rule was outlined in the original post. I don’t believe we need to write extensively on it. I just felt it right to update the community that we are no longer long.
“Run your winners, cut your losers” is the most profitable maxim for private investors to heed. The vast majority of PIs do not heed this at all. Avoiding the disposition effect and protecting capital by using a hard stop on the purchase price is just one way to force your hand into cutting losers.
If you’ve bought LOOP lower - congrats, you can run your winner. Our decision to sell out doesn’t change the investment thesis. It’s a risk management decision - not a fundamentals driven sell decision. It’s important to differentiate.
Run your winners, cut your losers” is the most profitable maxim for private investors to heed. The vast majority of PIs do not heed this at all.
You're telling me this? :-)
I found the rule I think, eventually, through the magic of Google:
https://www.stockopedia.com/co...
We also have two automatic sell rules:
A technical stop loss based on the purchase price according to the risk rating of the stock (Conservative - 12%, Balanced - 15%, Adventurous - 20%, Speculative - 25%, Highly Speculative - 30%). More volatile stocks need more wiggle room.
A fundamental stop loss - as soon as the StockRank falls below 50.
So, Loopup (LON:LOOP) was sold because, as a Highly Speculative stop it fell through the -30% technical stop loss. Fine.
timarr
@timarr - of course not telling you this... you have written biblically on behavioural biases... it’s for the lurkers and more generally to back up the case !
I find this easier said than done, even well performing shares such as Games Workshop (LON:GAW) and £SYL if you study their charts, have had huge corrections of around 50% this year. When do you sell? Some people use trailing stop losses so they would get thrown out of many successful shares.
LoopUp has a volatility of 91.5% according to Stocko's data.
I think stocks with a volatility greater than 50% are probably not suitable for an investment club approach. You can't find a sensible stop-loss (probably set it at about -99% if you did it!) and they need a different kind of mindset.
For the record, I do not hold. At least not yet.
If you look at the Fibonacci retracements from the lows in March:
- Between 17th March and end March the retracement came back to 50% of the move
- Between 1st April and 4th June the retracement came back to 38.2% of the move
- Between 4th June and 15th September the retracement came back to 38.2% of the move, forming a low at 182.5p (now broken). There is a 50% retracement level at 153.15p (which might yet hold).
- If you re-draw the position to between 4th June and today then the recent fall has broken below the 61.8% retracement (162.75p) and fallen to 160p.
If you look instead at auto support and resistance lines there are:
- Support at 197.6p, now broken forming resistance.
- Support at 176p, now broken forming resistance.
- Support at 104p still in play.
- Support at 39p (the March lows) still in play.
More positively On Balance Volume is holding up reasonably well. And Accumulation-Distribution has also held up well. Essentially the volume signatures are not showing capitulation at all. FactSet based EPS forecasts show rising future EPS.
So, looking for:
- Support to hold at either 153.15p and if that breaks 104p, and if that breaks 39p
- Some news event or a trading statement?
This move lower might simply be a mix of lack of news, waning sentiment becuase of lack of news, and typical small cap price behaviour?
M.
Has today's news changed anything for anyone regarding £LoopUp? Interesting conundrum. I personally think great value now for a semi permanent shift in working patterns.
Hi Pokiry,
Essentially, it rests on whether you think Loopup (LON:LOOP) 's business model rests solely on Covid-19. If I thought that was the case, I wouldn't have invested in Loopup (LON:LOOP) in the first place. That's not to say that Loopup (LON:LOOP) hasn't benefitted from Covid because it clearly has - it has accelerated a trend that was already in progress and pushed it further and faster than otherwise would have been the case. However, I don't foresee us returning to the old mode of working, face-to-face meetings are too inefficient in time and too costly.
Also, their new Direct Routing proposition is probably Covid agnostic, or would probably benefit from having more people back in the office, to aid roll-out.
But that's just my view, I wonder what is Stockopedia's Staff Investment Club's verdict?
Hi Maddox
That's not to say that Loopup (LON:LOOP) hasn't benefitted from Covid because it clearly has - it has accelerated a trend that was already in progress and pushed it further and faster than otherwise would have been the case.
I've been pondering this a lot in recent weeks, and not just about LoopUp. Someone recently - it might have been Philip Jourdan in last week's excellent piworld video - noted that we usually overestimate the pace of change in the short term but underestimate it in the long term. CV-19 has, for some companies, dramatically foreshortened those timescales.
A lot of small companies have great ideas and great technology but never succeed in becoming commercially viable because they can't get the funds to get scale - because they can't get the scale to get funds. They're trapped in a Catch-22 situation. For LoopUp and a number of other companies CV-19 has generated both scale and cash to allow them to bridge the gap between short-term and long-term.
As you say, none of us know what the future will look like, but I'd guess (for which read, I have no evidence) that it'll be a mix of home and office working with probably a lot less business travel than in the past. You only need a couple of people remote, especially clients, to require video conferencing.
None of that says anything about where Loopup (LON:LOOP)'s price will settle - I don't know, and nor does anyone else really. But I'm pretty confident that in 5 years time the price will be above where it is today, if it hasn't been taken over before then.
Personally I'll happily trade gains on a few Covid play stocks for a half-way normal life. There's no point making money if you can't spend it on the people and activities you want to.
Cheers!
timarr
Hi Tim,
Yes, this has been my direct experience. As I mention above, my firm recently conducted an employee survey into their working preferences post-Covid. Three choices - Would you prefer to work in the office most of the time? Would you prefer to work from home most of the time? or Would you prefer to mix home and office working? About 170 responses - almost exactly a third for each. Which equates to half preferring to be working from home a significant part of the time.
However, we had already taken out a floor in our head office, reducing from three to two floors, prior to Covid, a 33% reduction in floor space. The transition to WFH was already underway - what Covid has done has moved the dial further and made it totally acceptable and confronted the fears about a drop in productivity.
Cheers Maddox
HI Maddox, Thanks for your insights. The last 9 days, has seen further vaccine news followed by what is now a severe drop in the share price for LoopUp. Perhaps a big seller like Jupiter.
The more I look at it, unless I've made a complete mistake here, the market is completely mis-pricing this?
Regards
P.
Hi Pokiry,
I agree. The way I conceptualise it, a share has two key properties Value and Price - Value is intrinsic to the business and its prospects whereas Price is driven by sentiment. Nothing has changed to alter LOOP's value. Sentiment has changed because the chart trend has faltered and the Chartists and Momentum Investors have taken profits. This was caused by the Pfizer announcement of an effective vaccine on 9 Nov, that probably triggered their Stop-losses.
The investment rationale is unchanged it's just got better value as those seeking short-term/smaller profits have moved on.
LOOP's posting of tech vacancies is a useful indication that LOOP is growing at pace - those roles will be required for customer integrations. We cannot expect firms to be give us a running commentary and we already know that H2 is very likely to be every bit as good as H1. So, essentially nothing of importance has changed apart from Mr Market offering us a cheaper price to buy more shares.
Just my opinion of course, we all have to make our own investment decisions.
Regards Maddox
The more I look at it, unless I've made a complete mistake here, the market is completely mis-pricing this?
We know the historical earnings are meaningless. With a lot of pandemic stocks we know that the current earnings are a windfall and their future success depends on how wisely they spend it. With Loopup (LON:LOOP) it's harder to judge.
You'd think that there'll be a partial reversion to office working eventually but it's not clear to me that that means a big drop in video conferencing. You only need a couple of people to be out of office to need remote communications. Before we might have phoned people, but that's not going to happen in future.
It also looks like corporate travel budgets for 2021 - which are now being set - will be around 50% of the 2019 level. So we know there's going to be a lot less face to face meetings for significant time to come.
Of course, none of that speaks to Loopup (LON:LOOP) specifically. Maddox is your man there. I'm not a great one for making any predictions about price movements - there are too many variables to provide any level of certainty. But I do think the odds of them being undervalued now are greater than them being overvalued. The downside from here is unlikely to be great, the possible upside is significant.
timarr
Worth noting that Zoom dropped 17% yesterday. It might be that market sentiment is backing a 'return to normal' as far as workplace meetings are concerned. Despite yesterdays glut of big risers there were also a lot of big fallers that may have been priced for ongoing Covid problems (e.g. Ocado which fell 11% just after I bought it!). The gold miners had a bad day too as the gold price fell. There could be some wild price swings over the next few days in all directions. Mainly good ones I hope, but it might take a while for Loopup (LON:LOOP) and Zoom to recover.
Hi Jack,
Excellent article & excellent commentary. Can i ask how you decide on what to write on, is it your personal interest or editorial? I suspect like Paul, writing up findings is an excellent process for thorough analysis. Do you use a checklist to cover the same areas each time for each stock?
Thanks
J
Hi John,
Great question - for the Investment Club, we use a couple of screens. Maybe we'll cover them in more detail in later posts. Ed gives a good primer on some of the rules in the first post (here).
Right now we have some more recent SIC buys covered (NCYT and LOOP, both in October) but we also have some older pitches that we would like to get around to publishing.
The stocks covered in this series generally have a StockRank of above 75 and a market cap of more than £20m. Any company that qualifies can be pitched, so beyond that it is a matter of preference. We try to focus on companies with clear catalysts when we can.
We do use a template to research the stocks - we're continuing to refine it actually, but it's proving very useful in making the research process more consistent and methodical. Each company is different, so we do modify the template or go into greater detail in certain sections depending on the company and opportunity.
I personally find writing up the pitch a great way to ensure a certain depth of research. It keeps you honest!
If there is demand for more posts about the SIC approaches to stock screening and analysis, we'll be happy to publish.
Cheers,
Jack
I don't get what this offers over and above Teams native stack? Is it just the PSTN connection or is there more to it?
Maddox answered this below - effectively Loop replaces the requirement for your own organisation to connect to a PSTN if I understood his point properly. Also, whilst Teams natively allows dial in over a phone line, it appears Loop offer some enhancements in end to end security via their VPN.
Note: Taken from my understanding of the Maddox posts and put here to answer my own question so as to prevent others from repeating information already available below in response to me :) My understanding might not be correct.
Hi IGotPoesJacket,
Yes, but let me try and make it clear. Firstly, 'Direct Routing' is an adjacent market space to their online conferencing propositions. It just so happens that they already have in place the perfect technical architecture for this new opportunity - that has been created by MS opening up MS Teams for telecom integration by third parties such as £LOOP.
Currently, most MS Teams users - use it internally for staff comms, voice, email, instant messaging, internal conferencing. Then when those staff want to make an external phone call - they pick up their desk phone that will be separately route the call via a physical PBX box out over PTSN lines to the external party.
Direct Routing is an integration of Teams with a virtual PBX that routes the calls to the telecoms provider to the external party. In this way external calls can be made directly from Teams. The Calling Tariff is typically cheaper than the PTSN provider for domestic and international calls.
There is an additional point that I haven't mentioned previously - OpenReach is looking to phase out physical PBX and move all UK companies to their VoIP Network by 2025. This will force the migration away from PBX and drive adoption of Virtual PBX services like LOOP.
Ok, my company lets me dial out using Teams, I didn't realise there was a whole complicated layer of "stuff" needed in the middle, I assumed Teams did it natively.
Thanks for replying and explaining this to a simpleton :)
Hi IGotPoesJacket,
This is a totally new market space - so we're all simpletons here - nobody knows hows this will play out, so we need to explore all the angles. What on the face of it might be a naive question might in fact be the most penetrating. I'm putting my understanding out there to be shot down, queried or confirmed by those in possession of greater knowledge.
Nothing worse than someone who stays shtum and then tells you 'yer i knew there was something wrong with xyz firm' but didn't mention it. So the contrary view is often the most valuable but, let's be honest not the most welcome.
I've got skin in this game so keen to understand the risk/reward so please don't hesitate to share your thoughts.
Thank you again Jack for some more great analysis.
I was just wondering if any shares have been rejected yet by the club? If so it would be useful to see the analysis on these too if possible?
Thanks
Tim
@TraderBlade - actually both Novacyt Sa (LON:NCYT) and Loopup (LON:LOOP) were pitched and voted as buys in the last meeting. Normally there are 2 pitches, but only one makes it through. We're planning on writing up both successful and unsuccessful pitches after every meeting going forwards... but unsuccessful pitches from our historic archive might not make it through to publication.
It's actually quite a lot of work to get the rough pitch notes well written enough for publication !
Hi Ed,
If you can release the pitches i think that would be excellent output.
I try to now use analysis from selected sources & people as the first line filter, then only research further if the company suggested meets my own criteria. Pitch output from the stocko club would no doubt be good quality & i suspect very useful to most readers of these forums.
These deep dives are excellent idea generators especially with the quality comments, which often elicit contribution.
Excellent analysis. If this was rolled out more widely it would deserve a premium sub, possibly through a sub site with separate security.
Let's have a closer look at Loopup (LON:LOOP) 's competitive positioning.
On the face of it web conferencing solutions all look pretty similar. However the other providers' IP communication is delivered over the top (OTT) of third party broadband where service quality cannot be managed. Loopup (LON:LOOP) carries its audio channel over higher quality assured PTSN or its own quality managed virtual private network. So Loopup (LON:LOOP) has a very different underlying architecture in order to deliver the higher quality experience. It is arguably technically superior and has high security accreditation (ISO 27001). These differentiators are important for their target clients in the professional services sector.
ZOOM, Webex, GotoMeeting, etc are all software products whereas Loopup (LON:LOOP) is more service-oriented. Also, their products are all feature-rich whereas Loopup (LON:LOOP) is deliberately simple and easy to use. Again important if engaging with external clients, or potential customers.
Theoretically it's possible that any business could look to replicate £LOOP's business model. However, it would require investment to build a World-wide Virtual Private Network and the quality management functionality to compete in this niche.
Microsoft's strategy appears to be the Unified Communications platform provider of choice - rather than a provider of telecoms services. By opening up their Teams User Base to allow other providers to offer telecom services they are thus clearly indicating no intention to compete aggressively in this space.
ZOOM is experiencing explosive growth so I would doubt would see a benefit in reorienting it's whole business model to compete in a smaller niche. It would also be to acknowledge that their current service doesn't assure a quality experience. Also, they are probably focusing on resolving their software security issues as a current priority.
None of the web conferencing providers, I am aware of, have the infrastructure to compete in the Direct Routing market - and I doubt Microsoft would allow them to integrate with Teams.
On the other hand Cloud/VoIP Telecoms providers Gamma Communications (LON:GAMA), Vonage, Adept Technology (LON:ADT) and Toople (LON:TOOP) will be competing in this Direct Routing Market. These firms are not on the same scale as Cisco, Google and there is a lot of market to go for.
Regards Maddox (long LOOP)
Hi Maddox,
Some thoughts on Loopup (LON:LOOP)
1. Position Size and Management
I took at look a while back at the volatility in the stock and specifically what Stop-Loss level you might want to apply for protection given than you want to be a medium term holder. What I found was that I would need to have a ~30% stop loss. That is doo-able for me given my rules of 0.5% MaxRisk, but what it does mean that I would need to be careful with position size in the event of the stock rising by a target 60%-90%.
2. Phone a Friend (Actually I called two)
- Friend #1 is the Managing Director of a IT Services Company and a Silver Tier Microsoft Partner. Essentially, his view was that (a) no customer had ever asked for LOOP (b) the standard audio offering is perfectly adequate for the vast majority of clients (c) the Microsoft Teams environment is seen as a very reliable out of the box service with little or no specialist setup or technical support required (d) Microsoft suppliers are constrained in their profit margin on items that they sell into the MS teams environment - whereas MS is not!
- Friend #2 is a Manager at a major USA Video Conferencing Company. His view was that (a) Loopup (LON:LOOP) does not appear on the company's own competitor analysis at all; (b) the relationship with the PSTN providers is not an exclusive relationship (c) even placing Loopup (LON:LOOP) software onto the same server boxes that the PSTN companies use is unlikely to be exclusive (d) Loopup (LON:LOOP) have a profitable niche, for now, but no moat beyond first mover advantage.
3. Secular Trends
I can understand that if employers had to put in place home internet access quickly and cheaply then they might have given employees simple mobile phone network internet 'dongles'. I can undertstand that especially in areas with high density housing the mobile phone access will suffer from latency effects that disrupt call quality. I can understand that over time employers might move employees over to home IT setups that are based on Cable networks and which suffer much less from these latency effects - but this is more expensive and can take time to achieve. And over time the latency effects that plague mobile network access will lessen with the introduction of 5G locally and later a true 5G back-bone.
4. Best Guess
Loopup (LON:LOOP) is a business with a profitable niche that is likely to enjoy its moment in the sun - but that might not last. Their best hope might be (a) they get purchased by MS (b) they represenbt such a small market niche that the majors are content to leave them alone as a neutral service provider.
Would I rather have a smaller position in Loopup (LON:LOOP) or a larger position in Microsoft? Or both??? Trade (Loopup (LON:LOOP) ) and Trend (MS).
M.
Hi Macro,
Good points. 1) & 4) As Jack highlights above Loopup (LON:LOOP) 1H eps were 13.9p putting them on a p/e of 16 based on just their 1H earnings alone - if it does as well in 2H the p/e drops to just 8 - which is ridiculously cheap for a share growing as fast as LOOP. For comparison Gamma Communications (LON:GAMA) competing in the same space - is on a p/e of 32.7! I don't know what your aspirations are for Microsoft from here, but do you expect them to double?
2) #1. MS Teams is predominantly used within an organisation over its own managed internal network - which is of course fine. Currently, according to Gartner, only 10% of MS Teams is integrated with firms' external telephony. That's the new opportunity - 'Direct Routing'.
2) #2. Loopup (LON:LOOP) not being seen as a direct competitor is what I mention above. The Direct Routing opportunity is to integrate external telephony into MS Teams - displacing the PBX box altogether. The price offering is highly competitive and you save on PBX costs.
3) My firm recently conducted an employee survey into their working preferences post-Covid. Three choices - Would you prefer to work in the office most of the time? Would you prefer to work from home most of the time? or Would you prefer to mix home and office working? About 170 responses - almost exactly a third for each. Which equates to half preferring to be working from home a significant part of the time.
If you want to conference with your clients or prospective customers the likelihood is your going to have to catch them at home - and you'll want to give them the simplest, slickest, best quality audio visual experience possible. Particularly so, if they are abroad and speak English as a second language.
I've had far worse experiences than this.....
"I don't know what your aspirations are for Microsoft from here, but do you expect them to double?"
- Well, perhaps not as quickly as Loopup (LON:LOOP) . But a business with $136BN in cash that throws off $36BN pa in FCF, and whoose margins have risen from 19% to 36% over the last 5 years is unlikely to be short of opportunities! They can sit in VC/PE reviews and buy into all the most promising business models forever and a day. So, why not?
M.
What I like most about this company Maddox is they seem really focused on a small niche. They are a good fit for all professional services but seem to be winning law firms over as the way to do business (albeit they are only at the start of the process).
I find it very easy to imagine that they can achieve a dominant position in that sector in the next few years because it’s extremely interconnected (all lawyers need to talk securely to each other). But it is also easy to see how they can branch out into the main market from there (all lawyers need to talk securely to their clients). For me, this model is a great way to tackle the market overall.
I think this is a great CV19 play and it obviously accelerating their business. I see no reason why any of those gains should reverse when CV19 is under control though. In effect, CV19 is only accelerating the trend for the company, not causing it (I can’t make a similar claim for Zoom for example).
This is seriously high risk though - this is a big market with big players who could decide to end this company if they have a mind to. We also would be naive to think we have reached any sort of technological end point - there will be further advances in this sector which could leave LOOP out in the cold. However, for me the most likely outcome is an already large mass market platform looks about and sees a ready secure reliable solution for their business customers and snaps it up - I’m fine with that.
Interesting set up in LOOP. I actually was the one who voted No in the club - mainly over some concerns over my own trial with the software and some weak web traffic data since April - see similarweb. So I don't own personally, but do through the club. Am hopeful the wisdom of crowds wins out on this one. A lot of subscribers have done very well in this.
My closet technician says - bullish ascending triangle forming in LOOP's share price - though RSI is a bit divergent.
It does seem that we should have heeded the bearish RSI divergence after all.
Thanks Jack for the great in depth analysis of Loopup (LON:LOOP) (which I) bought in on Mike Taylors Cup and handle chart, he'd identified around the £1.80 ish mark.
I do firmly believe that this growth will continue to be based around the current remote working/lockdown culture. However, comforting to note clients signing up to 24 mth contracts.