Arbuthnot Banking: specialist lending up 26% and profit ahead of expectations, and we turn positive

Analyst’s view:
Strong growth in specialist lending and a newly profitable wealth arm are behind today’s upgrade, but rates are the bigger story. Falling rates hit Arbuthnot’s earnings hard, and with markets now pricing two rate hikes by the end of the year, that drag looks set to become a tailwind. The shares trade at less than half of book value and yield about 7%, before brokers update their forecasts for today’s upgrade.
Up 6.5% to 855p (£131m) - Third Quarter 2026 Trading Update
Arbuthnot Banking features in my portfolio, and when reviewing the StockReport data recently, I wondered whether it could soon be a Super Stock. Today’s third quarter trading update and the market’s reaction brought that a little closer.
Lending was the main driver for this private bank. Customer loans and leased assets rose 12% year on year to £2.5bn, and the specialist lending businesses grew 26%. Renaissance Asset Finance's book is up 45% to £409.5m – most of the growth coming from wealthy individuals buying high-value cars -- and Arbuthnot Commercial Asset Based Lending's is up 39% since December to £305.6m.
Deposits were up 10% to £4.9bn, although they barely moved in the quarter as the bank chose not to compete for rate-sensitive money. Funds under management and administration rose 21% to £3.1bn, and the long loss-making wealth arm turned a profit in the quarter.
There aren’t many weak points here. The quarter-on-quarter data isn’t as strong as the annual comparisons suggest: deposits and total loans each rose only about 2% in Q3, gross wealth inflows slowed to around £115m from roughly £170m a quarter in the first half, and Asset Alliance’s leasing book was broadly flat.
The Board now expects full-year profit before tax to come in ahead of expectations, and it says any rate rise would be a further tailwind.
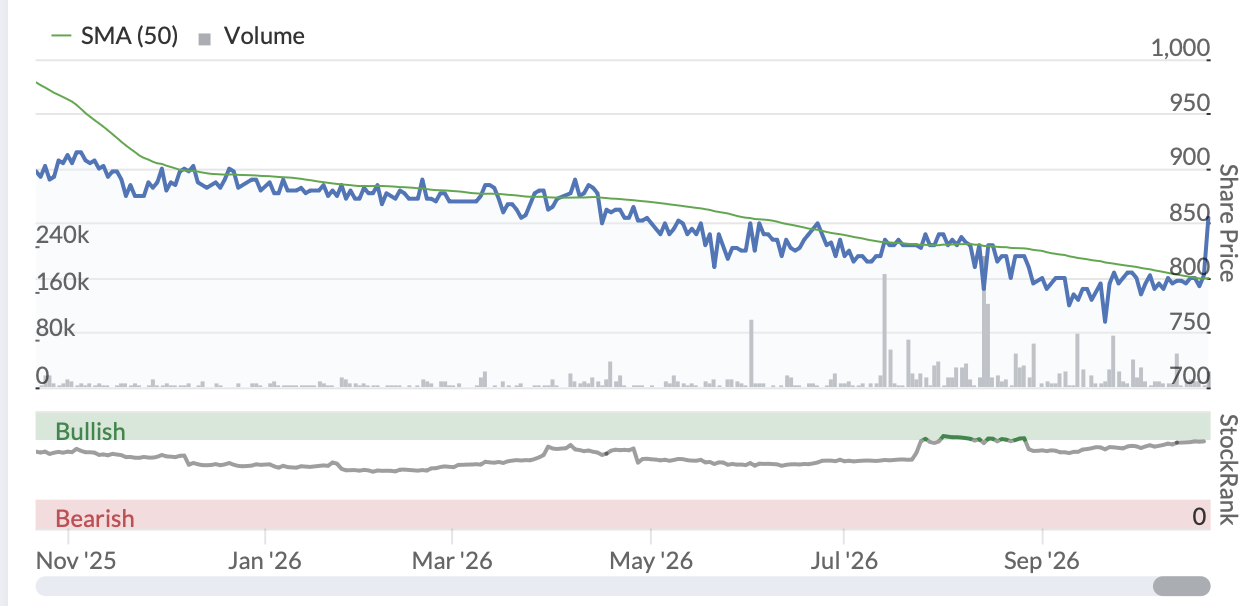
Interest rates have traditionally mattered more to Arbuthnot and this is seemingly why the stock was punished more as interest rates fell through 2024 and 2025.
It holds £4.9bn of customer deposits but has lent out only £2.5bn. Much of the difference sits with the Bank of England or in short-dated gilts and Treasury bills, with returns linked to interest rates. Arbuthnot doesn’t hedge the earnings on £523m of this “free cash” (as at June), calling the cost prohibitive. When rates fall, the return on its Bank of England cash falls straight away, while the gilts and Treasury bills delay part of the hit by three to 12 months.
Last year shows the effect. The Bank of England cut four times in 2025, ending at 3.75%. Lower rates were a big part of why profit before tax fell from £35.1m to £24.2m, and the net interest margin narrowed from 5.1% to 4.7%. The drag continued into this year: the average base rate in H1 2026 was 3.75%, against 4.48% a year earlier, and pre-tax profit was flat at £11m even though the loan book grew.
Of course, higher rates don’t help every part of the group. The company expects growth at Renaissance Asset Finance to slow in Q4 as financing costs are expected to increase.
Capital and credit
Capital ratios have come down a little. The CET1 ratio was 12.0% at June, against 13.3% at December, as the growing loan book increases capital requirements. The total capital ratio of 13.9% is still well above the regulatory minimum of 8.05% before buffers, although rule changes are expected to add about £20m to Arbuthnot's capital requirements.
Credit quality looks steady. Impaired (Stage 3) loans fell from £64m to £60m over the first half, and the impairment charge was less than 0.2% of the loan book on an annualised basis. One thing to watch is Stage 2, loans where credit risk has risen significantly, which grew from £53m to £74m.
Metrics and rates
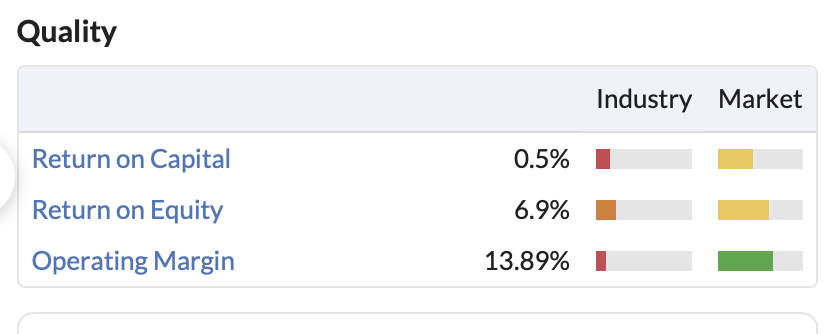
When I put an offer in on my house in late 2023, amid peak rates, Arbuthnot’s return on equity was 15.2%. Today’s StockReport shows a figure of 6.9%. The difference is largely interest rates, and that’s why I’ve been adding to my holding with the market pricing two rate hikes by the end of the year, and possibly more in 2027.
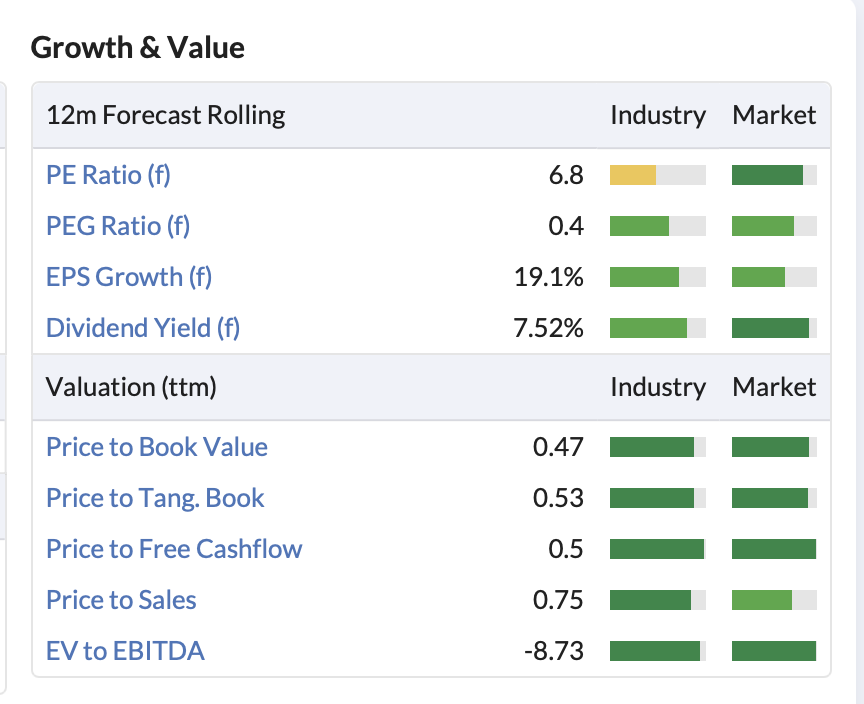
The Value Rank of 98 suggests this stock may be somewhat overlooked. Arbuthnot is valued at £131m, or 0.47 times book value (1,712p a share at June) and 0.53 times tangible book.
Consensus forecasts, from just two brokers, put the shares on 8.5 times 2026 earnings of 96.6p, falling to 6.6 times on 2027’s 123p. The forecast dividends of 57.5p and 61p give yields of 7.0% and 7.5%. Those forecasts haven’t yet been updated for today’s upgrade, so the multiples should come down further.
James’s take
It’s been a while since we last had a look at Arbuthnot, and the stock, for the most part, moved in the opposite direction to major UK high street banks. I definitely don’t see this as a risk-free opportunity, but I’m drawn by the valuation metrics, and the dividends. I’m also attracted because I feel Arbuthnot’s rate sensitivity looks like it might be a real tailwind over the next year.
There’s another very macro consideration, which I don’t know whether it’s worth factoring in (let me know in the comments). Arbuthnot is performing well despite record outflows of wealthy individuals, according to some sources. If that trend reverses, you’d expect Arbuthnot to be well positioned.
But on the valuation, rate forecast, and broad performance of the business, I’m shifting Arbuthnot to GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Arbuthnot Banking (3)
Comments here are also visible in the Daily Stock Market Report
Arbuthnot Banking (LON:ARBB) note not much of a rise today despite being ahead of expectations, are the budgetary potential tax on banks a potential headwind ?
No it's the spread?
James ref Arbuthnot Banking (LON:ARBB) thanks for the report and was interested until I noticed the directors are heavy buyers, normally a good sign, until I realised there's only a 15% free float. Have you ever tried to sell any and do you think it may be a problem?
Then read Yiannos write up on Earnz (LON:EARN) have owned both Mears (LON:MER) and sureserve, and impressed with Bob Holt, everyone needs a speculative play, so dipped in. Thanks for highlighting.