ASA International down 3% as it experiences some difficulties in Uganda

Analyst’s view:
The market reaction today is fair: any uptick in PAR>30 ought to be treated with some caution. Personally, I'm satisfied with the explanation that this is a country-specific issue. One of ASAI's attractions for me is its geographic diversifation; however, the downside of this is that there will usually be a problem in at least one of its locations. The potential value on offer here remains exceptional, to my eyes, and so I retain our fully positive stance.
Down 3% at 250.3p (£251m) - Q3 2026 Business Update
[Disclosure: at the time of publication, Graham has a long position in ASAI.]
International microfinance lender ASA International continues to achieve impressive growth - except for in India, which it has exited.
Highlights from today's update:
Excluding India, the outstandling loan portfolio grows 20% year-on-year, and by 5% quarter-on-quarter, to $631m.
Including India, the growth rate is 14% year-on-year.
There's an increase in the average loan size, seeing as the client base has only grown by 9% year-on-year (again, excluding India).
Portfolio at risk: PAR>30 (a measure of loans overdue more than 30 days) has ticked up from 2.4% (Q2) to 2.9% (Q3). This has been driven entirely by Uganda, as without Uganda PAR>30 was stable at 2.4%.
An explanation from the company as to what has happened in Uganda:
As disclosed previously, clients in Uganda have been negatively affected by the new trade regulations introduced earlier in the year. In addition, the country saw the impacts from the Ebola outbreak and a drought.
ASAI has responded proactively with a range of remediation measures, including "a short-term reduction in the portfolio" and management changes.
India: gross outstanding loan portfolio has reduced to an almost negigible figure ($3.4m). The exit should be finalised by the end of the year.
CEO comment:
...This performance reflects the resilience of demand across our markets and the strength of our operating model, with particularly strong contributions from Pakistan, Ghana, Kenya and Myanmar. We continue to balance growth with disciplined risk management, maintaining overall portfolio quality.
While PAR>30 increased during the quarter, this was primarily driven by temporary challenges in Uganda. Remedial actions are already under way and are expected to become visible in the PAR levels in Uganda in the coming months.
Estimates
Thanks to Cavendish for covering this stock today, with only "minimal" changes to forecasts. For example, the FY26 diluted EPS forecast increases by 0.3% to 73.1 US cents. The same forecast for FY27 increases 0.6% to 84.2 US cents. The increase in GBP is a little higher due to exchange rate movements.
Graham's view
The market reaction today is fair: any uptick in PAR>30 ought to be treated with some caution.
Personally, I'm satisfied with the explanation that this is a country-specific issue. One of ASAI's attractions for me is its geographic diversifation; however, the downside of this is that there will usually be a problem in at least one of its locations.
While the company remains very profitable at this level - note that earnings forecasts are stable - it is worth highilghting that PAR>30 of 2.9% is the highest level of risk we've had here in a few years. For context, it was 2% in 2023, 2.2% in 2024, and 1.8% in 2025.
PAR>30 had reached much higher levels in the Covid era and when the company was exposed to India.
I've had a fully positive stance on this one and I'll leave that unchanged today, on the grounds that earnings forecasts are intact and the difficultied in Uganda are isolated and likely to be short-term.
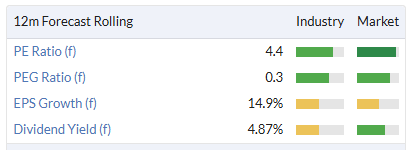
The potential value on offer here remains exceptional, to my eyes. And when a stock is trading at a mid-single-digit earnings multiple, we can't expect perfectly smooth sailing:
At the time of publication, Graham had a long position in ASAI.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on ASA International (5)
Comments here are also visible in the Daily Stock Market Report
ASA International (LON:ASAI) has a HUGE debt pile!!!!
ASA International (LON:ASAI)
has a HUGE debt pile!!!!
No shit - its a money lender - the money they need to lend out has to come from somewhere - ok it may be preferable that they would have people depositing funds with them rather than them having to borrow (you dont want a northern rock type situation).
Note Graham nicely summed up how they do business in a recent update (30/7)so i will just copy and paste info below.
to me taking grahams comments at face value it seems they have areally good safety net due to the high margins they make - so if they costs go up 2-3% they should still be making good money - thats not always the case with uk lenders who are preumbaly more regulated ref rates charged. aty face here the margins are fantastic - the risks are probabaly more geopolitical.
PAR >30 (GN note: portfolio at risk, more than 30 days due) of 2.4% vs. 2.0% a year ago
PAR>30 was 2.4% as at 30 June 2026 compared to 2.0% as at 30 June 2025, which remains industry-leading. One of the main drivers was the introduction of new trade regulations in Uganda which negatively affected clients.
I’d be more concerned about this if ASAI was a marginally profitable lender. But that’s not the case: net interest margin was 39.3% in 2025. Speaking roughly, this represents a huge spread between the yield the company earns on its loans, and the interest it pays on its borrowings. Net interest income was $244m, while total operating expenses were $143m.
Note sticky has them down as having 194p per share book value nowish (shareprice 250p) - if they are earning 70p eps and paying out 20p divis - thats some nice excess real value dropping through - note it will be levereged buisness model so that if loans increase at a lick that may increase at faster rate than profits made so extra funding needed.
Its pretty basic though if you have company making decent clean earnings and p/e is only 5 - it shouldnt take long for the benefits to be seen in shareprice as long as there is no hidden nasties. Perhaps within 2 years if shareprice stays where it is assets would be worth the shareprice alone.
The dream scenario for companies like this is if you can can sweet spot of nice organic growth and also reduce your external fundining requirements each year on lfl basic - then you also potentially get benefit of lower future costs on your debt - plus the marekt sees the company as less risky.
On the negative side - well money lending has alwasy ben kinda like the wild west - tehn buisnes model only ever works when customers are happy to repay all of what they borrow - plus some reasonable margins on top to cover profit and bad debt. Thats often the danger here is that growing lending books can hide issues within book - historically many companies covered over the cracks by lending more to cover those thats stuggled to pay - you need to hope that the company you invest in is doesnt have any sort of black hole in its debtors book - or sources of funding. stuff like that probbaly mostly explains the low ratings some of these lenders have when listed.
Hopefully Graham gets a chance to look at the update from ASA International (LON:ASAI) today.
+1 for ASA International (LON:ASAI) please - i currently hold Time Finance (LON:TIME) but the takeover there should be complete soon so i kinda mentally have the cash burninga hole in my pocket - this seems like decent potential similar lfl replacement candidiate with the uber low p/e. Not sure how tricky it is doing buisness in the places it lend money ?- eg the exit from India waht that does to tougher lending rules ? with a spread of different countries you would think that would provide some sort of worst case safety net if they had to stop in say their biggest market. With pe of under 5 ish one would hope there is some scope for bad news in one country to still leave decent returns beig made. the update seemed chipper and the stocky forecasts for next year show decent expected growth in bottom line. Secure Trust Bank (LON:STB) is trading on similarly cheap p/e with even bettre growth expected next year - perhaps uk is slightly less of the wild west - i already own som ehere though. Perhaps 50% on each is the way to go if i do make the switch.
Osb (LON:OSB) should be a beneficiary of the pivot back to £20K cash ISA's via their Kent Reliance business, although their products do need to get a bit more competitive. Nice dividend yield. No emerging market lending sleepless nights!