BAE Systems share price rises as free cash flow guidance hiked to £3bn

Analyst’s view:
Profit guidance is unchanged today while upgraded free cash flow guidance appears to reflect customer advance payments rather than any change to trading conditions. However, BAE appears to be trading well and benefiting from structural demand growth in both the UK and US markets. The valuation has eased since our last view in May and I'm happy to stay broadly positive.
Up 1.5% to 1,945p (£58bn) - Trading Statement
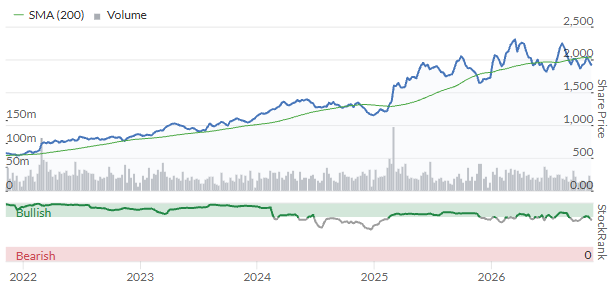
BAE Systems' share price has consolidated this year after quadrupling over the last five years. Today's announcement looks solid to me but seems unlikely to prompt any major change to expectations.
Key highlights:
Strong momentum with order intake of £33bn so far this year, and further expected. This compares to a figure of £16.4bn at the end of June, so order intake has increased modestly in H2. Notable orders include c.£1.6bn related to the Global Compat Air Programme and c.£4.3bn of further funding for UK Dreadnought Class nuclear deterrent submarines.
Free cash flow is now expected to be around £3bn this year, nearly 50% above previous guidance of >£2bn. This is said to reflect the benefit of customer advances received so far.
CEO Charles Woodburn says that strong trading in BAE's Electronic Systems, Air and Platforms & Services sectors offset "subdued growth and margins in our Maritime sector, as we progress through the first-in-class stage of the Type 26 frigate programme."
My reading of this is that completing the first of these new submarine hunter frigates is perhaps taking additional time and resources - hopefully future ships (I believe eight are on order for the Royal Navy) will be quicker.
In the US, BAE singles out munitions as an area of strong demand and says the company is supporting ten of the 12 programmes that are "prioritised for significantly increased production capacity". Space defence is also said to be a key area of focus.
Outlook & Guidance
There's no change to guidance today, other than the increase to free cash flow mentioned earlier:
Sales +8% to 10% (FY25: £30.7bn)
Underlying EPS +11% to +13% (FY25: 75.2p)
Free cash flow c.£3bn (FY25: £2.2bn)
Crunching the numbers shows that the FY26E consensus EPS of 85.1p currently shown on the StockReport is already at the top end of this guidance range, so I don't expect any significant changes to forecasts today.
Roland's view
The world has changed and BAE Systems is one of the company's that seems to be benefiting.
Progress with major programmes appears to be satisfactory and upgrade to free cash flow is encouraging, albeit this is always a lumpy metric for BAE.
Back in May, James commented that "a near-term re-rating looks unlikely". BAE's share price is largely unchanged since then, but the company's valuation has eased slightly as earnings expectations have edged higher:
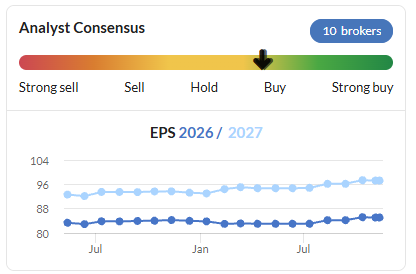
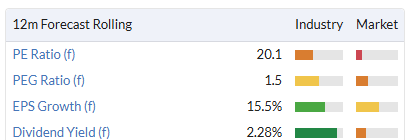
As a result, the stock's rolling 1y forecast P/E has fallen from 23x to 20x since May, while the forward dividend yield is now above 2% again.
Quality metrics remain slightly above average, but not by much:
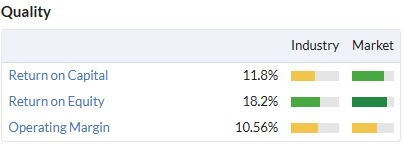
In general, I'd say that a large cap with these valuation and quality metrics was fully priced. But while I don't expect a major re-rating for BAE, I suspect that the outlook remains quite positive, with the potential for further upgrades.
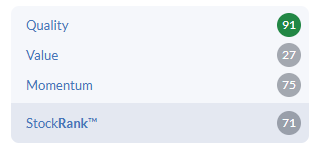
This is reflected by the stock's High Flyer styling and relatively strong StockRank:
I'm going to leave our broadly-positive AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on BAE Systems (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?