Beximco Pharmaceuticals - 100 Stock Rank but not without risks
Analyst’s view:
If this company can keep growing earnings while trading at a mid-single-digit P/E, paying a 6% dividend, and reinvesting 70% of earnings into producing new generics, it is clearly too cheap.
However, it is not without risks and was suspended until mid-year, when it failed to publish its FY25 accounts on time amid a prolonged regulatory and legal impasse. It's currently high profits may also may not last when Bangladesh's patent waiver expires in November 2029, and the company has to pay licenses on newer drugs.
The valuation may well mean it is worth a punt for the risk-tolerant investor, but any excitement should be tempered by the scale of the things that can go wrong with any largely overseas company that is listed on AIM.
Up 4% to 62.5p - Results for the year ended 30 June 2026
There's not much narrative in these FY results from Bangladeshi generic drug manufacturer Beximco Pharma, as they prefer the numbers to do the talking. These look pretty good:
- Net revenue increased 14.5% to Bangladesh Taka ("BDT") 56,265.9m / £347.5m (2024-25: BDT 49,120.4m / £295.6m
- Domestic sales increased 15.1% to BDT 51,852.5m / £320.3m (2024-25: BDT 45,046.9m / £271.1m)
- Export sales increased 8.3% to BDT 4,413.4m / £27.3m (2024-25: BDT 4,073.5m / £24.5m)
- Profit after tax increased 30.9% to BDT 9,160.8m / £56.6m (2024-25: BDT 6,998.9m / £42.1m)
- EPS for the year amounted to BDT 20.17 (2024-25: BDT 15.56)
Underlying the 14.5% rise in revenue, domestic sales grew 15.1%, which is 92% of sales. Exports grew a more modest 8.3% and remain under 8% of revenue, so this is still mostly a Bangladesh-exposed company.
While it is tempting to think that a generic drug manufacturer has no competitive advantage, the numbers suggest that there is at least some moat here:
Gross margin rose about 330bp to 48.7%, although they don't say whether pricing power, product mix (such as new launches), input costs, or some combination of these drove it.
Return on equity improved to about 15.6% from about 13.7% on average equity.
They have a first for successful generic production, saying, "We are especially proud of the Triko launch, the world’s first and only generic copy of breakthrough Cystic Fibrosis drug Trikafta, providing patients with transformative access to a lifesaving medicine at a fraction of the originator price."
Financially, net debt has swung to net cash. Including short-term investments, cash is BDT 7.6bn against borrowings of BDT 4.6bn. That gives net cash of about BDT 3.0bn, compared with net debt of about BDT 2.4bn a year ago.
However, some of that cash improvement is due to timing, due to a delayed dividend payment. For this year, the proposed BDT 6.00 per share is up 26% from FY25’s BDT 4.75, a payout of about 30% of earnings. This appears ahead of the 4.96 BDT forecast in the Stock Report, giving a yield approaching 6%.
Valuation:
The EPS figure of 20.17BDT also looks ahead of the Stockopedia consensus. Although I can't see any updated coverage from SP Angel, whose notes on the company are on Research Tree, to be sure.
Helpfully, this figure is pretty close to the forecast for the following year, which means I can fairly simply conclude this is on a pretty low P/E of around 5x earnings.
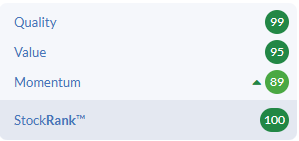
This is very cheap, so it perhaps shouldn't be surprising that this is the highest-ranked stock in the UK at the moment:
Risks:
Being a largely Bangladeshi company listed on AIM, this is not without risks, the most obvious ones being:
Patent waiver: As a Least Developed Country (LDC), Bangladesh is exempt from the WTO’s TRIPS patent rules, so its drug makers can make patented medicines without licences. That exemption is what makes products like Triko (the Trikafta copy) possible. Bangladesh was due to lose LDC status on 24 November 2026, which would have been a near-term cliff. However, the UN General Assembly extended the preparatory period to November 24, 2029, and the decision was adopted without a vote or an objection. The risk is pushed back, not removed: officials have stressed that Bangladesh would not receive another extension beyond 2029.
Currency: The Taka strengthened slightly against sterling (from 166.2 to 161.9 per £), so the sterling figures look a little better than the underlying Taka growth. Profit after tax is up 34% in sterling against 30.9% in Taka. However, this could reverse in the future.
Governance: This is the bigger risk. The company failed to publish its FY25 accounts on time amid a prolonged regulatory and legal impasse. The interim government’s regulator appointed nine independent directors to the boards of Beximco Pharma and two other group companies, and the company’s legal challenge to that is still pending in court. The AIM listing was suspended, and trading was restored on 26 June 2026. Today’s on-time results are a positive sign that normal reporting has resumed, but the board dispute remains unresolved.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Beximco Pharmaceuticals (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?