Bloomsbury Publishing: first-half profit falls 30%, so it needs a big second half

Analyst’s view:
With H1 revenue down 5% and PBT down 30% vs the previous year, they will need a big H2 to meet market expectations. There is a strong pipeline of books for H2 in their consumer division that provides some confidence that they can deliver the sales. However, they will also need near-record operating margins in both divisions to hit the PBT forecast, something that may be challenging if A&P revenues continue to decline, as expected. It is probably foolish to bet against a company that usually delivers. However, with the risk of a warning increasing today, and a fairly punchy forward multiple compared to growth rates, I think we should be a bit more cautious in our view.
Down 9% at 615p (£548m) - Interim Results
Context:
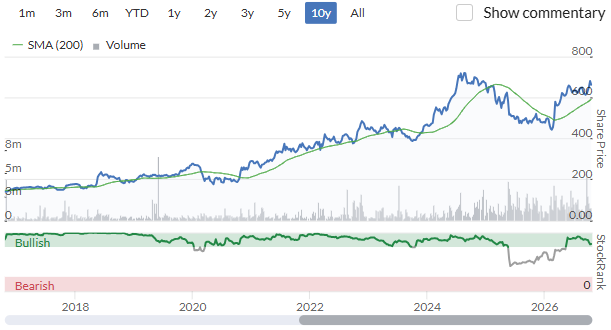
Bllomsbury was a big winner for holders coming out of the COVID period, with the shares delivering 3x returns to the end of 2024. However, the recent share price performance has been choppy:
Interest in the stock has been reinvigorated by an upgrade to FY27 forecasts earlier this year:
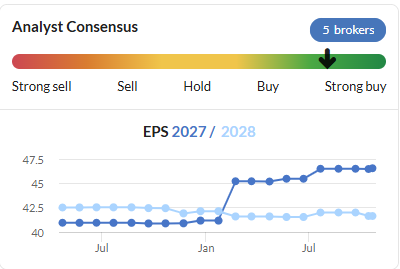
This trend led Roland to upgrade our view to GREEN when the FY26 results were published in May.
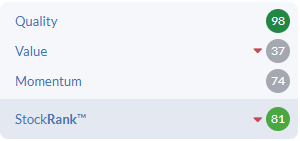
However, going into the H1 results, the share price had risen over 40% on a FY27 consensus that had only risen by 13%. The FY28 consensus had been slightly downgraded during this time. The net result is that the stock doesn't look particularly cheap, and the company goes into these results with high expectations from investors for further upgrades:
H1 Headlines:
While not an upgrade, the in-line headline gives initial reassurance:
Bloomsbury is pleased to report first half revenue of £151.6m with profit of £16.8m and a strong start to the second half of the year, underpinning the Board’s confidence in delivering record results for the full year.
However, I am always a little suspicious when no comparatives are quoted.
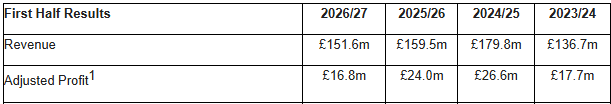
Percentages are still missing from the comparative table, but my maths suggests that revenue is down 5% and Adjusted PBT down 30%.
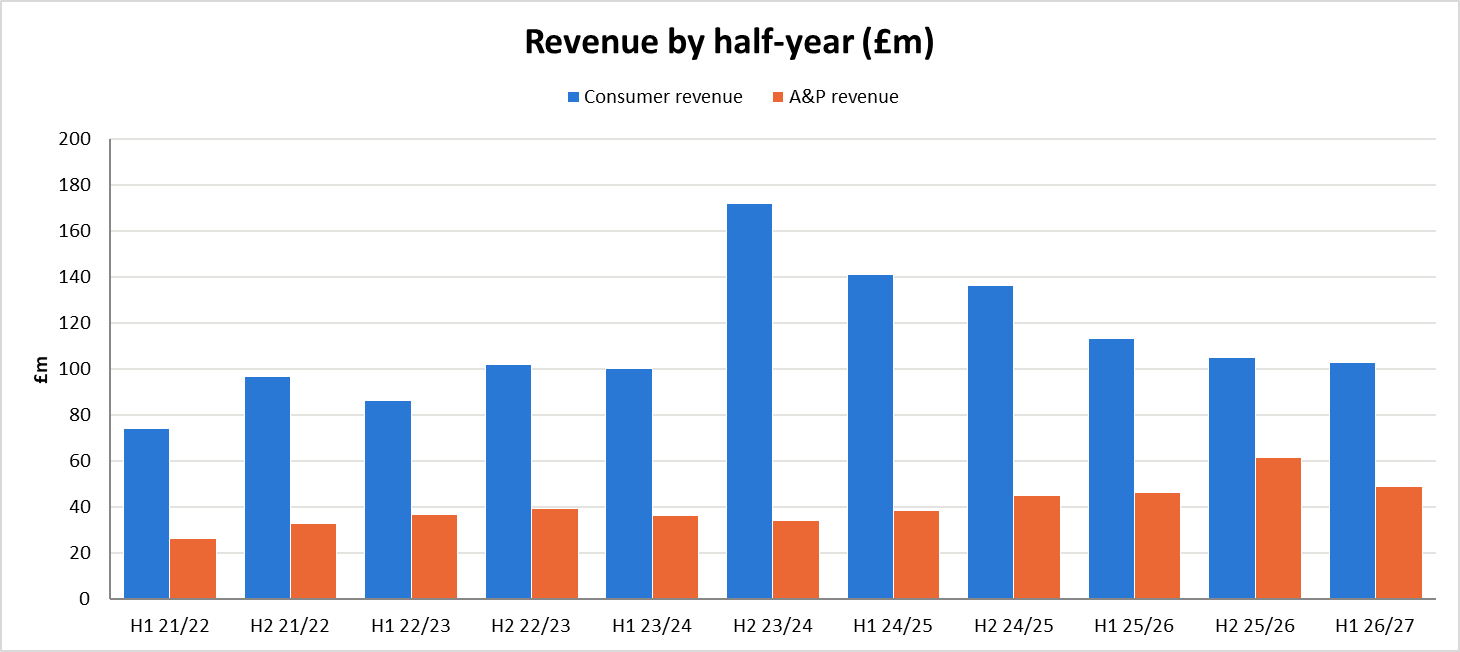
The context suggests that this was a weak half for both the Consumer division and the Academic & Professional one:
While they say:
A&P revenue is up 5.9% to £48.8m (H1 2025/26: £46.1m), showing encouraging signs of recovery
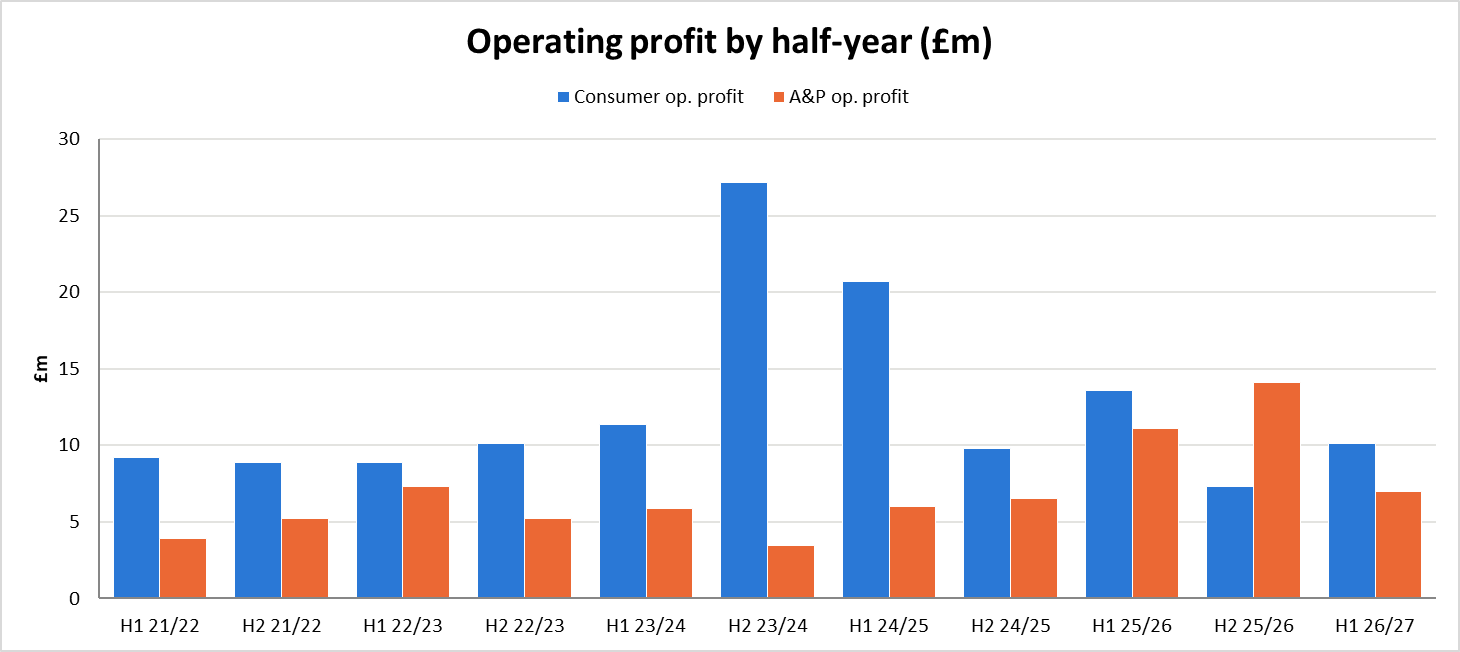
Operating profit in this division is down significantly:
Caused by much lower margins:
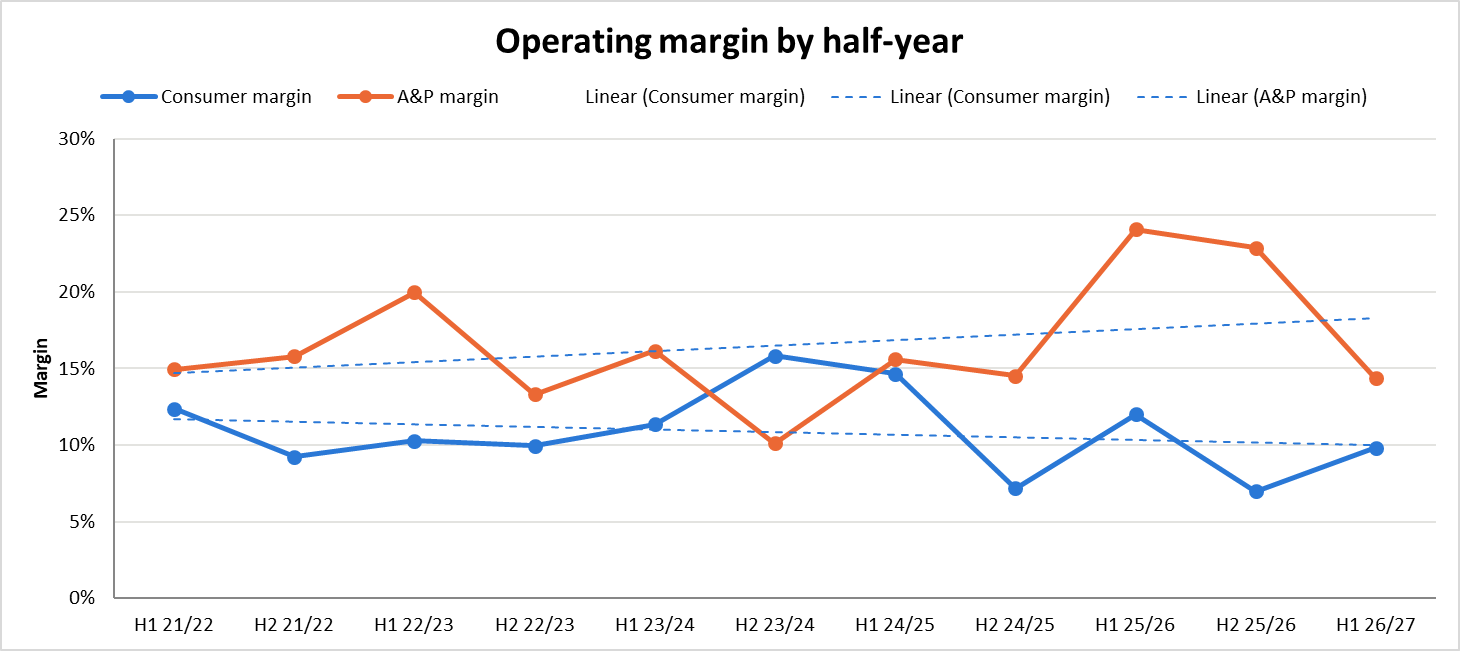
It may be too soon to conclude that the recent upward trend in margins in the A&P division is about to reverse. However, the risk that the previous two halves were anomalously high increases.
Adjustments:
As well as profits being down, the level of adjustments required to get there has also increased:
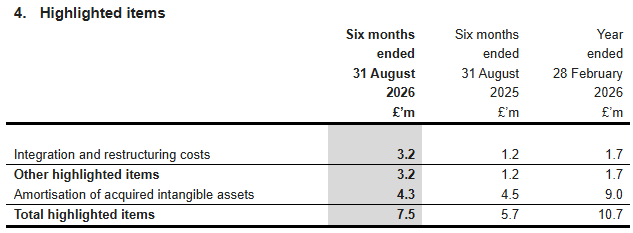
While amortisation of acquired intangibles is largely flat, there has been a big jump in restructuring costs. While these are probably the right thing to do and should drive improved profitability in the future, this doesn't suggest a business firing on all cylinders. Their narrative around this doesn't suggest that this process is complete:
We are progressing with key operational changes to support growth and enhance profitability through financial efficiencies. In April 2026, we announced a restructuring, and we have taken the first steps to simplify and streamline our structure. This has enhanced agility, accountability and positions the Company for continued expansion.
[my emphasis]
That the company appears to have repeated integration and restructuring costs, and is guiding for these to continue, makes these look far from one-off.
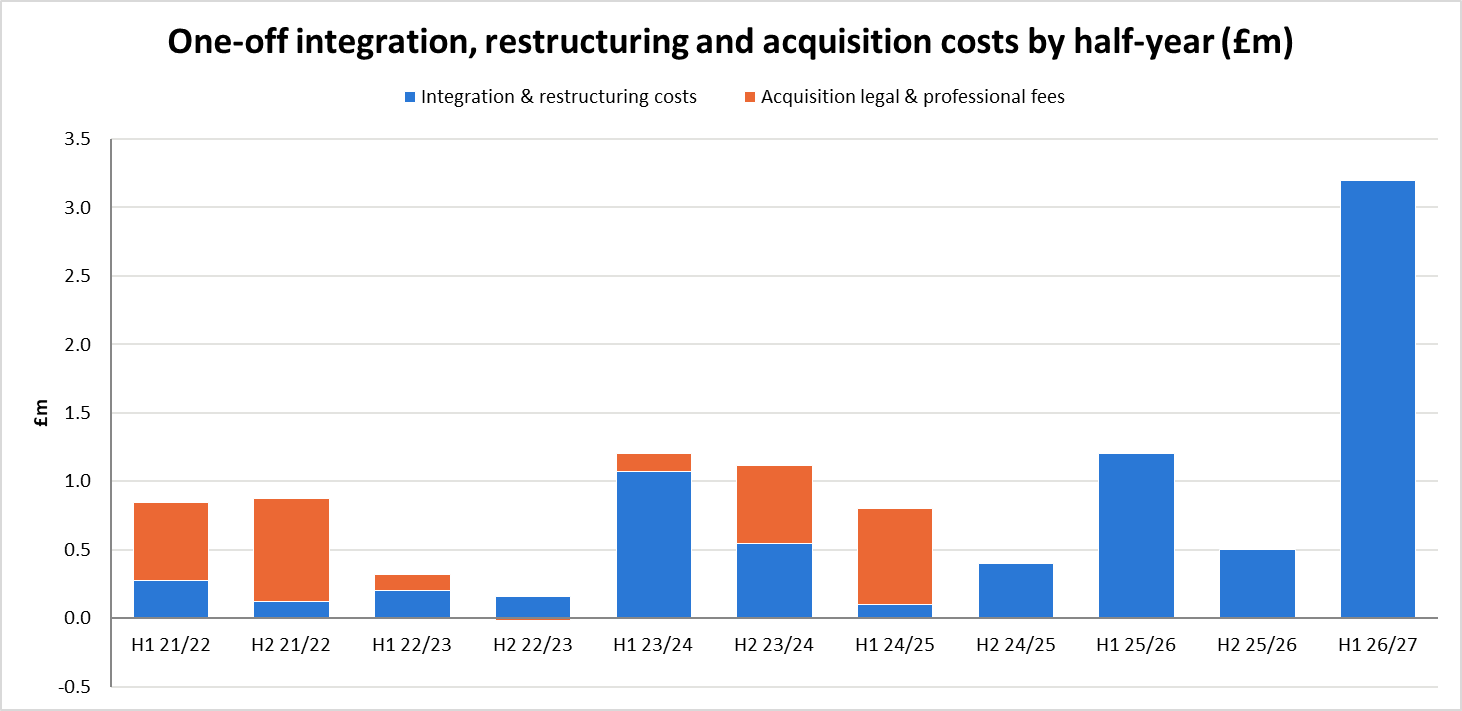
At the very least, the company wants us to give them the benefit of all the cost savings without counting any of the costs of achieving those savings against them.
Outlook:
Despite the weak half, the company say they are in line for a record year:
The Board looks to the current year with confidence in delivering record results in line with Adjusted Profit expectations....Bloomsbury’s portfolio of portfolios strategy, our authors, customers and the scale and resilience of our business continue to underpin the confidence we have in the future.
And helpfully, give us the consensus:
The Board considers consensus market expectation (before this publication) for the year ending 28 February 2027 to be revenue of £354.3m and Adjusted Profit of £49.9m.
There are reasons to think that the second half will be stronger for the consumer division:
Growth is second half weighted and the new novels for H2 2026/27 include many of our bestselling authors. In September, Gillian Anderson’s follow-up to Want, titled More, and Stephen Graham’s Letters to Our Sons, became instant Sunday Times bestsellers. Sarah J. Maas’ much anticipated next two novels in the A Court of Thorns and Roses (‘ACOTAR’) series, A Court of Splintered Harmony and A Court of Forgotten Melody, will be published on 27 October 2026 and 12 January 2027, respectively.
Forecasts:
I can't see any updated note from their broker, Singer. Still, taking the FY27 revenue forecast from earlier in the year, where Singer provides the split between Consumer and A&P revenue, then this is the implied H2:
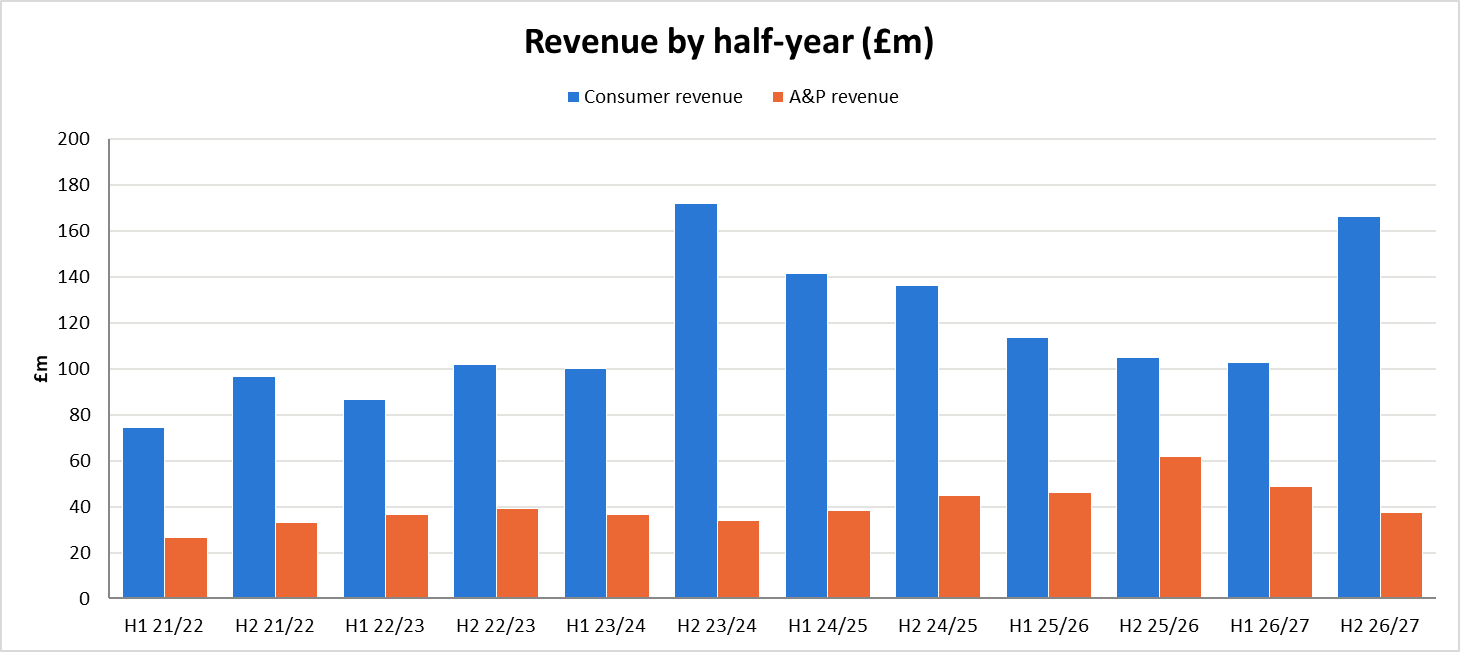
While these don't look impossible, they need to be on for a near-best-ever H2 in the consumer division to hit forecasts.
More worryingly, to hit forecast PBT in my calculations, they would need to reach near-record 15% operating profit margins in H2 for Consumer, while also increasing H2 A&P margins back to around 20%, something that may prove challenging on declining revenue forecasts.
Balance sheet:
The better news is that the company is generating strong cash flow with net cash rising to £22.8m. Although this is down from the FY number, it is largely due to dividend payments. They will also get some cash from the Anthropic settlement, although teh exact figure is unknown.
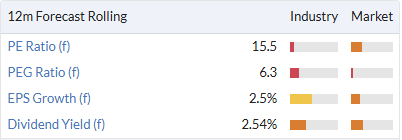
The interim dividend increased by 5% year on year to 4.28p. However, the problem with being such a highly rated stock is that the actual yield is low, and net cash is only 4% of the market cap. This doesn't really move the needle on valuation.
Mark's view
While it seems too soon to say the company will miss expectations, they have left themselves needing a pretty big H2 to hit the numbers. They need sales to deliver in their consumer division, and they'll need near-record operating margins in both BUs to hit forecasts. It would be particularly embarrassing if they upgraded forecasts earlier in the year, only to miss them, even slightly.
Increasing teh risk is that FY28 is not currently forecast to benefit from such a strong pipeline of book releases, which means that profits are currently forecast to decline. Unless, there are upgrades to come, a 16x multiple for a company with flat EPS and sales on four years previously may look a bit punchy, despite some excellent quality metrics.
Despite these risks, the company has executed very well over the last few years. It would probably be foolish to bet against that continuing. However, with the risk of a profits warning for FY27, or at least no upgrade for FY28, rising given today's results, I don't think we can remain fully positive. AMBER/GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Bloomsbury Publishing (6)
Comments here are also visible in the Daily Stock Market Report
Bloomsbury Publishing (LON:BMY) I hold here and was a little disappointed in H1 numbers.. *however*.. it's worth investigating why H2 23/24 and H1 24/25 cumulatively generated c 30mm excess profit in the consumer division and that was of course the Sarah J Mass Crescent City release in Jan 2024.. of course she has two books from her more popular ACOTAR series coming in H2 this year which is probably why they're so confident.. it is no coincidence that they raised FY estimates on BD5 this year the morning after she revealed the release date of these books.. if both books combined generate the same bump in thie FY then they will still outperform current estimates.. the Harry Potter series too should provide a boost...
My feeling is that the potential sales boost from the 2 upcoming SJM books was already priced in after a very strong run this year. Bear in mind this will only be a one-off boost and sales are expected to normalise again next year. Great company, but slightly uncomfortable they are so reliant on one author and all the lumpiness in earnings this entails.
Good morning Graham, if time permits, please could you look at Bloomsbury Publishing (LON:BMY) interims today?
Yes - will be interesting to see how the Mkt reacts - actuals are down but theres plenty of jam tomorrow - lots of it!
I find this statement somewhat confusing:
"Confidence in delivering record results in line with Adjusted Profit expectations."
Get excited but don't get too excited.
Seems the market does not like the figures share currently off nearly 9% ( I hold as well for ' jam tomorrow' )