boohoo posts adjusted profits but true financial success remains unproven

Analyst’s view:
Stockopedia's StockReport categerorises this as a Turnaround which matches perfectly with how the company would describe itself. And it could start to look like a value share, if forecasts are hit. Quality should improve, too: the company has transitioned to an "asset-light" business model, owning far less property and machinery and outsourcing where possible. For investors, it is now a diversified marketplace with access to thousands of brands, rather than a bet on a few fast-fashion labels. However, its financial success remains to be proven and so for now, I remain only moderately positive.
Up 4% at 26p (£405m) - Results for the six months ended 31 August 2026
boohoo has reported some strong H1 results:
Gross merchandise value after returns up 3.7% (£619.5m)
Revenue down 3% (£409.6m) but gross profit up 1% (£221.5m)
Adjusted EBITDA up 14.6% to £24m, assisted by stable operating costs.
As I noted at the trading update, I'm pleased to see that the adjustments to H1 EBITDA have collapsed to only a few million pounds.
This means that actual reported EBITDA figure comes in cleanly at around £20m, not far from the adjusted figure. In H1 last year, reported EBITDA was negative.
The accounts are complicated by a very large item: "non-cash lease gains" of over £40m, also referred to as "gain on recognition of finance lease receivable".
Trying to put it in plain English, boohoo has restructured its warehouses leases and in this case, it has generated a one-off accounting gain. It does impact the shape of the company's balance sheet. It doesn't impact cash flow, at least not in the short-term.
If this one-off gain and other "exceptional" items - including the likes of amortisation and share-based bonuses - are all excluded from calculations, then boohoo made a small after-tax loss in H1. But the direction of travel is positive: the adjusted loss in H1 this year is only £2m, vs. £14m in H1 last year.
CEO comment:
“The turnaround continues at pace. The Group has returned to GMV growth, gross margins are expanding and returns rates lowering. Reported EBITDA has increased over 600% and profit before tax has improved to £28.3m. This is the first time the Group has delivered positive profit before tax since August 2021. I am pleased to report that net debt is expected to be negligible at year-end. This is significantly ahead of our original guidance provided at the start of the year. I see material opportunities ahead and we are fully focused on maximising them.”
There has been excellent progress for sure, but I'd be a little cautious when interpreting this "600%" increase in reported EBITDA. The main reason for the improvement in reported EBITDA, as mentioned above, was lower adjustments. That's a big achievement, but it's a one-off.
Similarly, the positive profit after tax figure is only made possible by the lease accounting gain. The restructuring that caused this gain is surely a positive event for the company, but it's also a one-off (and also non-cash).
Disposal: as previously announced, the company has achieved the disposal of the Sheffield site for £90m and also Nasty Gal for about £12m. As a result, "net debt is expected to be negligible at the year-end". Fulfilment migrates from Sheffield to Burnley with a new partner in the form of GXO Logistics.
Outlook: in line.
Trading in September continued to be good, with the Group experiencing further accelerated growth. In respect of the full year, the Board expects to deliver GMV growth and Adjusted EBITDA of no less than £59m, as previously guided, representing double-digit growth year-on-year, together with continued material improvement in Reported EBITDA, positive profit before tax, free cash flow generation and negligible net debt. The £100m fixed cost target remains on track.
Estimates
Panmure Liberum and Zeus have both published on boohoo today. To give an example of current forecasts, Panmure see fully diluted EPS of 1p in FY Feb 2027, 1.7p in FY Feb 2028, and 2.6p in FY Feb 2028.
Graham's view
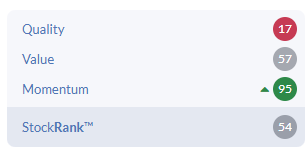
The Stockopedia StockReport categerorises this as a Turnaround which matches perfectly with how the company would describe itself. From the point of view of the StockReport, it has low Quality (for now), but moderate Value and rising Momentum:
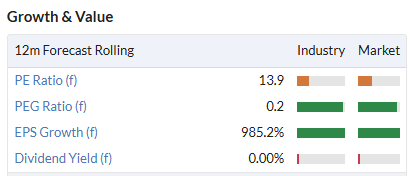
And it could start to look like a value share, if forecasts are hit. No dividend for now but a modeste PE ratio, based on forecasts:
Last month, I raised our stance on boohoo to moderately positive.
I don't see anything in today's report or in the broker forecasts that would make me want to upgrade our stance even further. I do think that the bullish thesis is fully intact: the company has transitioned to a more "asset-light" business model, owning less property and machinery and outsourcing where possible. If it works, this should see quality metrics improve over time.
For investors, it is now a diversified marketplace with access to thousands of brands, rather than a bet on a few fast-fashion labels.
This is now far more interesting to me than it was before, although its financial success remains to be proven. For that reason, I remain only moderately positive.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Boohoo (2)
Comments here are also visible in the Daily Stock Market Report
There is the reportedly £245m shareholder lawsuit against Boohoo (for alleged insufficient disclosure over the Leicester supply chain issues), which I understand is due to come to court in October 2027. I note that this lawsuit is not mentioned in the contingent liabilities section of the interims nor the annual report (so presumably this means Boohoo management is confident of winning if this goes to court).
Thanks for the review. Like all things Boohoo you do take on trust a number of issues. I noted at the disposal of the Sheffield Depot as cleaning out the stables and that a stock I long regarded as ' just rag trade' with the associated platitudes was looking like a possible early stage recovery which is now slightly more in evidence. I turned positive a little while back but was waiting to see the next installment which is this annoucement. Still lots could go wrong and the Stocko quality measure is aa fair comment on the company. Likely I will take a small position given the new management seem keen on cleaning up the mess left by their predecssors. Many a slip twixt cup and lip...