BRCK Group: housing headwinds cut earnings guidance by 20% as debt climbs - we turn cautious

Analyst’s view:
The current headwinds in the housing market are well known and I'm not entirely surprised by today's downgrade. However, this is BRCK's second profit warning in four months. I'm going to move our view down by two notches to AMBER/RED today, to reflect the growing risk from rising leverage and the seemingly weaker outlook for earnings.
Down 11% at 44p (£141m) - Half year Trading Update and Notice of Interim Results
You have to read to the end of today's half-year update to discover that this building materials group has issued a profit warning.
While BRCK headlines with the news that performance during the first half of the year was in line with expectations, CEO Frank Hanna says that a recovery in UK housing market conditions is now expected to take longer than previously thought. As a result, BRCK has cut FY27 adjusted EBITDA guidance to c.£45m; that's 10% below previous guidance of £50.3m.
Key points:
H1 revenue expected to be down by 1.1% at £343.1m
H1 adj EBITDA to be down 6% at £25.5m
Net debt excluding leases £96.4m on 30 Sept (up from £60.5m on 31 March 26)
Trading impacted by "subdued housebuilding and RMI [Repair, Maintenance & Improvement] markets"
I'm a little concerned about the increase in BRCK's debt levels. The company says the increase in net debt since the 31 March year end was due to the acquisition of specialist fencing contractor Jacksons during the summer.
However, this doesn't seem to account for all of the extra borrowing: the initial consideration for Jacksons was £14.5m in cash plus £4.9m for certain freehold properties. That gives a total of c.£20m, suggesting that a further £16m of cash has flowed out of the business for other reasons.
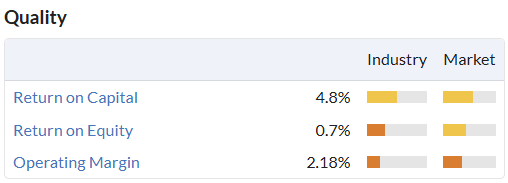
Some of this might relate to seasonal factors such as inventories, but I think the increase in debt is still a potential concern. I estimate BRCK's trailing 12-month leverage to be almost 2.0x EBITDA. For a low margin business that carries fairly high levels of inventories and receivables, that's higher than I'd really want to see.
The current headwinds in the housing market are well known and I'm not entirely surprised by today's downgrade. But I'd have hoped that BRCK would have been able to manage the business to reduce cash outflows during this period. That doesn't seem to have happened, although we'll have to wait for the H1 results in November to be sure of the explanation.
Outlook
House broker Cavendish has issued update forecasts today. Profit estimates for this year have obviously been cut, but expectations for the next two years have also been trimmed, suggesting an increasingly cautious outlook on growth:
FY27E adj EPS: 6.6p (-19.5% vs 8.2p previously)
FY28E adj EPS: 7.5p (-13.8% vs 8.7p previously)
FY29E adj EPS: 9.6p (-5% vs 10.1p previously)
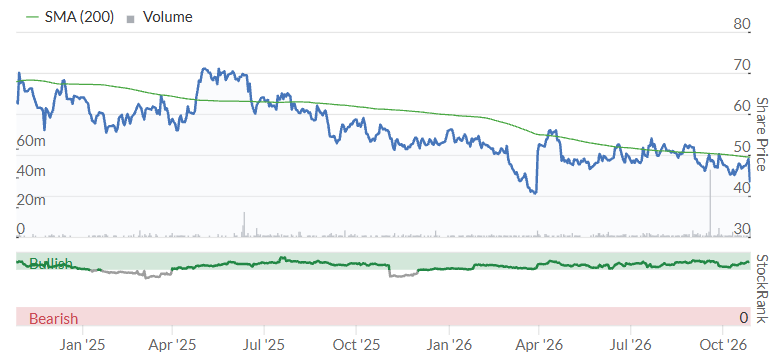
BRCK's share price has only fallen by c.11% at the time of writing, despite the c.20% cut to FY27 earnings forecasts. This suggests the market had already priced in a partial downgrade and highlights the stock's modest valuation - BRCK is trading on around 6x FY27E EPS after today's downgrade.
Roland's view
Cavendish expects net debt to ease to c.£86m by the year end, but that's still equivalent to leverage of 1.9x FY27E EBITDA. Given BRCK's subdued profitability and reduced expectations for outer years, I think this is high enough to be a potential concern.
In addition, I think it's worth considering that this is the second profit warning in four months:
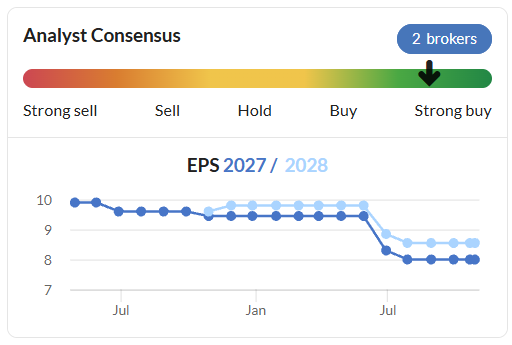
Even with the presumed contribution from the Jacksons acquisition, BRCK hasn't been able to avoid cutting guidance for a second time.
We've often found that companies warning in profit underperform for 12-18 months before delivering a genuine recovery. The StockRanks view this as Contrarian, but until market conditions improve I think it's possible that BRCK is cheap for a reason.
I'm going to move our view down by two notches to AMBER/RED today to reflect the growing risk from rising leverage and the seemingly weaker outlook for earnings.
The caveat to this is that if the housing market does pick up decisively (remembering that it's Budget Day today) then BRCK's profits could recover strongly, potentially providing an attractive recovery play.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on BRCK (6)
Comments here are also visible in the Daily Stock Market Report
BRCK (LON:BRCK)
Always sceptical of companies that engage in a lot of acquisitions.
agreed - its all about the detail though - for exampe, Norcros (LON:NXR) have done a fairly decent job at improving te overall quality of their buisness by using good targetted acquisitions whilst dithcing parts of their buisness that dont provide good whatever RO.. stat you want to use.
Bricks initial plan should have been simple - they spent £100 mill on two cladding companies and those companies had enough work due to backlogs that they should have been able to mostly repay the debt within close to 5 years - or certainly a big enough chunk that even if there was a dropoff its kinda paid for itself - in that regard hitting acquisition targets and delivering simple real clean cashflow is what its all about. the acquisitions were a bit sketchy in that the acquired companies had made ridiculous hay at the start of the cladding crisis delivering crazy good margins (before they bought) - over time it was obvious that the supply would kinda catchup with demand - no biggie if they can leverage things within the other stuff they do.
there seems to be zero honesty from then company though - they say its kinda ok - blame the middle east and then well thats another £ 5 mill of bottom line profit - without really fully explaining why its £5 mill off the bottom line - imho thats a huge miss for company with adequate controls in place - following on from similar and aligned with debt increase - it kinda shows that its currently a mess. the magin of safety needed here with tne debt levels is slipping away somewhat - they are still makig profits and should be able to "service the debt" - but thats not enough to make it an investible business - seeks like at present they are very much less than the sum of the parts - a terrible place to be for an acquisition led company.
Thank you Roland, your analysis and subscriber comments have given me pause for thought on adding to our starter position. Frank Hanna used to be joint CEO of MBH in which we have a full holding and is also struggling but carefully run. I can't help thinking FH has a point to prove but I'll wait for their HY before taking any action.
I am "building" a small stake in BRCK (LON:BRCK) and did dip in again today on the drop. I am hoping for something positive in the Budget, but also the 7% yield will help "cement" its position in my portfolio.
I have written several times recently on how hard it is in Housebuilding with costs all round still on the up and issues like the building levy hardly doing much for the bull case. Housebuilders margins are under great pressure and I would not be surprised to see housing starts no where near what the Government is expecting, More adroitly they will have been sitting on their hands until the latest version of ' Help to buy' which to me seems better than the last scheme (albeit not if you are in London) comes on stream. Incentives will abound in the spring of 27 me thinks so is optimisim just deferred, yet again.
Well is this the catalyst for recovery? Volume brick suppliers are in the forefront here so is it idle speculation to think some stock building is happening which would account for some of the increase in borrowings?
The chart suggests a bottoming out around 40p so less than 10% from where we are. If you believe UK will build build build then that would be an entry point. One wonders how safe the dividend is given the indicated 'grim outlook'
Is there a read across to other heavy end building materials suppliers
BRCK (LON:BRCK)
Horrendous update here - you have one job if go on acquision trail - you need to ensure acquisitions are sound enough that they pay for themselves - at the very time the company needed the proof that the acquisition strategy is working exactly the opposite is happening - debt up again materially - core profits cratering and there is a new acquisition that again complicates all the numbers. The huge red flag to me is the jump in net debt - I just can’t get that to make sense on any level.
Always sceptical of companies that engage in a lot of acquisitions.
It raises risk a lot because the result is unpredictable.
They usually overpay, otherwise why would the acquirer be happy to sell at that price.
Integration of the two entities especially IT systems is always harder than it first appears.
And it is probably empire building by the directors who are more interested in looking at other companies than running their own firm.
A company can grow organically year by year making good profits if it is well run. This is all shareholders want and something that directors should be laser focused on.
BRCK (LON:BRCK)
Always sceptical of companies that engage in a lot of acquisitions.
agreed - its all about the detail though - for exampe, Norcros (LON:NXR) have done a fairly decent job at improving te overall quality of their buisness by using good targetted acquisitions whilst dithcing parts of their buisness that dont provide good whatever RO.. stat you want to use.
Bricks initial plan should have been simple - they spent £100 mill on two cladding companies and those companies had enough work due to backlogs that they should have been able to mostly repay the debt within close to 5 years - or certainly a big enough chunk that even if there was a dropoff its kinda paid for itself - in that regard hitting acquisition targets and delivering simple real clean cashflow is what its all about. the acquisitions were a bit sketchy in that the acquired companies had made ridiculous hay at the start of the cladding crisis delivering crazy good margins (before they bought) - over time it was obvious that the supply would kinda catchup with demand - no biggie if they can leverage things within the other stuff they do.
there seems to be zero honesty from then company though - they say its kinda ok - blame the middle east and then well thats another £ 5 mill of bottom line profit - without really fully explaining why its £5 mill off the bottom line - imho thats a huge miss for company with adequate controls in place - following on from similar and aligned with debt increase - it kinda shows that its currently a mess. the magin of safety needed here with tne debt levels is slipping away somewhat - they are still makig profits and should be able to "service the debt" - but thats not enough to make it an investible business - seeks like at present they are very much less than the sum of the parts - a terrible place to be for an acquisition led company.