Can Hotel Chocolat bounce back after 75% drop?

Hotel Chocolat shares fell by 50% on Tuesday morning, after the upmarket chocolatier hit the market with a profit warning and said it would scale back its overseas expansion programme.
Shares in this former high flyer have now fallen by more than 75% since the start of 2022.
It’s a shocking reversal for investors. As recently as March, the company said that it had “a clear line of sight” to profitability in the US and Japan. While the core UK business appears to be performing more strongly, cost headwinds and restructuring costs are expected to lead to lower profits next year.
Hotel Chocolat’s market cap has dropped to c.£165m at the time of writing. That’s less than the £229m market cap achieved in the company’s 2016 IPO.

As shareholders or potential investors, I think we each need to decide whether this historically expensive stock now offers value.
At times like this it’s important not to anchor on past share prices. What’s happened before won’t necessarily happen again. Tuesday’s update suggests to me that Hotel Chocolat’s growth rate and cost structure are likely to be very different over the next few years. This will be reflected in its profits and valuation.
Let’s start with a look at the main points from Tuesday’s trading update.
FY22 trading: healthy
Hotel Chocolat’s underlying results for the year ended 26 June appear to be fairly healthy. Sales rose by 37% to £226m, ahead of the £215m consensus estimate shown by Stockopedia.
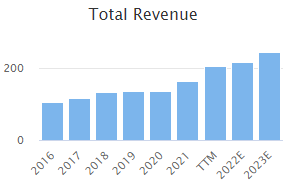
Full-year adjusted pre-tax profit is expected to be in line with market consensus, which is given as £22m (FY21: £10.1m).
The trouble starts with an admission that statutory profit for FY22 is “expected to be a loss”. This is due to impairment charges and costs arising from an ominous-sounding “internal business review”.
Overseas: exit costs
The majority of the extra costs that will be reported appear to relate to Hotel Chocolat’s near-total withdrawal from its international operations.
Japan: The company operates through a joint venture in Japan. This generated £5m of retail sales during the final six months of calendar 2021. Unfortunately, this loss-making business appears to have been built at a high price.
Hotel Chocolat loaned £23m to the JV between 2018 and 2022. According to Tuesday’s update, it’s now likely that these loans will be written off in full.
In mitigation, the company says its Japanese JV has suffered three consecutive years when peak sales (Valentine’s/White Day) have been impacted by Covid restrictions.
Going forward, funding will only be provided for essential working capital. However, the JV will be free to seek other sources of growth funding. This reads to me like Hotel Chocolat has decided to leave its Japanese partner to sink or swim. I suspect the former may be more likely.
USA: US sales totalled £2m during the six months ended 26 December 2021. The group had a small network of stores in the US, but these have now been closed (except one, which is due for closure).
As a result, Hotel Chocolat expects to report £3m of provisions relating to these store closures.
From FY23, US operations are expected to be online and wholesale only.
UK market “can be a lot bigger”
UK food brands seem to be a bit like UK rock bands. Only a few ever make it big abroad, especially in the USA. Perhaps Hotel Chocolat should have stayed focused on its home market, which continues to perform well.

Co-founder and CEO Angus Thirlwell now believes that the UK market “can be a lot bigger for us than we thought a year ago”.
The company now plans to focus on four core areas of growth over the next three years:
- VIP loyalty programme
- Digital growth
- Velvetiser hot chocolate system
- Velvetised chocolate cream alcohol drinks
All of these are identified as capex-light growth opportunities with market headroom to expand in the UK.
Mr Thirlwell suggests a number of reasons for investors to be confident of continued UK growth:
- Drinkable products have opened up “new incremental markets” and new sales channels.
- Online business is now three times larger than pre-pandemic (FY19)
- 71% of direct sales are now to VIP loyalty customers (FY21: 44%)
- UK stores are more profitable then pre-pandemic, due to higher sales densities and lower rents
- Unprompted brand awareness has risen from 17% in October 2020 to 23% in April 2021.
- The lifetime value of Velvetiser customers is “materially higher” than for non-Velvetiser customers.
- UK factory capacity increased from 210m pieces in FY19 to 380m pieces for FY23
- Ninefold increase in production capacity for vegan chocolate
- Lease signed for second UK distribution centre
Ahead of today’s update, I was cautiously optimistic about the outlook for Hotel Chocolat’s core UK business. My feeling was that even if profit margins came under pressure from rising costs, the company would be able to continue gaining market share and growing sales.
My view hasn’t really changed, but I think I underestimated the scale of the likely headwinds.
FY23 outlook: lower profits
Unfortunately, margin pressures for the year ahead seem likely to be worse than I expected. Hotel Chocolat’s guidance is for “lower profits in FY23, with the objective of higher profits thereafter”.
Management now has a strategic goal of achieving a 20% EBITDA margin in FY25. This compares to 15% in FY20 and 17% in FY21.
I think it’s possible that the company’s cost base may have become bloated as it expanded during the pandemic. CEO Thirlwell appears to acknowledge this:
"A year of exceptional sales growth following two years of reactionary tactics to the pandemic has left clear opportunities for us to proactively streamline overheads and improve gross margins.”
There’s no new profit guidance for FY23, but there is a useful breakdown of expected margin headwinds:
- Higher cacao prices and UK wages: -3% ongoing
- New warehouse capacity: -3% in FY23, falling to 0% in FY25
- General inflation: -3% in FY23
- Self-help measures: +3% in FY23
My arithmetic suggests that this means Hotel Chocolat expects to see a c.6% reduction in operating margins in FY23. To put this in context, operating margin in 2021 was 8.6%. Margins have peaked at 11% historically, but were already falling before the pandemic:

I think there’s a fairly wide range of uncertainty about the outlook for FY23, but I’d suggest that a 3% operating margin might be a reasonable estimate.
Balance sheet: Hotel Chocolat raised £40m in a placing in July 2021 to fund growth opportunities. Unfortunately, much of that cash now seems to have been used up.
The group had net cash of £53.8m at the end of 2021. By the end of February this had fallen to £27m. Tuesday’s update reported cash on hand of £17m and an undrawn £50m debt facility. I’m assuming this means net cash of £17m.
Although the business has clearly been cash flow negative this year, I don’t think the situation looks too concerning.The loan write-offs in Japan should be a non-cash item, while US store closure costs look manageable to me.
As long as Hotel Chocolat’s UK store estate remains cash flow positive, I don’t think there should be a liquidity problem.
However, I would suggest that Hotel Chocolat’s financial position is not as strong as it seemed six months ago.
FY23 profit estimate: Sales growth is expected to moderate in the short term.
Assuming sales are flat in FY23, then my estimate of a 3% operating margin would imply an operating profit of £6.8m. That’s nearly 45% lower than the £11.9m reported in 2016, the year of the IPO.
My view - fair value?
Based on a £165m market cap, an operating profit of £6.8m would give Hotel Chocolat an earnings yield (EBIT/EV) of 4.1%. That’s not outrageously expensive, in my view, but it’s well below the 6%-8% level I usually view as good value.
On a medium-term view, I think the shares could offer some value from current levels. But the market has now clearly lost confidence in the growth status of this business.
I don’t see any reason to rush in at this stage. I plan to wait for Hotel Chocolat’s full-year results in October. I’d like greater clarity on the group’s cash flow and current-year trading before taking a view on the stock.
Please let me know what you think in the comments below. Is Hotel Chocolat the next Thorntons, or can this former high flyer regain its lustre?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Roland, how much research did you actually do before writing this piece? I find it highly unlikely that you read last summer's placing RNS or even the recent interim accounts... If you had done so you wouldn't be mimicking Paul Scott's twaddle that HOTC have 'squandered' the £40m raised last summer.
"As part of the net proceeds from the Company's £22 million equity fundraising in March 2020, the Company increased its factory footprint from 45,000 sq. ft. to 80,000 sq. ft. providing capacity to support up to £250 million of sales. The net proceeds of the Placing will support the Company's future growth by expanding its factory footprint to 160,000 sq. ft., providing the capacity for the Company to increase sales to c. £500 million. The Company intends, dependent upon the rate of growth, to fund subsequent capacity investments such as installing new production lines from profits."
Now read note 6 of the companies recent interims released in March...
Between 27/06/21 and 27/12/21 they spent £13.5m on freehold property, fixtures & fittings and plant & machinery. We don't know how much they spent in H2 yet, but I'd guess at a range of £5-10m.
Investing in building out future capacity via raising capital when times are good seems smart to me. UK sales accounted for £215m of £226m reported in 2022 and grew 35% YoY.
At the £1.48 IPO price / £167m market cap (another fact you got wrong), UK sales were just £76m.
There is therefore very little logic in the current market cap being almost equal to that of the IPO, the business is multiple times larger and has ~£50m in additional fixed assets on the balance sheet.
Sure, gross margins have fallen slightly, however they are still way above the ~40% level that Thornton's were reporting from 2010-2015 before they were bought by Ferrero.
I'd say this is a screaming buy down at current levels, a recovery to £2+ should be easily achievable given HOTC was trading at £4.50 as recently as 31/03/2022.
I think it is possible to disagree without being as rude as you are. Two people here with great financial experience have gone over the HOTC figures and have broadly agreed. You have just made your first post since you joined 5 years ago - perhaps you should post more often if you have greater insight...
I have never been a shareholder but I will add my view of the business. I buy a lot of chocolate and HC chocolate is very good and I go there for the traditional xmas, easter, valentines etc purchases. Their shop in MK is usually pretty busy especially in the peak season. Thorntons "chocolate" is crap and is presumably bought by people who don't know what chocolate is. You can buy higher end stuff like Godiva which is probably slightly better quality but is much more expensive, my view is HC is a bit like Waitrose that it has a core of middle class customers who value it and are relatively immune to the price of it. That also probably means it has a lowish consumer ceiling. HC I would argue is similar to Fevertree, a premium product for which there is always a cheaper alternative but the buyers like it and stay loyal.
Exactly this. It’s a quality product that is expensive but for the purposes of seasonal gift-giving is an appreciated luxury rather than a £1.50 bar from Lidl.
Govida "higher end stuff" was recently sold in Yorkshire Trading at discount prices so low that it was even lower than Moser Roth and Choceur at Aldi! Godiva is also sold at inflated prices on Cunard's cruise shjps.
Chocolate is a personal taste. I think Godiva is delicious. I thought Hotel Chocolat was so horrible I threw it away. Also reckoned it was way overpriced. Thorntons is palatable and certainly not crap quality. Marks and Spencer sell some delicious chocolate bars. Aldi and Lidl (ditto with Aldi for wine) sell excellent quality chocolate for bargain prices. e.g Moser Roth, Choceur and JD Gross. Their dark chocolate is in different league to Bournville.
I know personal taste is not the way to decide whether Hotel Chocolat (LON:HOTC) is worth investing in. It looked way overvalued until the recent crash. On fundamentals and assuming plenty do like their chocolate, then Hotel Chocolat looks far more tempting now than previously.
If this counts as a profit warning, and I think it does, there will be two more before I buy back in.
Never tried their chocolate, going by all the adverse comments I don't think I will either. Aldi chocolate is ok, I buy it occasionally. As an investment I would have thought Greggs is a better choice. Im considering buying at the moment.
I pop into their (usually empty) shops for a browse now and again but rarely buy anything due to the exorbitant prices. It is possible to buy a very good bar of chocolate from Lidl/Aldi for £1.50. I imagine it will suffer a similar fate to Thorntons.
I'm a fan so I'll put in my tuppence worth. HC is far, far better than Thornton's ever was. I live in Glasgow and the main time I go into the store in Glasgow is at Christmas when it's packed. I then usually order eggs at Easter online. I often buy the chocolat cream alcohol stuff at Christmas for workmates who love it. I don't think Thorntons ever branched in to that. Given my own shopping habits I would estimate it is a very seasonal business, but it is high quality and as far as I can see it isn't in the market to compete with the Lidl take on 'Dairy Milk' in the impulse buy section at the supermarket checkout. As for not breaking the US, if you've ever tasted the absolute crap that Americans think is chocolate then I think the problem is one of abysmal US tastes.
Fair enough , but I do not think that your choice of tastes has anything to do with the valuation of the company.
Thanks
I personally wouldn’t buy any HOTC yet … for me (being a value investor) it needs to drop another 50% :-))
I live in Japan and visited a Hotel Chocolat (LON:HOTC) shop with Japanese friends the other day. There was a lot of talk about how interesting it looked - but everything was so big for Japanese tastes that only very limited items were bought.
Japanese don't like "big" western tastes - and they haven't adapted their business model.
I felt at the time that its days were likely numbered in Japan, just the same as other western brands that don't realise that Japan is different.
Lindt etc, they have shops here - and they break down their chocolate to small sizes and are increasingly popular.
Also, I did buy one box of chocolates, I ate one and felt it didn't have much taste. 2 Japanese friends also ate one and their reaction was muted - and both refused another. They didn't comment negatively, but as I'm English, Japanese people wouldn't want to "offend" me by saying it wasn't very nice - but I've never seen those same people refuse "just one more" lindt etc.
Suffice to say, before visiting - I was interested in investing in the company, but based on that visit alone - I decided against it.
Normal MM activity... download the end of day trade report from the LSE for Hotel Chocolat (LON:HOTC) and look at how few shares were used to drop the price. It's the drop that causes the selling, not the selling causing the drop IMHO!
Around 8.5m shares were traded instead of the average 50K.
What exactly are you implying?
Download the data and analyse it... look at how many shares were traded and at what price. What caused the gap down? Where were the shares traded (price level)? Think volume profile and then you can make up your own mind.
Sorry it’s still not investable for me , even after crashing down about 80% from its highs. There is also at least one further implied profit warning in today’s RNS.
Good luck though.
I can remember a few years back, Greggs being mullered by a heat wave - I fear they have another "headwind" coming, albeit a temporary one.
Two of their shops that I have visited recently are not busy at all. Starbucks ( next to them ) , however , was really busy with customers queuing. Definitely the next Thorntons for me as it’s burning cash like mad.
You're visiting a Hotel Chocolat store in the height of summer. Of course it's not busy. An ice cream van in winter would also be less busy. If you look over the last three years you can see a noticeable uptrend in the share price in winter and a dip in summer. All the other factors in the article above are fair enough but the busyness of a chocolate store in midsummer, when you'd expect it to do most business in Christmas and Easter, I don't think should be a major concern.
It was the same in Winter.
A brand in Cheshire Oaks and in Chester that cannot get customers and compete with the likes of Starbucks is a recipe for disaster.
Thanks