Castings: the market shrugs off cost overruns at a well-defined problem

Analyst’s view:
This is a serious profit warning in percentage terms: the new profit forecast is 30% lower than the prior forecast. However, the share price has barely moved and I agree with this. The reason for the profit warning has nothing to do with demand, or competition, or anything else that might be central to the investment case. Instead, it's a well-defined issue at a particular site, that is already in the past. Forecasts for FY28 and FY29 are unchanged and I am similarly going to leave our stance here unchanged (moderately positive).
Down 1.5% at 272.9p (£119m) - Trading Update and Notice of Results (profit warning)
Castings PLC... the leading iron casting and machining group primarily focused on the European heavy truck market, announces a trading update in respect of the year ended 31 March 2027...
This is quite a serious profit warning in percentage terms.
The group's subsidiary William Lee, based in Derbyshire, is a major parts producer for truck manufacturers. It produces over 25,000 castings daily - or at least it usually does, when it has power:
...the third-party power supply issue at our William Lee site continued to impact results in the first half of the year. As previously reported, power was restored at the end of May, but the incremental cost of catching-up production continued beyond that date.
There have been cost overruns in recovering from this incident:
Revenue: still running in line with expectations for FY27 (£181.1m)
Adj. PBT: expectations reduced to a level broadly consistent with FY26, excluding historical R&D tax credits.
In the prior year, PBT was £10.3m, but this included £1.2m of R&D tax credits, of which only £0.4m were attributable to FY26.
This suggests that we should now expect adj. PBT of about £9.5m for FY27.
Estimates: thanks to Canaccord Genuity for publishing on Castings today. Their new adj. PBT estimate for FY27 is £9.0m (previously £12.8m).
For FY27 and FY 28m, they expect adj. PBT of £14.8m and £16.6m, respectively (unchanged).
Graham's view
As I noted at the top, this is a serious profit warning in percentage terms: the new forecast is 30% lower than the prior forecast.
However, the share price has barely moved and I agree with this. The reason for the profit warning has nothing to do with demand, or competition, or anything else that might be central to the investment case.
Instead, it's a well-defined issue at a particular site, that is already in the past.
It's correct to shrug off this type of thing, in my view - unless it is part of a pattern of mishaps.
It's also relevant that the company has a strong net cash position (still expected to be over £20m at year-end), so there is no urgency around the exact profit figure that the company produces in the current financial year.
Forecasts for FY28 and FY29 are unchanged and I am similarly going to leave our stance here unchanged (moderately positive).
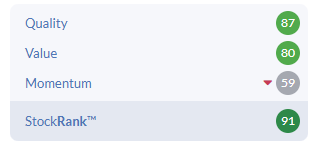
The StockReport is even more positive on this one than I am, classifying it as a Super Stock:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Castings (2)
Comments here are also visible in the Daily Stock Market Report
fair comment Graham, one risk not mentioned is if this has incovenienced their customers and they might go elewhere, reputational damage etc.
Thank you for this coverage Graham, I like what CGS do, on renewables too now, and how they report. We also like their dividend record so we'll continue to hold and wait for better times.