Cavendish: first-half revenue falls to £22.8m, putting the £60m forecast at risk

Analyst’s view:
This is a stock I've championed in the past and I must admit that I'm starting to question myself. On the bright side, I do expect the balance sheet to remain very strong and for cash to continue to cover a large chunk of the market cap. But if I'm honest, the wait for a rebound in IPO activity has taken much longer than I expected. My optimism that AIM might see a rebound within the space of a few years was misplaced.
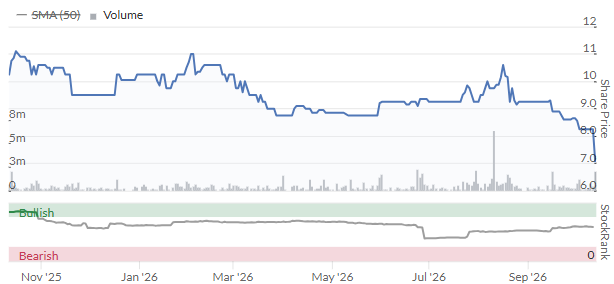
Down 16% at 6.97p (£27m) - Half Year Trading Update
This is not a great update:
Against the current market backdrop of increased macroeconomic challenges, the Group revenue for the period is expected to be about £22.8m.
That level of revenue leaves the company with another £37m to generate in H2, if it's to meet market expectations of £60m. It requires an H1:H2 split of 38:62.
It's also a significant drop-off from prior years: H1 revenue was £28.5m last year, and £27.7m the year before that.
For some further detail, they tell us that the revenue mix was "balanced across all service lines". And they've been active in the LSE's new Private Securities Market - share auctions for private companies.
Outlook: they are able to promise very little.
Despite challenging conditions in the year to date, we are increasingly seeing good prospects being generated from several areas of targeted investment in the prior periods, including our business outside London. We have a healthy pipeline of both public and private transactions, including IPOs. However, as we have seen in the first half of the year, completion timetables, and therefore revenue visibility, remain difficult to predict. Against this backdrop, we will continue to exercise strict cost controls.
Graham's view
Revenues can be very lumpy, so I'm not going to rule out the possibility of a really strong H2 that brings full-year revenues close to that £60m forecast.
At the same time, it's hard to build an investment thesis on numbers that seem to be totally unpredictable, and also appear to be going in the wrong direction at the moment.
This is a stock I've championed in the past and I must admit that I'm starting to question myself.
On the bright side, I do expect the balance sheet to remain very strong and for cash to continue to cover a large chunk of the market cap. At the full-year results, the cash balance was £19m with no debt, and tangible equity was £25m.
The company has said that it will "exercise strict cost controls" in light of the poor visibility it enjoys right now, and this should help to protect the cash balance.
And so with a market cap of just £27m today, I still think this makes for an interesting value investment.
But if I'm honest, the wait for a rebound in IPO activity has taken much longer than I expected. And I don't see signs of anything changing in 2027. There has been a little bit of activity on the LSE's main market in recent times, but there has been almost nothing on AIM (the market where Cavendish are strongest).
I'll take us down to neutral today on the grounds that the company is now likely to miss full-year expectations. Pre-tax profits last year were £1.5m on £56.9m of revenues, and it seems to me that Cavendish will be doing well to repeat that this year.
So in summary, the main attraction here is the balance sheet. If a larger bank were to buy Cavendish, I'd expect them to pay a nice premium to balance sheet value (£19m cash/£25m tangible equity). But in the absence of a takeover, the case for investing here is unfortunately looking weaker and weaker. My optimism that AIM might see a rebound within the space of a few years was misplaced.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Cavendish (8)
Comments here are also visible in the Daily Stock Market Report
Cavendish (LON:CAV)
I have warned in the past, and had a proper look again this afternoon.
Unfortunately, this is a RED as it can get.
If the cash gets lower then it is game over.
All the best
It is very disappointing. G
Has to do with the FCA rules. Another FY with lower revenues and they have a serious problem.
Not sure if this was picked up and mentioned in your analysis this morning.
All the best
Fair write up on Cavendish (LON:CAV) Graham, I don't think it can stay Green when they are so many unknowns.
Revenue is -27% year on year for H1, like you say the might make it up in H2 but there is considerable risk that they won't. They certainly haven't claimed that they think they will hit the £60 million.
I sold half my Cavendish (LON:CAV) holding a Month or so ago thankfully, seems a good price now so I think I'll hold onto the what I have left.
Then again I have been saying the last 18 Months it looks a good price, yet it keeps going down.
For a broker (!) Cavendish (LON:CAV) 's update today is too opaque. They should have spelled out the decline in H1 revenues, and made some mention of margins. 2/10
I sold this morning and ate the loss. Was hoping that their operational leverage might come through but they are clearly finding the market tough / revenue difficult to come buy.
The fact that they still operate with 2 CEO's is odd to me. I wonder if an appointment from the outside needs to be introduced at the top level instead of this.
I sold half my Cavendish (LON:CAV) holding a Month or so ago thankfully, seems a good price now so I think I'll hold onto the what I have left.
Then again I have been saying the last 18 Months it looks a good price, yet it keeps going down.
I agree, very disappointing H1 results.... and not enough information and colour in the Trading Update for investors....!
The only silver lining I can see is that IPO activity has picked up quite markedly in Sep and Oct so far. My rough count is like up to 10 IPOs already in the bag between Sep-Oct... and we still have another few weeks of new IPOs to be announced before the season closes in Dec.
However, I think Cavendish (LON:CAV) did none of the IPOs.... hence their profit warning today... bad luck, or are they struggling in a competitive market? They make enthusiastic sounds about their IPO pipeline, but its all too vague...
My research shows, however, that they are continuing to grow the number of companies that they are appointed broker for, so at least that metric is healthy and forms a nice recurring income, as well as optionality for extra income for transactions, etc.
(I hold in the Boon Fund)