Daily Stock Market Report (Tue 13th Oct 2026) - CAV, GNC, IPX, MARS, WTB

Good morning! There is no one major overnight news story to report, so let’s just bring you a few of the headlines:
Saudi vs Houthis: Saudi has intercepted more missiles launched by the Houthis in Yemen.
UK economy: the IMF has upgraded its forecast for UK economic growth this year from 1% to 1.3%. Growth is then expected to moderate in 2027.
The well-known dating app Bumble (NSQ:BMBL) (listed on the NASDAQ) has received takeover interest, according to the Wall Street Journal. Its shares rose 50% yesterday.
Now let's take a look at today's UK company news…
Overnight market movements:
The FTSE is up 0.3% at 10,675
S&P 500 is down 0.1% at 7,800
Brent crude (December) is down 1.1% at $105.50/bbl
Gold is up 0.5% at $4,190oz
Bitcoin is up 0.6% at $83,500
Ed Sheldon joins me today.
All done for today, thank you.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BP (LON:BP.). (£92bn | SR99) | Updated Q3 guidance. Reported upstream production (mboe/d) 2,190 to 2,240 (previously 2,100 to 2,250). Refining throughput (mb/d) 1,375 to 1,405 (previously 1,300 to 1,360). | ||
Jardine Matheson Holdings (LON:JARB) (£12.4bn | SRN/A) | 2026 underlying earnings are expected to be between US$5.50 and US$5.65 per share, upgraded from previous guidance of US$5.33 per share. Paying £250m for the 50% stake in Gammon Construction owned by Balfour Beatty, making Jardines the sole owner with immediate effect. | ||
Land Securities (LON:LAND) (£5.1bn | SR39) | Completed the acquisition of an additional 10% stake in Bluewater, one of the top-10 retail destinations in the UK. Paying £95m. | ||
Whitbread (LON:WTB) (£4.2bn | SR34) | SP +2% | AMBER/GREEN= (Graham) [no section below] | |
Balfour Beatty (LON:BBY) (£4.2bn | SR78) | Sold its 50% shareholding in Gammon Construction, the Hong Kong based contractor, to Jardine Matheson for £250m. | ||
Plus500 (LON:PLUS) (£2.4bn | SR61) | Conditionally agreed to acquire Hedge Capital Markets Inc. This marks Plus500’s entry into the SEC-regulated segment of the US market. In Q1 2027, PLUS will consolidate the US product suite, from futures and prediction markets to stocks, options, ETFs and other SEC-regulated products, into a single application. | ||
Bellway (LON:BWY) (£2.2bn | SR48) | Total housing completions up 10.8% to 9,695 homes. Underlying operating profit increased by 5.6% to £320.6m. Outlook: Customer demand remains constrained by economic uncertainty and affordability pressures, with mortgage interest rates above prior-year levels. Targeting total completions of between 9,000 and 9,400 in FY27. Underlying operating margin is expected to reduce further. | PROFIT WARNING? (GN note: expectations for 2027 were already weak, so I’m not sure if this reduces expectations further.) Update: SP +1%, so the market was already anticipating this. | |
Greencore (LON:GNC) (£2.1bn | SR42) | Q4 pro forma revenue increased 4.5% to £1,036m. Underlying profit momentum was ahead of expectations. “We now anticipate FY26 Adjusted Operating Profit for continuing operations (UK business) to be approx £248m, ahead of current market expectations and previously raised guidance.” (current consensus £238m). | AMBER/GREEN = (Ed S) | |
Ninety One (LON:N91) (£2.1bn | SR48) | AUM £181.4bn (30 June: £184bn). | ||
Oxford Instruments (LON:OXIG) (£1.6bn | SR71) | H1 order intake up nearly 44%. Reported revenue grew by approximately 8%. Adjusted operating margin is expected to progress by over 100 bps. Confidence in delivering full year results in line with market expectations. | ||
Integrafin Holdings (LON:IHP) (£1.3bn | SR75) | Quarter end funds under direction on the Transact platform of £86.5bn, up 17% year-on-year. Net inflows to the Transact platform of £0.9bn in Q4. Total underlying administrative expense growth is expected to slow to c.3% in each of FY26 and FY27. Cost savings have been weighted towards H2. Other guidance issued at the HY26 results remains unchanged. | ||
Bytes Technology (LON:BYIT) (£1.06bn | SR70) | “The Board continues to expect gross profit growth for the full year in the low to mid-teens in percentage terms, with low to mid single-digit percentage growth in operating profit. This is due to “cost normalisation” as previously flagged costs return to normal levels. “...the Board expects operating profit to grow more broadly in line with GP from FY28, with operating leverage building thereafter.” Buys CyberOne for initial consideration of £19.4m. | ||
Michael Page (LON:PAGE) (£638m | SR81) | Gross profit +1.5%. The Board expects 2026 operating profit to be in line with company compiled consensus of c. £29m. | ||
Tharisa (LON:THS) (£362m | SR99) | Quarterly PGM production of 41.0 koz (Q3 FY2026: 39.6 koz), bringing FY2026 PGM production to 153.7 koz (FY2025: 138.7 koz) in line with guidance. Production guidance for FY2027 is set at between 150 koz and 170 koz PGMs. | ||
YouGov (LON:YOU) (£316m | SR82) | Results for the year ended 31 July 2026 & Launch of share repurchase programme | Revenue +2%. Adjusted operating profit down 9% (£54.3m). Net debt £142m. “The Group is confident in the delivery of adjusted operating profit growth for FY27 of between 7% and 12%, in line with current market expectations.” Believes there’s a “disconnect between the prevailing share price and the Company’s intrinsic value” and launches £15m share buyback. | |
Marston's (LON:MARS) (£295m | SR61) | SP +21% | AMBER/GREEN ↑ (Graham) [no section below] | |
Victorian Plumbing (LON:VIC) (£270m | SR80) | Group revenue increased by c.11% to c.£344m in FY26. Group adjusted PBT is expected to be c.£22m (FY25: £21.8m), ahead of market expectations. Group year-end cash was c.£25m. | ||
Berkeley Energia (LON:BKY) (£195m | SR29) | Has provided a response to the Australian Securities Exchange (ASX) in relation to a query received from ASX regarding recent trading in the company's securities. | ||
Reach (LON:RCH) (£150m | SR59) | Group revenue down 14.1% with digital revenue down 20.3%. The group maintains its cautious outlook for digital revenues and remains on track to deliver in line with market expectations for the full year. | ||
Impax Asset Management (LON:IPX) (£129m | SR78) | On 30 September, the company's AUM totalled £20.0bn. Saw £2.4bn of net outflows during the quarter. | AMBER ↓ (Graham - I hold) | |
Kodal Minerals (LON:KOD) (£62m | SR23) | Q3 production was 27,234 dry metric tonnes of spodumene concentrate grading 5.29% Li2O. Year to date production of 80,429 DMT of spodumene concentrate. Full-year production guidance range of 105,000 to 115,000 DMT of spodumene concentrate with an expected unit production cost of between $600 and $610. | ||
Angling Direct (LON:ANG) (£37m | SR92) | Group revenue up 5.1% to £56.4m, adjusted EBITDA up 11.9% to £4.3m, adjusted profit before tax up 11.2% to £3.3m, net cash of £14.5m at 31 July 2026. The company is trading in line with full-year market expectations. | ||
Cavendish (LON:CAV) (£32m | SR58) | Group revenue for the period is expected to be about £22.8m. Has a healthy pipeline of both public and private transactions, including IPOs. | AMBER ↓ (Graham) | |
iFOREX Financial Trading Holdings (LON:IFRX) (£32m | SR27) | Has announced a strategic collaboration with TipRanks, a leading financial research platform, and WNSTN, an AI infrastructure platform. | ||
Gelion (LON:GELN) (£29m | SR3) | Has entered into a co-funded PoC with a top 5 global automotive original equipment manufacturer, to jointly undertake a pilot program to test and evaluate Gelion's proprietary Nano-Encapsulated Sulfur (NES™) cathode active material under conditions relevant to electric vehicle battery applications. | ||
Abingdon Health (LON:ABDX) (£27m | SR21) | Total revenues for FY26 grew 32% to £11.3m, adjusted EBITDA loss improved to £1.5m (FY25: £2.6m), loss before tax of £2.0m (FY25: £3.5m), cash and cash equivalents of £2.9m. Expects continued revenue growth will take the group to a further improved EBITDA position for the year ending 30 June 2027. | ||
Haydale (LON:HAYD) (£22m | SR4) | For FY26, now expects: revenue of £5.0m compared with market expectations of approx. £8.0m, an adjusted EBITDA loss of approximately £2.69m compared with market expectations of approx £2.0m; gross margin of approximately 44% (compared with 37.9% at H1 FY26) and a year-end cash position ahead of market expectations. Will re-base SMCC’s activities around a more capital-light model. Board believes current trading business will achieve operating breakeven during H1 FY27. | ||
Energypathways (LON:EPP) (£19m | SRN/A) | Has closed £1.75m fundraising. Funds will be deployed to accelerate the company's MESH project and provide working capital. Trading in the company’s shares has resumed today. | ||
Orchard Funding (LON:ORCH) (£13m | SR96) | Lending volume down 5.1% to £57.8m, total revenue down 2.6% to £5.0m, PBT up 32% to £2.5m, EPS up 23% to £8.9m, interim dividend of 2p. Remains optimistic about continued strong performance but the next six months will be challenging. | ||
Aptamer (LON:APTA) (£11m | SR7) | Revenue up 28% to £1.5m, adjusted EBITDA loss of £2.3m (2025: £2.2 million), cash balance at 30 June 2026 of £4.4m, increase in sales pipeline from £4.8m at 30 June 2026 to £7.0m at 21 September 2026. |
Graham's Section
Cavendish (LON:CAV)
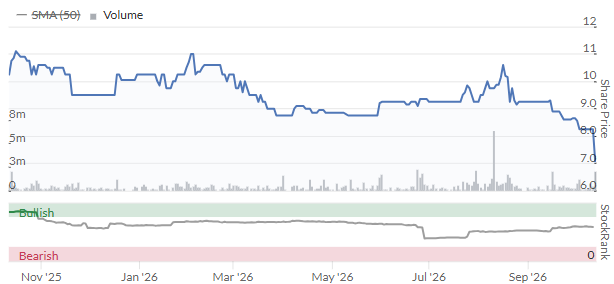
Down 16% at 6.97p (£27m) - Half Year Trading Update - Graham - AMBER ↓
This is not a great update:
Against the current market backdrop of increased macroeconomic challenges, the Group revenue for the period is expected to be about £22.8m.
That level of revenue leaves the company with another £37m to generate in H2, if it's to meet market expectations of £60m. It requires an H1:H2 split of 38:62.
It's also a significant drop-off from prior years: H1 revenue was £28.5m last year, and £27.7m the year before that.
For some further detail, they tell us that the revenue mix was "balanced across all service lines". And they've been active in the LSE's new Private Securities Market - share auctions for private companies.
Outlook: they are able to promise very little.
Despite challenging conditions in the year to date, we are increasingly seeing good prospects being generated from several areas of targeted investment in the prior periods, including our business outside London. We have a healthy pipeline of both public and private transactions, including IPOs. However, as we have seen in the first half of the year, completion timetables, and therefore revenue visibility, remain difficult to predict. Against this backdrop, we will continue to exercise strict cost controls.
Graham's view
Revenues can be very lumpy, so I'm not going to rule out the possibility of a really strong H2 that brings full-year revenues close to that £60m forecast.
At the same time, it's hard to build an investment thesis on numbers that seem to be totally unpredictable, and also appear to be going in the wrong direction at the moment.
This is a stock I've championed in the past and I must admit that I'm starting to question myself.
On the bright side, I do expect the balance sheet to remain very strong and for cash to continue to cover a large chunk of the market cap. At the full-year results, the cash balance was £19m with no debt, and tangible equity was £25m.
The company has said that it will "exercise strict cost controls" in light of the poor visibility it enjoys right now, and this should help to protect the cash balance.
And so with a market cap of just £27m today, I still think this makes for an interesting value investment.
But if I'm honest, the wait for a rebound in IPO activity has taken much longer than I expected. And I don't see signs of anything changing in 2027. There has been a little bit of activity on the LSE's main market in recent times, but there has been almost nothing on AIM (the market where Cavendish are strongest).
I'll take us down to neutral today on the grounds that the company is now likely to miss full-year expectations. Pre-tax profits last year were £1.5m on £56.9m of revenues, and it seems to me that Cavendish will be doing well to repeat that this year.
So in summary, the main attraction here is the balance sheet. If a larger bank were to buy Cavendish, I'd expect them to pay a nice premium to balance sheet value (£19m cash/£25m tangible equity). But in the absence of a takeover, the case for investing here is unfortunately looking weaker and weaker. My optimism that AIM might see a rebound within the space of a few years was misplaced.
Impax Asset Management (LON:IPX)
Down 12% at 89.6p (£114m) - Q4 AUM update - Graham - AMBER ↓
[At the time of publication, Graham has a long position in IPX.]
We had been AMBER/RED on this (e.g. here), until I got excited at the Q3 update in July, when I switched up to AMBER/GREEN. In hindsight, it looks like I read too much into the improved Q3 outflows
Outflows in Q4 have soared to £2.4 billion. This compares with £2 billion in Q2, or only £1 billion if we exclude the loss of an investment trust to the Saba campaign.
When I looked at that Q3 update, I read it as a £1 billion outflow. Given that the last-seen cash balance of £46m was already covering a decent chunk of the market cap, almost putting this stock in the deep value category, I was happy to take a more optimistic point of view.
But now the quarterly outflows have increased to over £2 billion again, and this time they aren't even masked by positive market movements.
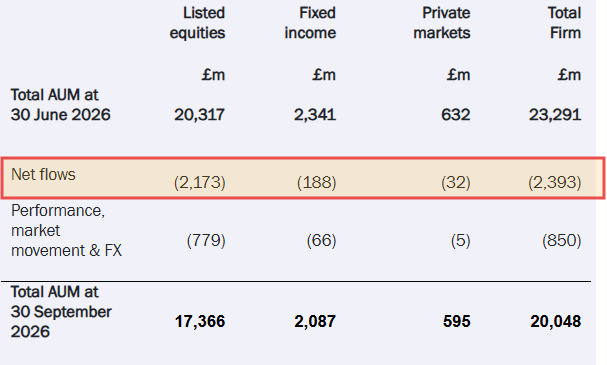
Let's hear from CEO Ian Simm (emphasis added by me):
"The net outflows for the quarter were concentrated in actively managed listed equities (~75% of AUM) and principally reflect the 'lag effect' of clients responding to the previous weaker investment performance of some strategies.
"Between 2023 and 2025 these strategies were challenged by an equities market dominated by a narrow part of the technology sector and our thematic strategies' investment opportunities were out of favour.
"However, since the start of 2026 there has been a significant change in equities markets, with environmental themes in particular performing more strongly, as investors reconsider areas such as energy security, resource efficiency and electrification, particularly in the context of the build out of AI... As our performance track record strengthens, we expect to see our own flows improve.
Graham's view
The quarterly net outflow is 10% of starting AUM, which is very poor no matter which way you look at it.
For the financial year as a whole, net outflows (£7.8 billion) are an incredible 30% of starting AUM. And it's not as outflows were positive before then, either.
Forecasts at Equity Development have been cut due to the disappointing AUM news. They leave FY26 profit forecasts unchanged, but they reduce the FY27 net income forecast by 14% to £10.8m, and the adjusted EPS figure by 12% to 10.4p.
I'm cutting our stance on this today to neutral. However, I don't want to get any more negative than that, due to the considerable asset backing here.
Impax had cash reserves of £46m as of March 2026. Equity Development have year-end net cash forecasts of c. £61-62m for the next two years.
So in my view, at a market cap of £114m, this is not all that far away from deep value territory, from a balance sheet perspective.
I'd also like to emphasise that the company is still profitable with an expected after-tax profit margin of 8-10% over the next two years.
So there's a lot to dislike - front and centre in that regard being the very heavy outflows. I don't think there's been a quarterly inflow here since soime time in 2022. Returns have not been good enough and investors have lost interest as sustainability has gone out of fashion in favour of AI and other technology trends.
But everything has a price and I find it hard to believe that Impax is undervalued at this level. Hopefully Ian Simm will prove to be correct, and flows will improve with the help of recent strong fund performance. As that is just a hypothesis at this point, I think a neutral stance is fair.
The destruction of the share price is quite a sight to behold:
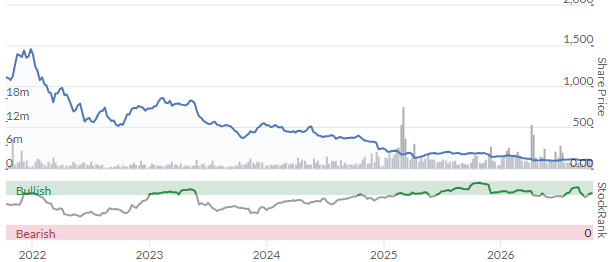
I turned positive on this too soon, and added a small starter position to my portfolio to help focus my attention on it. Thankfully, I've not been tempted to buy any more - and I have no intention of doing so in the near-term!
Edward's Section
Greencore (LON:GNC)
Up 1% at 265p (£2.1bn) - Q4 Trading Update - Ed S - AMBER/GREEN =
UK convenience food manufacturer Greencore has today provided a trading update for the quarter ended 25 September and there are numerous positives:
Trading performance:
Q4 pro forma revenue increased 4.5% to £1,036m, reflecting strong volume growth and recovery of labour, packaging, and certain raw materials inflation.
Manufactured pro forma volume growth in Q4 accelerated to 2.1%, ahead of the wider grocery market at 0.5%, with chilled categories including salads, dips, quiche and sandwiches performing strongly.
Innovation remained an important contributor to growth with 167 new products launched during Q4.
Underlying profit momentum was ahead of expectations, driven by a combination of volume growth and continued margin improvement.
Synergy delivery from the Bakkavor acquisition has continued to progress strongly.
FY26 pro forma revenue grew 3.6% to £3,378m.
FY26 manufactured volume grew 1.1%, ahead of the wider market at 0.5%.
Net debt (excluding lease liabilities) is expected to be approximately £600m at FY26 (net debt/adjusted EBITDA of approx. 1.8x versus medium-term target: 1-1.5x).
“Greencore has had a monumental year, and we finished it with a strong performance in Q4. We grew volume ahead of the market, drove strong profit growth and we continue to make strides in our integration with Bakkavor. That performance means we are in a position to further upgrade our full year guidance.”
Outlook:
Now anticipates FY26 adjusted operating profit for continuing operations (UK business) to be approximately £248m, ahead of current market expectations and previously raised guidance.
Q1 FY27 trading has started positively, with volume momentum continuing from Q4 FY26.
Has had further success cross-selling its new categories into existing customers and has won a further 75bp of annualised revenue growth (c.£30m of annualised revenue) across salads, ready meals, dips and breads, which will launch across Q2 and Q3 FY27.
The group continues to progress the sale of its US business, which has been treated as a discontinued operation and held for sale asset. The US business continues to trade positively and in line with expectations.
“We have real momentum in our business and Greencore has never been in a stronger place. Customers want to do more with us and we are seeing encouraging progress from cross-selling categories across our expanded customer base.”
Notes worth highlighting:
Current market consensus for FY26 adjusted operating profit for continuing operations (UK business only) is £238m (with a range of £236-241m), which was compiled from 8 covering analysts.
Previous guidance, provided as part of the Q3 trading update, was FY26 adjusted operating profit of £234-242m (continuing operations, UK business only).
Pro forma growth reflects the new Greencore: Q4 growth reflects Greencore and Bakkavor for the entire period (both current and previous year) and removes the Bristol facility (which was disposed in January 2026) from the previous period; 12-month growth reflects Greencore 12 months, Bakkavor since acquisition and Bristol up to date of disposal (both current/prior year).
Ed’s view:
This is a sound update, with solid revenue growth in Q4 and news of better-than-expected adjusted operating profit for FY26. What jumps out to me is the language from management – the company had a ‘monumental’ year, currently has ‘real momentum’, and has ‘never been in a stronger place’.
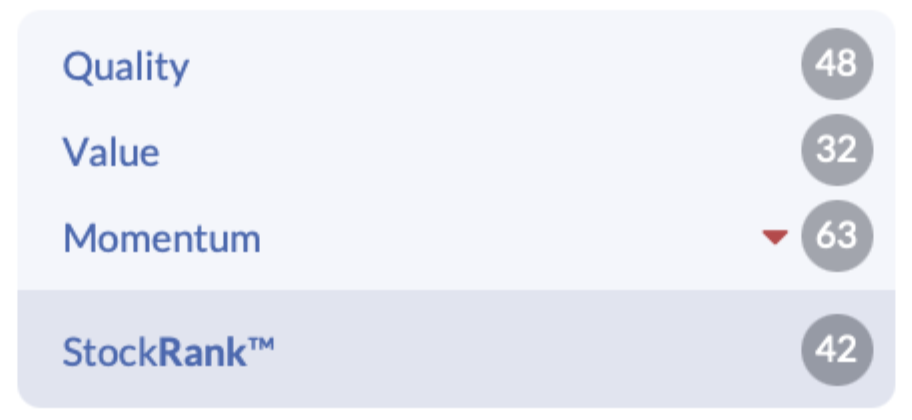
What’s interesting is that Greencore sports a StockRank of just 42 at the moment. It seems the StockRank took a huge hit in late May when the company’s interim results led to a sharp drop in the share price.
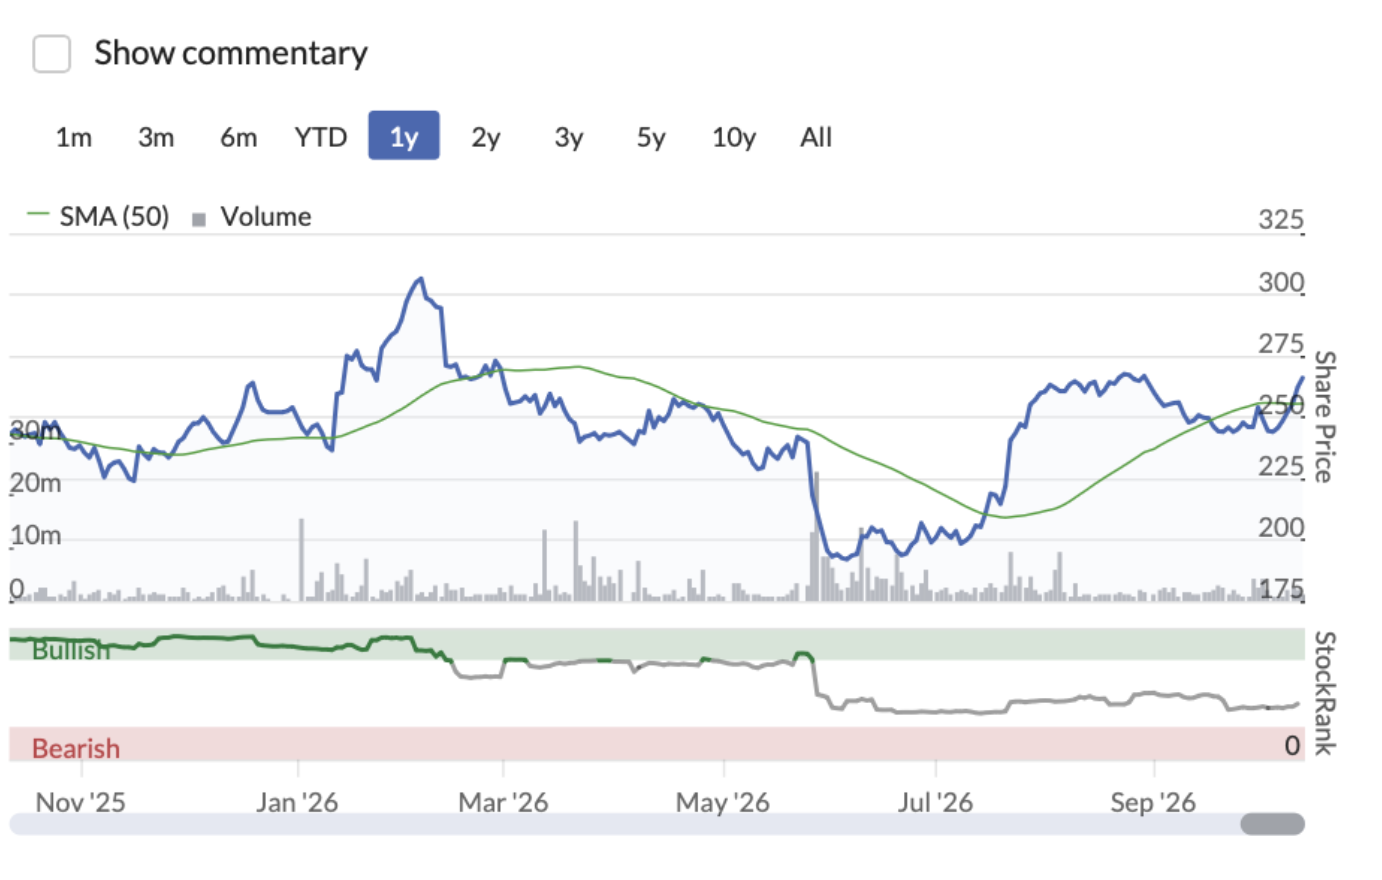
I suspect that it’s only a matter of time until we get a material jump in the StockRank. Because the company clearly has operational momentum at the moment (there was another positive update back in July in which guidance was raised) – and earnings forecasts are rising:
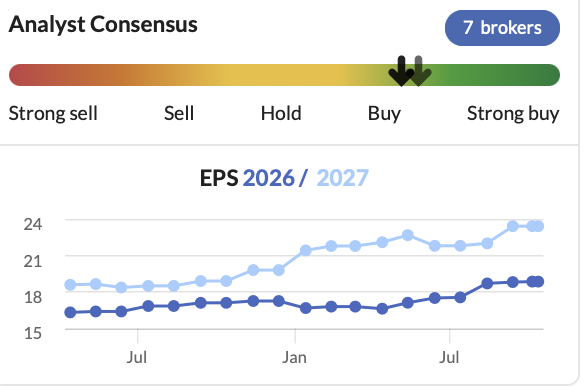
Meanwhile, it looks relatively cheap on a forward-looking P/E ratio of 11. Additionally, the share price is rising and is now back above both the 50-day and 200-day moving averages.
Looking beyond today’s update and the StockRank, one thing that is worth highlighting here is insider buying. When the stock fell sharply in late May, a number of directors including the Chair stepped up to buy shares.
Since then, we’ve seen more insider buying activity with the Chair making some large purchases (e.g. 350,000 shares @ £2.38 on 22 July). This is bullish, in my view.
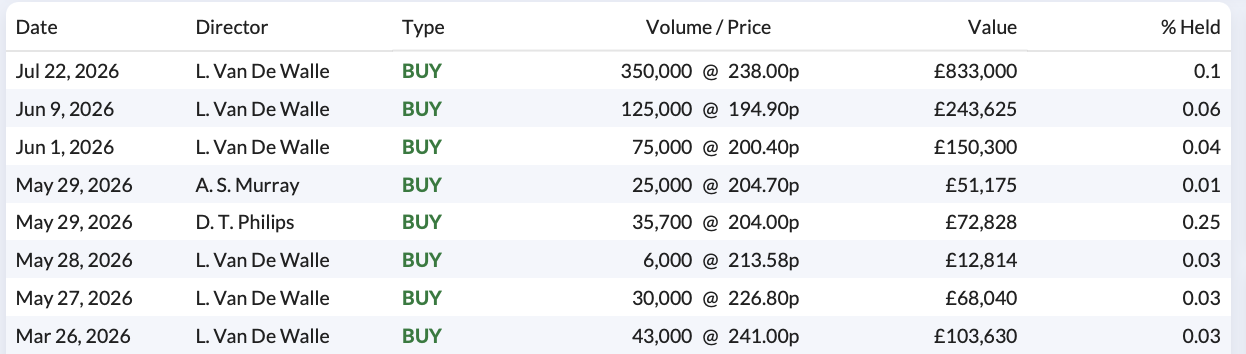
Overall, I think the set-up here looks quite attractive. I’m tempted to go to a GREEN rating but I think I’ll leave it on AMBER/GREEN for now just because net debt/adjusted EBITDA is a little on the high side at 1.8x.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Cavendish (LON:CAV)
I have warned in the past, and had a proper look again this afternoon.
Unfortunately, this is a RED as it can get.
If the cash gets lower then it is game over.
All the best
It is very disappointing. G
Has to do with the FCA rules. Another FY with lower revenues and they have a serious problem.
Not sure if this was picked up and mentioned in your analysis this morning.
All the best
PayPoint (LON:PAY) having an excellent run. Now moved up through 700 with little chart resistance until 800. Thank you for drawing this stock to my attention Graham. I owe you a beer or three when next we meet.
Most welcome, Lord Gnome!
I have been casting an eye over the BP (LON:BP.) trading statement this morning. It states that 'Net debt at the end of the third quarter is expected to be in the range of $13.5 to 14.5 billion (2Q 2026: $22.3 billion).' The FT also reports that Net Debt was $22bn at the end of June. However the BP stock report shows Net Debt at $35.4bn at the half year point (i.e. June 26).
Can anyone explain the discrepancy to me, it's probably in the definition of Net Debt but I can't see what it is.
Fair write up on Cavendish (LON:CAV) Graham, I don't think it can stay Green when they are so many unknowns.
Revenue is -27% year on year for H1, like you say the might make it up in H2 but there is considerable risk that they won't. They certainly haven't claimed that they think they will hit the £60 million.
For a broker (!) Cavendish (LON:CAV) 's update today is too opaque. They should have spelled out the decline in H1 revenues, and made some mention of margins. 2/10
I sold this morning and ate the loss. Was hoping that their operational leverage might come through but they are clearly finding the market tough / revenue difficult to come buy.
The fact that they still operate with 2 CEO's is odd to me. I wonder if an appointment from the outside needs to be introduced at the top level instead of this.
I sold half my Cavendish (LON:CAV) holding a Month or so ago thankfully, seems a good price now so I think I'll hold onto the what I have left.
Then again I have been saying the last 18 Months it looks a good price, yet it keeps going down.
I agree, very disappointing H1 results.... and not enough information and colour in the Trading Update for investors....!
The only silver lining I can see is that IPO activity has picked up quite markedly in Sep and Oct so far. My rough count is like up to 10 IPOs already in the bag between Sep-Oct... and we still have another few weeks of new IPOs to be announced before the season closes in Dec.
However, I think Cavendish (LON:CAV) did none of the IPOs.... hence their profit warning today... bad luck, or are they struggling in a competitive market? They make enthusiastic sounds about their IPO pipeline, but its all too vague...
My research shows, however, that they are continuing to grow the number of companies that they are appointed broker for, so at least that metric is healthy and forms a nice recurring income, as well as optionality for extra income for transactions, etc.
(I hold in the Boon Fund)
Marston's (LON:MARS)
Underlying profit at year end to be above top end of expectations - i wasnt really expecting that - all done with full year lfl sales down 1.2% - with great world cup , good summer weather and refurbed sites benefitting from 30% uplift in sales negative topline seems tepid. Its hard to make much sense of that really - obviously they have done well on costs which is key and the old saying sal;es is for sanity well thats probbaly true - clearly though with such high bounce in sales "when they splash the cash" that suggests sales must fall of quickly when sites start to get tatty again - i wont argue with 30% ROIC returns but i am left wandering if they wait too long and underinvest in sites before they get refurb - we all perhaps know that when pubs go below minimum standards - the punters soon walk for the door - ideally all pubs should kinda not be on the floor ref sales levels ever.
Ref net debt excluding leases its coming down - at the itermim stage they they hoped to be down to 4X at year end and they are only at 4.2X - perhaps they have accelerated refurb plans. But lowering debt quickly imho is the key to teh value outing at current prices.
Mention of buybacks soon - personally i would rather they carried on paying down debt for at least another 18 months - sharebuybacks could pay good rewards though at anything around current levels - as long as they keep making current years level of profits into future that tactic might really help recovery - lets be frank at current market cap share buybacks do have a bit of a no brainer feel.
Note the market was expecdting decent uptick in earnings for the new year starting too - lets hope that there is no hidden stuff ref brokers and teh new year.
all they really need to do is deliver clean net profits of £60 millplus and pay debt down with that. I would say with topline lfl numbers still in negative territory despite the "investment for growth" - not sure if they are simply in a purple patch of tailwinds - will it carry on as planned ref decent bottom line delivery? i know not but they seem fairly chipper. Take £150 million off the debt and feed interest savings to profits and this company would look alot more attractive at current prices-than it does now so i hope they are not going to gung ho ref investing - they have been very guilty of that in the past.
Stockranks are currently well out of the green but with debt coming down that may imrpove - note the debt shown per stocky included leases so its kinda not reflective of actual debt if you are happy to "sensibly" ignore future rents that will be covered by future sales and not treat that as real debt.
It would be great to hear some thoughts on Whitbread (LON:WTB) - they have an activist trying to shake the business up and unlock capital for shareholders (Corvex Management)
Whitbread (LON:WTB) must admit i have got bored and jumped ship here - not sure how much better their new about direction cunning plans will work than then old ones. If it aint working you gotta do something different though - my slightly worry is that all this change of use wont exactly come cheap. They are making hard work of a pretty decent brand that should benefit from having high outright ownership and debt that isnt too high. I suspect they may be near the bottom here ref bad news and i see they are on target today - so perhaps green shoots for shareholders. As you say Corvex on the sidelines should perhaps concentrate the minds of management.
Yes - the planned changes will indeed cost. I have stayed at Dumbarton where there was a restaurant next-door - but now closed and last time I passed by still closed and empty. In fact I no longer stay there - better elsewhere. If this is repeated over many sites the cost will indeed be high, so I welcome an activist with over 6% stake taking a seat on the Board.
My understanding is that many of their properties are undervalued in their financials which should provide some cushioning. Equally Germany appears to be developing well. An interesting mixture for a hospitality business with a clear strategy. On a day to day level I use Premier because they are consistent in their offering and I appreciate knowing what I am going to get when I am away. In particular cleanliness. I am no longer a holder but used to get involved on a trading basis for a while as they had a clearly defined range. I can't quite see how they improve their performance in the Uk so the story is all Germany for growth and as such I would want to see how the politics works its way through.
Zeus Capital’s note today lifts microcap Goldplat (LON:GDP) ) fair value by 40% — unremarkable on its own, except for the backdrop. Gold has fallen roughly 7% this month, and other gold-mining equities have amplified that slide. Goldplat’s shares rose anyway.
The other oddity: this is Zeus’s first note since May. They’ve been asleep for 5 months, but now raise a target the stock had already outrun, ahead of next month’s trading update. I hold.
Plus500 (LON:PLUS) opened 66 p up so a slightly better reception than IG's Underdog acquisition - lets hope it holds
Impax Asset Management (LON:IPX) update: management lamely trying to spin a recovery narrative yet the business is still under severe pressure from outflows.
Clients pulled a staggering £7.78bn out of the firm over the year. Even though market performance added £1.77bn to AUM over the 12-month period, the sheer volume of redemptions overwhelmed those gains.
I thought this might have turned a corner but last quarter saw further massive outflows (almost 10% of market cap in single quarter!). Although PE of around 10 and half market cap is in cash so possibly all the bad news priced in.
Impax Asset Management (LON:IPX) Surely another example of Stocko ranks way behind the times. Its been in so called recovery mode for the best part of 5 years during which time it has fallen deeper and deeper yet is shown as overall 78 - Q97 R93 and yes, M12
My worry here is that AUM falls below a certain level whereby the company becomes stuck in a downward spiral as clients and staff jump ship. Not sure they've reached that stage yet, but the risk has certainly increased after another massive outflow. Flows need to stabilise within the next few quarters. I'll watch from the sidelines for now but could be a good recovery candidate at some point.
Interesting tit for tat acquisitions by IG group (LON:IGG) last month and as from today Plus500 (LON:PLUS) - I am sure Graham will be interested in how the Plus 500 acquisition goes to day compared to IG's . The US is becoming quite a battleground and I happen to hold both of them. The corporate lawyers must be rubbing their hands !!!!
I think the pick of the sector now is CMC, who appear to be growing without risky bolt-ons by becoming a tech provider to third parties.
I like the look of Greencore (LON:GNC) . Brokers have upgraded FY26 EPS by 10%to 20.8p, the Bakkavor acquisition looks a good move now. FY26 TU out this morning.
Greencore (LON:GNC) I'm not sure I understand the SR of 42, on a PE of 11.2 and a PEG of 0.6. I don't think it will be 42 for long !