Daily Stock Market Report (Tue 21st July 2026) - YU., MARS, KIE, MONY, STEM, MTO, MHA

Yesterday saw the appointment of John Healey as the UK's new Chancellor.
Healey was Defence Secretary from 2024 to 2026, where he wanted to increase defence spending to 2.5% of GDP. He ended up resigning from this post in June of this year, arguing that Rachel Reeves and Sir Keir Starmer had not committed enough to defence spending in the wake of the US-Iran war and the situation in Ukraine.
I don’t know much about Healey’s priorities other than this episode. He has been an MP for nearly 30 years, with plenty of time served as a backbencher.
Meanwhile, Burnham’s first act as PM yesterday was to cut VAT on electricity bills from October, with the rate falling from 5% to 0%, part of the “breathing space” agenda.
Overnight market movements:
- The FTSE is down 0.6% at 10,480
- S&P 500 is up 0.5% at 7,480
- Brent crude (October) is down 0.8% at $86.50/bbl
- Gold is up 1.4% at $4,060/oz
- Bitcoin is up 0.7% at $65,800
Roland Head joins me today.
Finished for today, thank you.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Prologis (NYQ:PLD) (£106bn | SR52) (re. SEGRO (LON:SGRO) (£12bn | SR74)) | Prologis say they met with Segro on Sunday. “We were disappointed that the discussion did not provide meaningful clarity regarding the matters that would enable further progress… We remain ready to engage constructively at any time in the interests of all shareholders.” | TAKEOVER | |
Compass (LON:CPG) (£40bn | SR71) | “Another strong quarter”. Organic revenue growth 7.1%. Like-for-like growth in line with expectations. Reiterating 2026 guidance: “confidence in delivering underlying operating profit growth of above 11% in constant currency”. | ||
Smiths (LON:SMIN) (£7.6bn | SR62) | Smiths Industries Pension Scheme completes a £760 million buy-in transaction with M&G. Follows the successful buyout of SMIN’s other defined benefit pension scheme in May. | ||
Frasers (LON:FRAS) (£3.4bn | SR82) | Frasers has acquired a further 2.55m HUGO BOSS shares. Now holds 20.9m shares, c. 30.28% of the share capital of HUGO BOSS. Has therefore exceeded the mandatory bid thresholder of 30% in the German takeover code. | ||
ROSEBANK INDUSTRIES (LON:ROSE) (£3.0bn | SR22) | MW Components performed strongly in H1. Confident it will exceed current market expectations for 2026. CPM is on track to meet market expectations for 2026.Overall outlook: adjusted operating profit and EPS to be ahead of consensus for 2026. Confident the Group will continue to outperform into 2027. | ||
MITIE (LON:MTO) (£1.97bm | SR54) | Q1 FY27 Trading Update & Intention to suspend Share Buyback Programme & Recommended cash acquisition | Revenue +10%. 4% organic growth. Closing net debt £477m. Suspending share buyback due to takeover offer: up to 221.6 pence in cash for each Mitie Share. Includes 3.1p dividend for FY26. 44.7% premium to yesterday’s close. | TAKEOVER (Graham) [no section below] This isn't the type of company I'd have thought to be a priority for a US takeover but here we are: a generous offer from OCS, which is owned by the American private equity gian Clayton, Dubilier & Rice. A near-45% premium should, in my opinion, be enough to get this over the line. For now, there is only a commitment to support the takeover from Oasis Management Co., who have options over MTO shares equivalent to a 9.9% ownership interest. The offer equates to an earnings multiple of 15.5x this year's forecast earnings. In the facilities management sector, I'd consider that to be a reasonable offer and it's certainly a much higher level than where the stock market was willing to value it. Well done to anyone holding this. |
MONY (LON:MONY) (£1.05bn | SR96) | Like-for-like revenue growth 6%. Reported growth 1%. Profit after tax +1% (£46.1m). “Confident to deliver Adjusted EBITDA for 2026 within our current published consensus.” | GREEN = (Roland) A closer look at MONY’s divisional results suggests to me that its core businesses are performing well. It’s unfortunate that the (acquired) cashback business appears to be acting as a drag, with H1 revenue down 13% following a similar decline in 2025. Despite this, profitability remains excellent and I think the company’s efforts to become more of a full-service financial platform are logical, albeit they bring tough new competition. Although the outlook commentary seems to suggest that profits could be towards the lower end of consensus, I am not too concerned given the stock’s low rating. Ultimately, I still think there’s plenty of value on offer here, so I’m leaving our positive view unchanged today. | |
Kier (LON:KIE) (£974m | SR73) | “The strong trading momentum reflected in [H1] continued through the second half of the year, and we now expect revenue and profit for FY26 to be at the top end of market expectations.” | AMBER/GREEN = (Roland) [no section below] Today’s update suggests a mild upgrade to full-year expectations, backed by £1.5bn of new infrastructure business in H2 and £1bn of new construction work. Both categories were weighted towards major public sector infrastructure projects, including Sizewell C, South West Water, prisons and hospitals. One positive point is that Kier expects to report average month-end net cash of c.£11m for FY26, improving on the monthly net debt figure of £49m reported last year. Average daily net cash is the gold standard in this sector, but a monthly net cash result is still respectable. The shares have risen by c.20% since our last view in Sept 25, but Kier’s StockRank has fallen steadily over that period. On balance, I think it’s fair to leave my previous moderately-positive view unchanged today. | |
Galliford Try Holdings (LON:GFRD) (£593m | SR86) | Appointed to the new Crescent Purchasing Consortium Construction and Capital Works framework. Covers construction projects across education and the wider public sector for a maximum of eight years. | ||
GB (LON:GBG) (£519m | SR54) | Financial performance in the first quarter was in line with the Board's expectations. | ||
Iqe (LON:IQE) (£481m | SR25) | Trading in H1 2026 exceeded management expectations with strong demand across all of the Group's core segments, which is expected to result in first half revenue of at least £64m. IQE now expects FY 2026 revenue growth in excess of 30% year-on-year, resulting in low-teens £m adjusted EBITDA. | ||
Wickes (LON:WIX) (£434m | SR67) | H1 like-for-like revenue growth 0.6% (Retail minus 0.4%, Design & Installation Rangers plus 3.6%). Retail returned to growth in Q2 after a negative Q1. “We remain comfortable with consensus expectations for adjusted PBT for 2026.” | ||
MHA (LON:MHA) (£402m | SR81) | Organic revenue growth 6.4%. Total revenue up 12%. Adjusted PBT +11% (£39.2m). Positive start to FY27. Board “remains confident in the Group's prospects for FY27 and in delivering its medium-term ambition of annual revenues in excess of £500 million.” | AMBER = (Graham) [no section below] I had the chance to talk one-on-one to management here recently, which I really appreciated. It was very helpful for me to understand how the company has transitioned from a private partnership into a publicly-listed model, while continuing to attract and incentivise younger staff. This is a fairly recent IPO (April 2025) that hasn't put a foot wrong yet, and today's full-year results are encouraging. There's a nice mix of organic and acquired growth, a healthy net cash position, an ambition to double revenues over the medium-term, and a positive outlook statement. The main service offered (audit & assurance) generates 50% of revenues but generally speaking this is a well-diversified business: a range of service lines are offered across a wide variety of economic sectors, and there is even some geographic diversification with acquisitions made in South-East Europe and the Middle East. At the same time, it should be more nimble than a Big 4-type firm. As such, I continue to have zero criticisms of MHA. The reasons for my neutral stance are a) valuation, as 12x earnings strikes me as very fair in the professional services sector; and to a lesser extent b) it it has been publicly-listed for barely more than a year, which increases my caution. But I am very much open to upgrading my stance on this one at some point. The StockRanks love it, giving it a score of 81 and categorising it as a Super Stock. | |
Fuller Smith & Turner (LON:FSTA) (£393m | SR91) | LfL sales growth 5.1%, good year-on-year profit conversion for the first 16 weeks of the financial year. | ||
Marstons (LON:MARS) (£351m | SR66) | Like-for-like sales growth 22% on matchdays. Year-to-date LfL sales are 1.6% lower. The Board has confidence in delivering full-year market expectations. | AMBER = (Roland) [no section below] I cut our view to neutral in January, commenting that sales performance seemed to have been weaker than rivals over the festive period. Today’s update shows strong LFL sales growth on matchdays, this is hardly surprising. I think the more important number is that overall LFL sales are -1.6% year-to-date. Any growth in profits in this context is presumably being driven by cost cutting and lower interest payments as debt falls. However, leverage isn’t expected to fall below 4x EBITDA until next year. Some progress is being made here – refurbished formats are performing more strongly – but I don’t see much reason for excitement and share the StockRanks’ conclusion that a neutral view is appropriate. | |
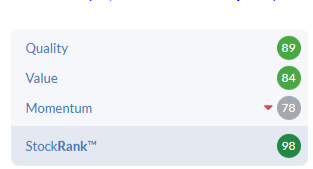
Yu (LON:YU.). (£284m | SR98) | H1 revenue +19% to £405m with 43% growth in meter points to 153k and 45% increase in contract book to £1.7bn. FY26 outlook: “on target to deliver EBITDA, EPS and operational meter metrics” in line with current expectations. | GREEN ↑ (Roland) Despite some macro pressures, this founder-led business is continuing to deliver profitable growth and market share gains. Our algorithms are positive on Yu, with Super Stock styling and a StockRank of 98 and this reflects my own positive view of the business. With a single-digit P/E and double-digit EPS growth forecast for the next 12 months, I’ve decided to move my view up one notch to be fully positive today. | |
SThree (LON:STEM) (£263m | SR95) | Revenue -8%, with pre-tax profit -73% to £2.7m. EPS -63% to 2.1p, interim dividend held at 5.1p per share. Net cash -10% to £43.0m. Outlook: “cautiously optimistic”, with improving new business activity in a number of countries and a return to growth in the contractor order book. H2 weighting expected, supporting FY26 PBT guidance of c.£10m. | AMBER = (Graham) We’ve been neutral on this and I’m inclined to stay neutral on it today, although I am leaning towards a possible downgrade.I do think that the balance sheet is a form of strength, but I’m less confident in the earnings outlook, as hitting forecasts requires a big H2 weighting in the current financial year, and then a near-trebling of profitability next year. | |
Helical (LON:HLCL) (£231m | SR42) | Redemption of B shares will occur today. Cash proceeds from the redemption are expected to be sent to shareholders on Tuesday 4 August 2026 (see yesterday for more detail). | ||
Netcall (LON:NET) (£194m | SR50) | FY26 results are expected to be in line with expectations, with revenue +20% to £57.7m and adj EBITDA +23% to £12.1m. FY27: sales pipeline is at “a record level”, supported by demand for cloud-based and AI-enabled solutions. | ||
Midwich (LON:MIDW) (£135m | SR64) | H1 revenue +3% to c.£640m, with H1 adj profit expected “to be around 10% higher than H1 2025”. Growth in other areas is offsetting the impact of the Middle East conflict. Net debt +£12m to £148m (2.3x EBITDA). Outlook: now expects FY26 results to be “broadly in line” with 2025. | BLACK? (RH note: current consensus is for FY26 adj EPS to be 24.3p vs 22.4p in FY25, so this looks like a downgrade to me, but I don’t have access to any broker forecasts). | |
Arbuthnot Banking (LON:ARBB) (£135m | SR58) | Pre-tax profit +1% to £11.0m, with NAVps of 1,712p (Dec 25: 1,694p) and a CET1 ratio of 12.0% (Dec 25: 13.3%). EPS +17% to 49.9p with interim dividend +9% to 24p. Continued growth in client balances and lending, with net inflows to asset management. | ||
Somero Enterprises (LON:SOM) (£109m | SR86) | The company has engaged with a broad base of shareholders and reviewed feedback received on topics including capital allocation and remuneration. The company continues to assess “the appropriate balance between maintaining financial flexibility, investing in the business and returning capital to shareholders.”. | ||
Berkeley Energia (LON:BKY) (£109m | SR20) | The maiden Mineral Resource Estimate (MRE) for Berkeley’s 100% owned Conchas Project in Spain has been completed, with totals of ~49,000t of contained Li2O & ~25,200t of contained Rb2O. | ||
Sintana Energy (LON:SEI) (£107m | SR17) | Uruguay: Exploration of the AREA OFF-1 block has been suspended for a year (until Aug 27) at the request of operator Chevron. Argentina: a recent exploration permit expression of interest by SEI will now be put to an international public tender before a decision is made on the permit award. | ||
Gateley (Holdings) (LON:GTLY) (£74m | SR49) | Revenue +8.2%, adj pre-tax profit -7.1% to £21.6m. Adj EPS -10.1% to 11.5p, dividend cut by 44.2% to 5.3p per share. Outlook: early trading in FY27 is in line with expectations, with good activity levels. Targeting margin improvement through fee discipline and cost control. | ||
Victoria (LON:VCP)(£73m | SR50) | More than 75% of the holders representing Victoria’s €166.6m 3.75% senior secured notes (due March 2028) have agreed to the proposed refinancing, allowing it to be implemented. | ||
Billington Holdings (LON:BILN) (£58m | SR88) | Three significant recent contract wins with an expected combined value of c.£28m. These contracts are split across three sectors: Education (c.£6m), Energy from Waste (c.£12m) and Defence (c.£10m). All of them are expected to be delivered in 2027. Outlook: these projects “provide further confidence for delivering 2027 in line with market expectations”. | ||
Rentguarantor Holdings (LON:RGG) (£50m | SR31) | H1 revenue +250% to £3.4m, with adj net profit of £250k (HY25: loss of £367k). There was a 110% increase in applications during the half year, with a 179% increase in the number of contracts. Certain debt has been repaid and there was a £1m equity raise in June, improving the group’s cash position to c.£2.4m. Outlook: now expects FY26 revenue and adj PBT to be “materially” ahead of expectations. | ||
Edx Medical (LON:EDX) (£40m | SR3) | The BC95 testing service involves three component tests. 1.) A highly sensitive biomarker test for the very early detection of bowel cancer. 2.) A comprehensive report on a panel of hereditary genetic risks. 3.) A reference test for faecal haemoglobin which aligns with current NHS practice. |
Graham's Section
SThree (LON:STEM)
Unch. at 215p (£263m) - FY26 Half Year Results - Graham - AMBER =
The decline continues here, with a sharp drop-off in profitability:
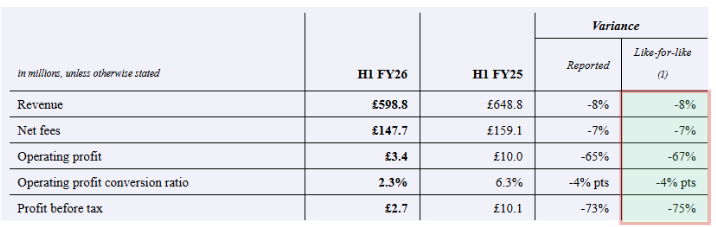
We did get a preview of these results in June, when I was neutral on this stock.
At those results, the company said it was on track for FY26 PBT of c. £10m. It says that again today, in the outlook:
As previously announced, the cost optimisation programme remains on track, with benefits weighted to the second half, underpinning FY26 PBT guidance of c.£10 million.
Note that there’s a heavy H2 weighting. PBT of only £2.7m in H1 leaves it all to do in H2, although the company will argue that it’s already laid the groundwork for a stronger second half.
The observations I made at the H1 trading update are worth emphasising again:
Contract fees underperforming permanent fees: I find this interesting, as contract fees ought to be more stable than permanent fees. But that’s not happening at the moment. Contract fees are down 8% year-on-year, while permanent fees are down 5%. (Remember that SThree is heavily weighted towards Contract, which represents 85% of fees).
Geographical spread: the biggest variance is actually geographical, rather than contract vs. permanent.
Spot the difference between continental Europe (DACH/Netherlands) and USA:
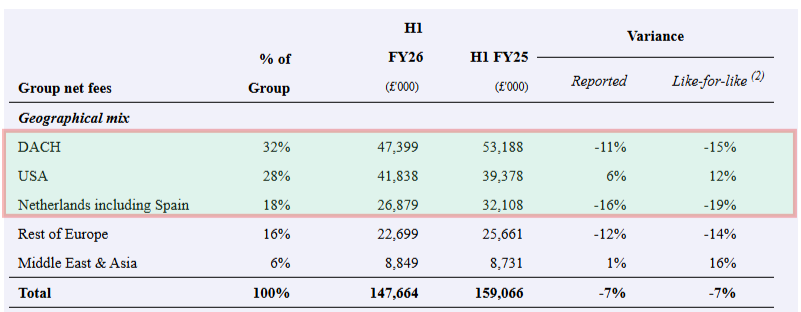
For me, this table is a good argument against the idea that recruitment is structurally broken. What it says instead is that recruitment can still thrive in very strong economic conditions.
But perhaps the sector is far more reliant on strong economic conditions than we previously realised?
Here is an excerpt from the company’s review of DACH (Germany, Austria, Switzerland)::
Germany saw Contract decline 12% YoY, with overall net fees down 14%, reflecting lower levels of demand for Technology skills (down 18%), its largest vertical, particularly in software development, amid an ongoing shift in demand towards ERP cloud migration and roles across the AI value chain. Performance continues to reflect a challenging trading environment, with the expected uplift in job flows from the reform of the debt brake and the government's €500 billion investment fund yet to emerge.
In other words, what’s being blamed is a combination of weak Technology demand and a lack of fiscal support from the German government.
Switzerland and Austria were also very weak: in Switzerland, Engineering fees collapsed by 55%, so that total Swiss fees fell 24%, “with broader market softness reflecting continued cautious client sentiment”.
In the US, by contrast, there was:
…robust demand for Engineering and Technology skills linked to power generation and the AI value chain. This reflects sector-wide investment to meet rising electricity demand from AI applications, data centres and electric mobility, alongside ongoing grid modernisation to address climate-related challenges.
AI is clearly having a big impact, with Technology roles in strong demand in the US, while Europe goes in the other direction.
CEO comment (with emphasis added by me):
"Trading momentum improved through the first half despite continued macroeconomic and geopolitical uncertainty, with strong performances in the USA and Japan, stable year-on-year new business activity and a return to growth in our contractor order book. While market conditions remain mixed across our geographies, we are encouraged by the improving trends we are seeing in a growing number of countries and by the continued resilience of our Contract business.
We anticipated early on how our industry was set to evolve and, over recent years, implemented clear strategic initiatives. The benefits of these decisions are increasingly visible. We have simplified the business, focused on markets where we have the right balance of scale and opportunity, and successfully completed the rollout of our Technology Improvement Programme. Operating on a single global cloud-based platform has enabled us to build an operating model centred on shared services and economies of scale, which is delivering productivity gains, improved execution, and the data and process backbone to deploy AI and new capabilities at scale and pace. We are now a focused, scalable, less complex and tech-enabled business with a clear operating model…
I’ve spoken to management here before and they are very proud of the Technology Improvement Programme, arguing that it sets them up for the future in a manner that isn’t matched by other recruiters.
Net cash ended H1 at £43m (a year ago: £48m) and the interim dividend is unchanged at 5.1p. Note that this dividend is not backed by earnings per share.
Graham’s view
We’ve been neutral on this and I’m inclined to stay neutral on it today, although I am leaning towards a possible downgrade.
Consensus forecasts say that FY November 2027 will be much more profitable than the current year:
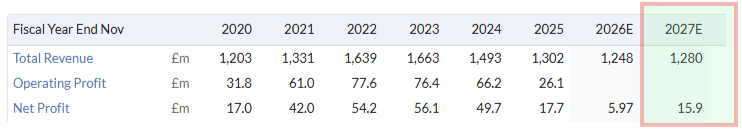
These forecasts result in a forward P/E multiple that isn’t too extreme (21x):
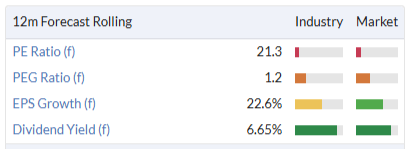
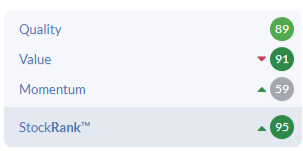
Combine that with a high dividend yield and asset backing, and you get a high ValueRank. It even qualifies as a Super Stock:
Today’s balance sheet shows equity of £211m, or £194m after deducting intangibles. Most of the company’s assets are in the form of receivables, which is a good thing (much more liquid than PPE).
So I do think that the balance sheet is a form of strength, while acknowledging that the cash balance is likely to be volatile.
I’m less confident in the earnings outlook, as hitting forecasts requires a big H2 weighting in the current financial year, and then a near-trebling of profitability next year.
That’s all possible but for me it heightens the risk of a profit warning.
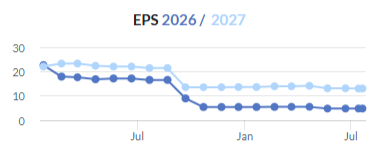
EPS forecasts have been stable for a while, after having been downgraded previously:
For now, I think a neutral stance remains the right call for us.
Roland's Section
Yu (LON:YU.).
Up 2.7% at 1,685p (£292m) - Trading Update and notice of results - Roland - GREEN ↑
Yü Group PLC (AIM; YU.), the independent supplier of gas and electricity, and meter asset owner and installer of smart meters, to the UK corporate sector, is pleased to confirm trading is in line with expectations and provides an update on trading for the six months ended 30 June 2026.
I last covered this business utility supplier in March, when I reviewed Yu’s full-year results.
At the time I took a broadly positive view, notwithstanding a couple of niggles. Today’s half-year update suggests to me the group is continuing to deliver real growth and market share gains:
H1 revenue +19% to c.£405m, in line with management expectations. “The group continues to gain market share despite a warmer than expected winter period reducing consumption”.
Meter point growth: the number of meter points managed by the company has risen by 43% to 153k over the last year, supporting the company’s target for 7-9% market share in 2028.
Contract book +45% to £1.7bn, ahead of management expectations: this represents customer contracts for future energy supply.
Smart meter installs up 27% to 12k, with meters owned up to c.55k. These are expected to generate an annualised, index-linked annuity income of £3.0m (H1 25: £1.8m).
Yu’s hedging facility with Shell (disc: I hold SHEL) has been extended to 2032. This trading agreement allows the company to buy electricity and gas at fixed prices (to support customer contracts) without requiring Yu to post collateral to offset commodity price movements. It’s a useful asset to the business as it effectively reduces the capital needed to support growth. The current facility has the capacity to support annual revenue of >£2bn, providing a clear growth runway.
Outlook
The combination of a mild winter and the Iran war are both cited as short-term headwinds – both factors may have put some pressure on consumption.
In addition, I imagine elevated energy prices mean that customers will be reluctant to sign up for new fixed price contracts, preferring to delay in the hope that better prices will be available later in the year.
Despite this, expectations are unchanged today. Updated broker notes from both Panmure Liberum and Cavendish confirm that there is no change to forecasts this morning. This leaves Yu trading on a fairly modest multiple, with a useful 4%+ yield (one of the highest in the UK utility sector):
Roland’s view
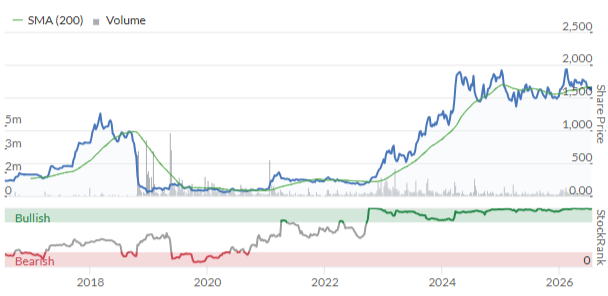
Yu has been an impressive growth story, six-bagging since its 2016 IPO:
Quality metrics are also very strong indeed:
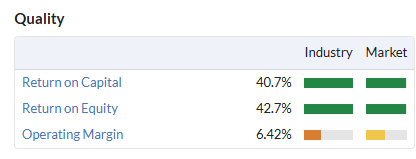
The business remains under the leadership of founder Bobby Kalar, who has a 50% shareholding. I know some investors are wary of small caps with controlling shareholders, but in this case I see it as an attraction. Kalar’s annual dividend income was c.£5.8m last year, by my calculations, representing a multiple of his (generous) total remuneration of £1.2m.
When a CEO’s dividend income exceeds his remuneration, I generally see this as a strong sign of shareholder alignment.
I am positive on this business and share the StockRanks’ view of this business as a Super Stock. However, Yu’s business model is not without risks:
Yu is exposed to the UK economy through demand growth and more specifically bad debt (companies that cannot pay their energy bills). Low margins mean that relatively small increases in bad debt could have a material impact on profits.
Liquidity: despite the benefit provided by the Shell hedging facility, this is a business that requires significant liquidity to support working capital movements and contract wins. My understanding is that Yu also uses invoice factoring to aid cash flow through the year. The company reports a gross cash position of £129m today, but forecasts from Panmure Liberum suggest the year-end net cash position could be c.£50m. In my view, this is a business that needs strong liquidity, so I don’t view net cash as surplus to requirements.
Competition: Yu is generating attractive returns and competing for market share in the UK corporate sector. Larger competitors may try to limit the group’s growth by using their superior scale to offer more competitive pricing (something Telecom Plus recently reported in the consumer sector).
I was AMBER/GREEN on Yu following the group’s full-year results in March. The shares have edged lower since then, but forecasts have held up and continue to show double-digit EPS growth next year:
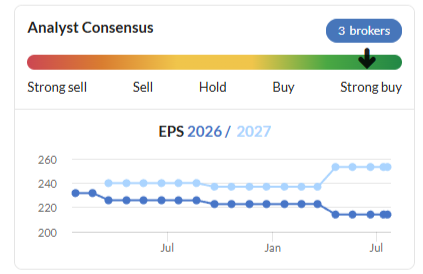
I’m going to move my view up by one notch to GREEN today.
MONY (LON:MONY)
Down 6% at 192p (£1.00bn) - Half-Year Financial Report - Roland - GREEN =
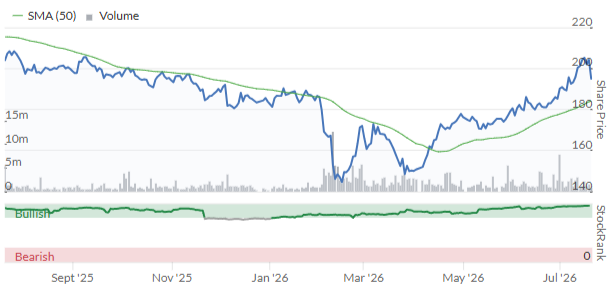
We turned positive on price comparison group MONY in April, when Graham flagged the seemingly excellent value on offer. The shares have enjoyed a good run since then, but have pulled back slightly following the publication of today’s half-year results:
HY26 results summary
Today’s headline figures do indeed seem a little underwhelming:
Revenue up 1% to £227.1m (+6% LFL)
Pre-tax profit up 1% to £46.1m
Adjusted earnings per share up 5% to 9.7p (aided by the impact of buybacks)
Interim dividend up 1% to 3.36p
Net debt up 73% to £31.8m
However, drilling into the group’s segmental results suggests to me that the underlying performance of most of the group was much stronger than these headline figures suggest:
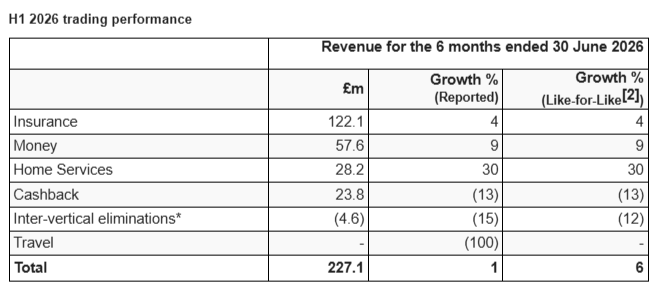
We can see that all of the group’s core businesses all delivered fairly respectable levels of growth in H1:
Insurance: headwinds eased in car insurance, with average premiums down 5% year-on-year, improving from a decline of 9% in H2 2025. MONY says a new AI-enabled Price Optimiser tool is helping motorists save an additional £25 on average.
Money: current accounts and loans are highlighted as areas where performance improved.
Home Services: strong growth, flagging up the continued recovery in the Energy Switching market.
Travel: MONY has moved to having a minority shareholding in its Travel business so no longer reports revenue in this segment. For comparison, Travel generated £6.2m of revenue in H1 25. Stripping this out implies underlying H1 26 revenue growth of c.4%.
Cashback: this was the main area of weakness. MONY’s cashback business was built around the acquisition of Quidco in 2021. Cashback revenue fell by 13% last year, when I estimated that Quidco was only likely to be generating single-digit returns on capital employed.
I’m not convinced this deal has generated much value for shareholders. Fortunately, the current CEO seems to be focused on driving organic growth, rather than making expensive purchases.
Growth initiatives: press reports over the last few days have flagged up the launch of MoneySuperMarket’s investment platform. This has initially been launched as a fund supermarket “enabling customers to invest from as little as £1”.
Other new products in the pipeline include:
SuperSaveClub Insurance - “our own digital broker enabling monthly payments for members at no additional cost”.
MoneySuperMarket Business Banking - “our first dedicated SME proposition, waitlist now open ahead of launch next month”.
MONY’s aim is to transform its MoneySuperMarket app into a super app that will become a “financial companion, going way beyond comparison”.
I can see the logic in this. Although investment, insurance and business banking are competitive markets, it’s possible that MONY will be able to leverage its brand and loyal customer base (SuperSaveClub has 2.5m members) to expand its reach.
Profitability & Balance Sheet: strong quality metrics and strong cash generation have historically been hallmarks of this business:
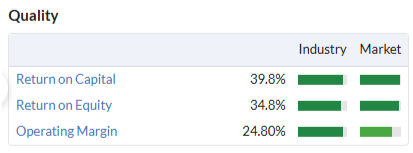
Today’s results show profitability remains intact, with an H1 operating margin of 27% and trailing 12-month return on capital employed of 40%.
The only area that did suffer in H1 was cash flow, with operating cash flow down by 17% to £36.2m. The highlights several reasons for this:
Expansion into channels with longer cash collection cycles (e.g. Energy)
Stronger revenue growth in June (cash won’t be collected until H2)
Reduction in amounts owed to Quidco members
Cash conversion is expected to improve in the second half of the year and I don’t think there’s a serious concern here. But I’ll be interested to see if the evolving mix of revenue does have an impact on full-year free cash flow conversion.
Outlook
My feeling is that there’s some wiggle room in today’s statement from Peter Duffy:
Our recent trading performance and the breadth of our portfolio combined with disciplined cost management, gives the Board confidence that we will deliver Adjusted EBITDA for 2026 within our current published consensus. We remain well positioned to deliver sustainable, profitable growth.
Consensus forecasts are included in today’s results and are available on MONY’s website.
Current consensus for FY26 adj EBITDA is £140m to £148m, with a mean of £145m. My reading of today’s outlook guidance is that EBITDA is expected to be within the range of expectations, but could be towards the lower end.
I would guess that this lies behind today’s share price drop.
Unfortunately we don’t have access to broker forecasts for MONY, so can’t see more detail until updated consensus estimates filter through to the StockReport.
Roland’s view
Notwithstanding the risk of a slight downgrade to consensus, I continue to think MONY shares probably offer good value. At around 195p, the stock is trading on a forward P/E of 10, with a 6.4% dividend yield:
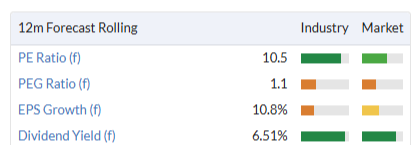
If past years are a guide, these earnings will convert fully into free cash flow, providing strong support for the dividend and perhaps further buybacks.
Looked at a different way, MONY’s trailing 12-month profits currently offer an EBIT/EV yield of c.11%. For a business with minimal leverage, high margins and strong cash generation, this seems too cheap to me unless the business is about to go into decline. I continue to see this business as a potential takeover target, as Graham highlighted in April.
While AI may present some risks, on balance I think the combination of product complexity and commercial and regulatory barriers to entry in the financial sector are likely to protect MONY’s platform, as long as it continues to evolve.
The company’s continuing move towards becoming a financial platform could help create a moat, if it gains traction.
Although MONY shares aren’t quite as cheap as they were a few months ago, I’m comfortable leaving our GREEN view unchanged following today’s results.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
any thoughts on Headlam PLC - does it have any life left? The stock price has been collapsing over the last few days even though I think it still has 'positive' property. I remember the analysts here on stockopedia - this used to be referred to as a 'solid' boring company that is 'steady as it goes' just a few years ago. They used to buy back shares as well! Now reduced to a sub 5 million market cap jeez - I bought a few but just a punt.
I would suggest you stay well clear of this share - I think it’s days are numbered
You love to get into trouble Ben-:)
Shoe Zone (LON:SHOE) and IG Design (LON:IGR) will make you money before year end instead of taking it from you!
All the best
I don't like that the activist investor First Seagull seems to be selling - rns just hit.
The plot thickens at System1 (LON:SYS1) ....
Lord Ashcroft, previously of only a 1% stake, just bought another £2m shares at 328p (above the offer price of Brave Bison (LON:BBSN)) to now own 6.5%.
Lord Ashcroft is near 30% shareholder in Jaywing (which was listed till last year) - an Australian marketing agency.
The plot thickens...
(I hold in the Boon Fund)
Doesn't he also own 23% of Brave Bison (LON:BBSN) ?
He does indeed! Completely forgot about that!
That does get more intriguing that he thinks the current SP of System1 (LON:SYS1) is undervalued, to buy now.... it would make sense if he was backing BBSN management to make a higher bid.
If Ashcroft owns 23% of Brave Bison (LON:BBSN) and now 6% of System1 (LON:SYS1) isn't he a related party? Is it a blocking move or an enabling one? What are your thoughts Boon Fund?
Rentguarantor Holdings (LON:RGG) expects revenue and profits to be materially above market expectations. It looks like they'll be thrashed to me!
Has anyone previously researched what the potential addressable market is? The growth here is strong but I am wondering what the potential limit on revenues and profits is.
Rentguarantor Holdings (LON:RGG)
cheers Tortoise investor - had a quick look and their product almost looks too good to be true froma landlords perspesctive (how its not shareholders having to pick up the pieces if stuff goes wrong) - not sure how they work their ninja magic - or if i am missing hidden catches in that it might not be as good as a quick glance gives ten impression it is.
All i can guess is that very high % of tenants are trustworthy and for them any bad credit would be fate worse than death - so if you can whittle the bad uns out presumably that limits the damage. does the company go after tenants for recompense if they fail to pay rent on time ?
I would guess the addressable market is huge and perhaps there are other areas where move into that may be complimentary. eg deposist ref building works being done
One would think that chances of repeat business should be great - if tenant ensure they dont screw landlord very little reason not to do same again next time they need a guarantor.
At face value on an initial look it looks great.
Obviously with the changes in then law they are in an uber uber sweetspot ref timing - so i wouldnt be minded to get carried away with the amazing growth rate.
Tempted to pick up a few on a whim here.
I was tempted too, but the stock still trades on a p/e around x40. Personally, I know 3 people in my area that have had to move because landlords (the smallest one held 8 properties) have all decided to sell up because of the new legislation, which is the opportunity for RGG. My concern is the pool is getting smaller even though there is a great deal of opportunity for growth. My other concern is the moat for the business. It strikes me as though this is something potential entrants could quite easily replicate, hence, my decision for remaining on the sideline.
Thanks for the note Tortoise.
I hold as my biggest holding Property Franchise (LON:TPFG) which at a recent investor update (cant remember which) said that they were launching a rent guarantee scheme. Property Franchise (LON:TPFG) has a large advantage here because of their huge number and range of franchised rental outlets.
That is not to say Rentguarantor Holdings (LON:RGG) may be a future growth stock but there is a lot of competition. I remember when doing clients rental tax returns a few years ago that certain agents and insurance companies were offering this product
Will be interesting to see how much traction Rentguarantor Holdings (LON:RGG) gets and how competitive their rates are
MHA (LON:MHA) earnings beat, cash up to 25m, divi increase and very confident tone for FY27. Typically UK PLC, share price drops
Any knowledge to why the growth is still there but the pull through cashflow has dropped off a cliff in the last two years for MHA (LON:MHA)
MHA (LON:MHA)
ok fantastic cash generation from operation thats da bomb - no issues there.
all that dosh has been pretty much handed over to "the members" - so thats your answer.
hmmmm how long will this company remain listed with that cash profile :)
Presumably there is some logical reasons there - perhaps that lies in the company roots before listing ?
This site is playing up again, can't find some of my folios.
Be great if you got a chance to have a look at MONY (LON:MONY) team, always viewed it as a decent income stock with 6.5% divi which is covered, despite the AI fears its also had a nice run up since earlier in the year back to near 52 week highs. Personally I would be looking for a pull back before adding as I've always been convinced its ex/peak growth already but equally it seems to be holding onto the status quo and could be a cigar butt with quite a few (income) puffs in it yet.
I work in an IT role that puts me at the centre of the AI storm so I feel I have a right to comment on the topic. Here is another example of a company who's death has been exaggerated. Think it would be a useful exercise to identify other companies that fall into this category, RWS springs to mind. Could be a clever way of shorting AI without risking the farm. Apologies for not volunteering, lack the time and expertise. PS have you noticed how predictive text is getting poorer - to drive you towards using AI? 'centre' is now a typo on Stocko!!!!
You're allowed to comment on any topic you want to!
I spent several decades working in software development and am also sceptical about some uses of AI...
e.g. Sage (LON:SGE) I know someone who has recently retired from a small, 3 person company with a £2M turnover that sold electrical components. They used Sage as their system of record for recording quotes, orders, stock in/out, invoices and receipts etc.
They paid about £3k per year for licensing and support. Businesses like that are not going to rip out Sage and replace it with some new, AI built package just to save £3k. The risks and costs are simply not worth it.
As for predictive text, I agree it's getting worse, but imho it's more to do with trying to add more features to the software than driving us towards AI. If anything, it drives me to switching off the enhanced keyboards (like SwiftKey) that typically use predictive text.
MARS Marstons lead with positive figures from the World Cup but then say that sales at other times are suppressed. Now the World Cup is over will this mean they struggle to hit full year figures? Currently they say they will be inline with expectations. How will the market view this report? YNGA Youngs & Co appear to be the stronger bet in this sector.
I was expecting MARS to beat expectations given their profile of pub and I agree this could lead to a challenging next few months. History tells us we normally get a slow down in beer sales post a large sporting event as people are spent out. I agree YNGA is a much better proposition.
Agree with Young & Cos Brewery (LON:YNGA) got to ask yourself why has it moved to the main market from aim when times are tough, looking for a buyer/expansion. is the mc correct as 2 lots of shares?
Marstons (LON:MARS)
its always the way with mars they never seem to be able to match spoons ref sales increases despite they selective fantastic soundbites and their continual insistance they are beating their market segment (perhaps they are comparing themselves with the old school pubs that closing en masse) .
Hey ho then trend is still decent overall (most ref debt) - crazy that they wouldnt want to keep paying down debt will all spare cashflow they are not reinvesting in growth for another year or two - but hey what they think is conservative gearing is different what i think is sensible gearing - all we know is that too often they have had to cap in hand to shareholders over the last 20 years - they are clearly current on a reasonable stretch - but will that last forever no - should they know that and kick the debt issue into the sidelines forever - yes.
Look at all the positive vibes headline stuff from the company the last 18 months and broker forecasts have pretty much flatlined - infact looks like forecasts have just been lowered as of today - great it is not.
Hey ho with ope of 5.6 and ntav double the sharerice plus a bit i am more positive than negative - with the chunky debt though i think there are less risky options out there even if i do feel eventually the company could get back to £1 per share. I am not selling my holding at this price.
Compared to their nett asset value these shares still look very cheap. L4L sales excluding World Cup but there is positive news around more investment in their estate and returning money to shareholders.
OCS to acquire Mitie (MTO) in £3.1bn deal to create UK facilities services giant
OCS Group International has agreed a recommended cash acquisition of Mitie Group plc, valuing the facilities services provider at up to 221.6 pence per share, including a proposed final dividend, and implying an equity value of about £3.1 billion. The offer represents premiums of more than 40% to recent trading prices, and Mitie’s board, advised by Ardea Partners and Peel Hunt, has unanimously backed the deal, with directors and a major shareholder giving irrevocable voting