Cavendish still going backwards with no tangible evidence yet of a return to form

Analyst’s view:
I was already very worried about this after the H1 trading update, when I said that the company would be doing very well to repeat its FY26 performance in FY27. On the basis of the latest Hardman forecasts, we are now expecting to see FY27 considerably worse than FY26. So I'm inclined to treat this as a fresh profit warning. The market is certainly treating it that way, with the share price down by 9%. The particularly troubling aspect of it for me is the reduction in the cash pile, which has been an important part of the investment thesis for me here. I'm downgrading our stance on this by one notch, to AMBER/RED. Perhaps a revival in the IPO market on AIM is just around the corner, but I don't see it yet - and it has taken far longer than I expected.
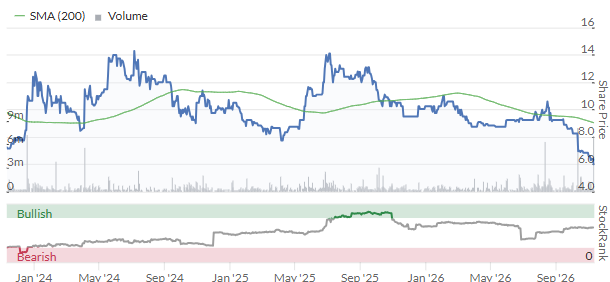
Down 9% at 5.8p (£23m) - Interim Results and Board Change
I've been increasingly worried about this one, and turned down to a neutral stance last month at the H1 trading update.
That H1 update informed us that the revenue result would be "about £22.8m"; the actual result is £22.9m, down 20% from last year after another very quiet period for small-cap IPOs. Transaction-based investment banking revenue fell by over 30%, to £17.9m.
"Core profit before tax" comes in at £0.8m (H1 last year: £2m).
As promised, the company is managing its costs tightly: it plans to reduce annualised costs by £3m, of which about £2m will relate to employee costs.
In this H1 period, employee cash costs already shrank by 24% (from £19.6m to £14.9m) as lower bonuses were paid out on lower revenues. This is the main reason why the company was able to eke out a small adjusted pre-tax profit, despite lower revenues.
Adjustments: unfortunately, there is no pre-tax profit on a statutory basis. After £950k of share-based payments and £333k of "adjusting items" (more than the entire prior financial year), the actual PBT result is a loss of £500k.
CEO change: John Farrugia (formerly of Cenkos) will no longer be co-CEO, but will he remain "engaged on specific client activity for the foreseeable future". Julian Morse (formerly of Cenkos) becomes sole CEO.
The co-CEO structure is unusual. I'm surprised it lasted as long as it did (3 years), and I wouldn't read too much into this change.
CEO comment: talks up the cost structure which enabled the company to generate a small adjusted PBT, and suggests that revenues can increase in the year ahead.
“In a period of challenging market conditions and deal completion timetables, our lean platform and low fixed-cost base have enabled us to remain profitable in the first half of the year. Despite the slow start to the year with pressure on all businesses resulting from significant geopolitical and economic headwinds, we are increasingly seeing good prospects being generated from several areas of targeted investment in the prior periods. We have a healthy pipeline of both public and private transactions including potential IPOs which are expected to yield greater fee revenues over the next 12 months than we have seen in this period.
Cash balance: I'm very disappointed to see that the cash balance has fallen to only £10.6m (last year: £19.8m). This is blamed on "the earlier payment of prior-year final dividends to shareholders and the relative reduction in transaction fees in the period".
Checking the cash flow statement, I see that working capital - especially a large increase in receivables - drained the cash balance by over £6m. Almost £2m left the company in the form of dividends. Cavendish says that "the cash position is expected to strengthen again from December onwards", but the interim dividend is cancelled.
Market conditions: UK markets remained "subdued", as we know, with "low levels of new issuance and relatively weak secondary-market liquidity" on AIM. By contrast, the private M&A market was "more resilient".
Outlook: expectations of higher interest rates "have weighed particularly on UK small and mid-caps", but a resolution to the Iran war could reverse this.
Estimates: profit forecasts from Hardman have been slashed with FY March 2027 now expected to see a pre-tax loss of £0.4m. The forecast published as recently as June was for a pre-tax profit of £3.6m.
Revenues are now seen at £50.2m, down from a previous estimate of £60m. The prior year's result was £56.9m.
Graham's view
I was already very worried about this after the H1 trading update, when I said that the company would be doing very well to repeat its FY26 performance in FY27.
On the basis of the latest Hardman forecasts, we are now expecting to see FY27 considerably worse than FY26.
So I'm inclined to treat this as a fresh profit warning. The market is certainly treating it that way, with the share price down by 9%.
The particularly troubling aspect of it for me is the reduction in the cash pile, which has been an important part of the investment thesis for me here.
Hopefully it will start to grow again, perhaps with the help of a working capital unwind, but it needs to nearly double to reach the level it was at previously.
In a similar vein, revenue is now heading to be materially lower in FY27 than FY26: and FY26 itself could have been viewed as a depressed level.
The fact that Cavendish has passed the interim dividend and is restructuring employee costs says to me that the expected upswing will not be enough to radically change the company's fortunes for the better.
Overall, therefore, I'm downgrading our stance on this by one notch, to AMBER/RED. It's not easy admitting when I've been wrong, but it's better than the alternative (pretending that everything is fine). Perhaps a revival in the IPO market on AIM is just around the corner, but I don't see it yet - and it has taken far longer than I expected.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Cavendish (4)
Comments here are also visible in the Daily Stock Market Report
But even of the IPOs on AIM this year Cavendish (LON:CAV) only had one. So the problems here stem from more than just lack of IPOs.
It'd be great Graham and team if you're able to interrogate Cavendish (LON:CAV)'s results this morning . Some positives in this such as the IPO pipeline mentioned but I'm also intrigued that cash has halved.
I'll second that please Graham. It looks like a lot more patience is required given how tied to the economy the business is. Good to see they're moving to 1 CEO but shame they dropped the interim divi but entirely understandable. Could see this dropping to 5p and languishing for the next 12 months.
I sold up this morning with a 50% loss over the last few years. UK small market cap it dead and this pipeline of IPO's never materializes. Best chance is for it to get bought out
But even of the IPOs on AIM this year Cavendish (LON:CAV) only had one. So the problems here stem from more than just lack of IPOs.