Churchill China: net cash and a potential operational recovery priced at 8.8x earnings

Churchill China (LON:CHH) caught my eye when I saw it on Ed’s list of Speculative Super Stocks. I’d seen the name before -- it’s a Stoke-on-Trent tableware maker that’s been going since 1795 -- but I hadn’t ever looked at it very closely. Perhaps that’s not surprising as my portfolio favours AI and industrial stocks, and Churchill China makes cups and saucers, among other ceramic items.
On closer inspection, the stock was hard to ignore: net cash, a share price below book, a forecast yield of 5.83%, and a set of problems that, on the company's own account, belong to 2025. What’s more, Roland covered it at Amber/Green on 31 July and holds it – that was a good sign, too.
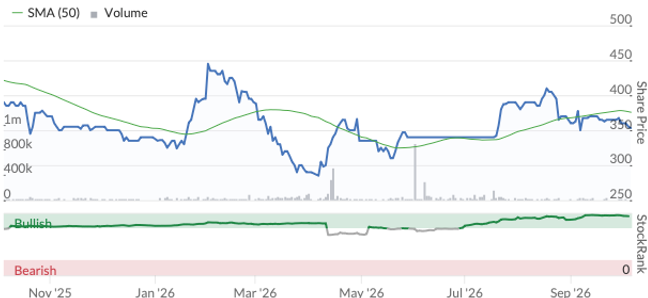
On the quant side, it’s very strong: StockRank 94, Quality 86, Value 95. Momentum at 54 is the only laggard, which is what you’d expect from a share that’s drifted over the past 12 months, and is down nearly 70% over three years.
However, with the business now pointing to an improved pipeline, there's cause to be optimistic.
The Pitch
Churchill fits Ed’s criteria – it’s Speculative, Micro Cap, and Super Stock. That’s a great starting point. Ed's own line was that owning the bucket often pays better than picking from it -- so why does this one deserve a call out?
Churchill makes ceramic tableware for the hospitality trade. The 2025 annual report puts it at over 680 people across three manufacturing sites. The brands are Alchemy, Art de Cuisine, Super Vitrified and Dudson – highly respected, professional grade stuff.
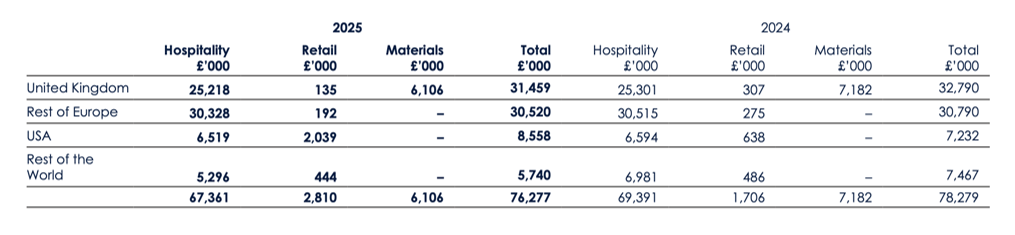
It’s less of a UK story than you might expect. In 2025 the UK was £31.5 million of revenue, with Europe not far behind at £30.5 million, the US at £8.6 million and the rest of the world at £5.7 million. Hospitality is the business, at £67.4 million of the £76.3 million total; materials and retail make up the rest.
For me, the thesis is simple. The market cap is £39 million. Net cash and deposits were £8.5 million at 30 June 2026 and the shares trade at 0.64x book. This means that a fifth of the price is cash and the rest is assets bought at a discount.
The recovery story sits on top of this. The one institutional analyst covering the stock has earnings at 39.6p for 2026, which is 8.8x forward with a 5.83% yield. If it comes through, that’s great. If it doesn't, the cash and the assets are still there.
[Chart: Churchill China 1y share price. Source: Stockopedia]
The Big Picture
The balance sheet is a great starting point, and it’s super strong. Net cash and deposits were £8.5 million at 30 June 2026 against £5.6 million a year earlier. Despite three years of falling sales, the cash balance is up year on year.
Admittedly, the dividend cut has undoubtedly contributed to that growing net cash position. The business paid 38p per share to shareholders for 2024. For 2025, a 7p interim and a proposed 14p final, so 21p in total. The chairman called it a “difficult but prudent decision”. The 2026 interim was held at 7p.
Operationally, energy is the cost that matters most when you run kilns, and the company hedges like an airline. The 2025 annual report pointed to open exposure at circa 16% of gas costs for 2026, with 64% of 2027’s gas requirements already forward purchased.
That’s certainly a positive, but the UK’s energy prices must be a drag on earnings. Sadly, it was the UK that dragged on revenue too in H1 -- UK hospitality sales were down 3.3% in the first half of 2026 and materials sales were behind 2025 by 16.5%.
Overseas had turned before 2025 was out. The final results said European sales in the second half of 2025 were 7% above the prior year, and the interims said European and US sales were slightly ahead of H1 2025 in the six months to 30 June 2026, with the Rest of the World broadly in line.
The thing to watch is the pipeline – and this is where the thesis lies. The 2025 results said the pipeline of projects going into 2026 was stronger than the prior year, with an improved European and UK hospitality pipeline. Q4 is the company's biggest quarter, and the pipeline is where the growth on top of replacement orders comes from. The factory should convert them at a better margin than last year: the trading update said the investment programme is “generating tangible productivity benefits”, including a new flat plate making machine with “measurable benefits in both productivity and waste reduction”.
The interims also said that profitability improved in Q2 and that “the operational issues faced in H2 2025 have been resolved”. The company still expects full-year profitability “in line with expectations”.
“New project business remains at good levels, in particular in the hotel, business and leisure segments.”
- James Roper, CEO (interim results).
Going Deeper
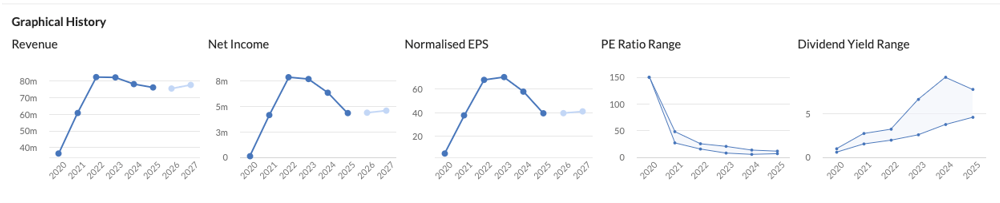
Earnings per share over the past 12 months were half what they were in 2023. That’s clearly the type of reverse that investors don’t want to see. But let’s take the field as we find it today, and relative to the current valuation.
- The operating leverage cuts both ways. Revenue fell 2.9% in the first half and operating profit before exceptionals fell 17.9%. A near-3% drop in sales took nearly 18% off profit. Run that in reverse and you have the recovery case.
- The US is the growth market. USA revenue went from £7.2 million in 2024 to £8.6 million in 2025 while every other region fell over that period. The interims show US sales were slightly ahead again in the first half of 2026.
- A lot of this is replacement demand. The company says a high percentage of revenue comes from replacement orders at good margins. Plates break. Restaurants reorder from the supplier whose pattern they already have.
- The board held the dividend through a 27% EPS fall. 7p interim, unchanged, against 16.8p of adjusted EPS – that should provide some confidence.
- The management change is internal. James Roper, 14 years running Sales and Marketing, took over as CEO on 26 August 2026. Dave O'Connor, 35 years at Churchill and 14 as CEO, stays on part-time. CFO Michael Cunningham announced his resignation on 21 August and is expected to stay until early 2027; the board is looking for a successor. Panmure Liberum replaced Investec as nomad on 7 September.
- Somebody doubled up. Raymond James Wealth Management went from 6.63% to 12%, notified 5 August 2026. The annual report also lists Aberdeen plc at 9.87%, Rathbone plc at 9.23% and Mrs S Roper at 8.06%.
[Table: FY25 revenue by market and segment. Source: Churchill China Annual Report 2025]
Valuation
It's no surprise to see the shares on lowly multiples after three years of falling revenue. On the positive side, there's plenty of room for the multiple to expand if the business does what the sole analyst expects.
- 8.8x forward earnings. Trailing is 10.2x.
- A 5.83% yield covered 1.9 times. The 21p dividend was cut from 38p for 2025.
- 0.64x book, 3.58x EV/EBITDA. Market cap £39.6 million, enterprise value £33.3 million.
- £8.5 million of net cash and deposits. About a fifth of the market cap.
The business has existed since 1795 – that doesn’t mean it’s a safe bet. But it’s a brand(s) hospitality buyers know, and the market has it at two-thirds of book value with a fifth of the price covered by cash.
[Chart: Growth & Value panel. Source: Stockopedia]
What the Brokers Say
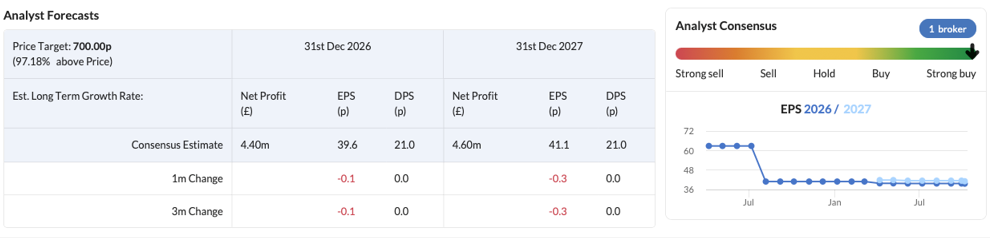
Only one broker covers the stock – unsurprisingly for a Micro Cap. Its forecasts are 39.6p for 2026 and 41.1p for 2027, with a 700p target (97% above today’s price), and they have barely moved since the 31 July trading update. That broker is Panmure Liberum, which has also been the company's nomad and sole broker since 7 September. So read the target accordingly.
[Chart: Analyst consensus / EPS estimates. Source: Stockopedia]
The Bear Case
A recovery could be on the cards, but there are plenty of risks worth bearing in mind:
- UK hospitality is still shrinking. UK hospitality sales down 3.3% in the first half, materials down 16.5%. The 31 July trading update: “Whilst sales visibility remains limited and recognising the significance of the final quarter of the year, the Board is reassured by the resilience of trading during the first half.”
- The gas is bought ahead, not fixed. A third of 2027's gas is still at the mercy of the market. Roland’s longer-term worry, in his 31 July note, is that a high cost base and exposure to UK energy prices eventually erode the company’s viability. I can’t dismiss that.
- Lots of change at management level. Roper started on 26 August 2026. Cunningham goes in early 2027 and the board has begun the search for a successor.
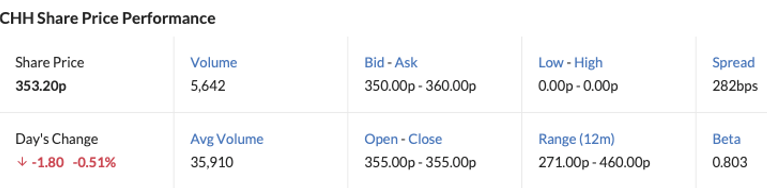
- Thinly traded. 11 million shares in issue, an exchange market size of 750, and a 556 basis point spread. I got a live quote for £10,000 of shares without trouble but it’s likely easier to buy than to sell.
[Share price and trading data. Source: Stockopedia]
The Bottom Line
Churchill has net cash worth a fifth of the market cap and pays 5.83% on a dividend that's already been cut. The gas is bought. The factory problems are, on the company's account, fixed. And the shares are on 8.8x forward earnings.
That multiple is pricing three years of falling revenue. The thesis is that it's wrong about 2026. The pipeline is stronger than it was, Europe turned in the second half of 2025, and the factory is more efficient.
If the second half lands, the multiple has a long way to go. The valuation, however, is a backstop.
There's no scheduled date for the next update. Last year's final results came on 13 April.
[Disclosure: at the time of publication, James Fox has no position in Churchill China.]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Churchill China is a puzzle. The share, which was trading at close to £20 five years ago, ticks all the right boxes on the Stockopedia rankings in terms of quality and value. However, barring a dramatic improvement in its end markets and a marked reduction in its long term energy costs, it is hard to see what will trigger a significant re-rating in its shares.
In addition, there is one area of potential concern not reflected in the statistical rankings - the low level of the non-executive directors’ ownership of CHH shares. The chairman and non-executive directors have a combined shareholding which is worth less than £50,000 compared with their annual directors’ fees of £262,000. Despite CHH’s lowly share price the non-execs have shown themselves reluctant to invest in the business in a meaningful way.
I agree with your comments often looked at Churchill China (LON:CHH) which I see as a ' curate's egg stock' and thought is it lowly enough rated to cope with the various issues. It is and has always been a could be scenario. I have never taken the plunge. Costs to me are the issue and with it being unclear where the Gas price will go I am still on the sidelines. No idea if Government support is what it says it is and taking this on trust as a fall back seems to me to depend on your skepticism over what happens if this is withdrawn. It is hard to see the Gas price coming back given geopolitical issues.
This is an industry that has cried wolf on costs and rightly so. Yes it has a good balance sheet and this insulates but as another correspondence says no buying from non execs and I would prefer to see something here.
If I had to take a stake in the industry I would rather buy into the greater potential at Portmeirion ( Spode) but again it seems to me these companies need a good US Xmas. I think the jury maybe out on that
Always happy to be wrong
I've been tracking Churchill China (LON:CHH) on my watchlist for a few years now. Good quality operator, market leading position, resilient in the face of very tough trading conditions in the last few years. Even Aurora / Phoenix Asset Management hold it, and they are value and quality investors who like to do deep research into management, operations, moat.
However, I have invested into Portmeirion (LON:PMP) instead, after their SP crash and equity fundraising at 50p.
I wrote a long article on my Substack about why I've invested and the imminent catalysts that I see for a re-rating in the next 12 months. But here's a quick one-liner summary of each.
This is a company that looks great on paper but a dog in the real world. Wouldn't touch it with a bargepole, but who knows, it's a very strange time in the market generally.
The spread was huge when I last looked.
It takes buyers and sellers to make a market. Time will tell who is right.
All the best
Cheers James,
I hold already. Bought some months ago around the current price. More or less on the basis of your analysis. It just looks too cheap.
James Roper must know the busIness inside out and upside down. He is a significant shareholder together with other family members. Similarities with James Halstead (LON:JHD) another family business that has been about for a long time where family members continue to manage the company and remain substantially invested. Again a very strong balance sheet but has struggled of late. I also hold.
Thank you James, this is on our monitoring list and except for momentum fits Ed's 4 buying signals. We'll join Roland on the shareholder list this morning with a starter position.