Computacenter: yet another earnings upgrade as data centre boom continues

Analyst’s view:
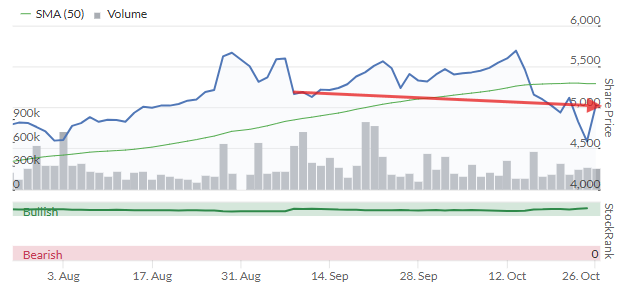
In September, we reverted to a neutral stance on Computacenter. Today, with a slightly cheaper share price of about £50, and another earnings upgrade, I think it makes sense for us to get back onto a moderately positve stance here. The earnings multiple is still rather expensive for Computacenter; we need to be aware that any weakness in the AI/data`centre boom could feed through rather quickly, which would make the stock look significantly overvalued. For now, however, there are few signs of the boom slowing down.
Up 9.6% at £50.30 (£5.3bn) - Q3 Trading Update
It's a terrific update from Computacenter today, raising PBT expectations for the current year from consensus (£387.1m) to new guidance of at least £425m.
This is on the back of an "excellent" Q3 performance that was ahead of their expectations:
Group Technology Sourcing revenue continued to grow strongly, primarily driven by hyperscale and neocloud customers in North America and the UK. Group Services revenue was also ahead of last year, as strong organic growth in Professional Services, also driven by North America, more than offset a decline in Managed Services revenue.
As noted by Roland, Computacenter is a prime beneficiary of the AI and data centre boom. Note the importance of North America: at the half year results, this region was responsible for 60% of adjusted operating profit.
That trend continues, with the UK and Germany also making important contributions:
By geography, North America continued its strong momentum, with record levels of project completions, benefiting both Technology Sourcing and Professional Services, while also increasing its committed product order backlog.
Order backlog rises to £12.9 billion, vs. £9.3 billion at the end of June, with "a strong pipeline of opportunities in North America and the UK".
Graham's view
In September, at the half-year results, my colleague Roland took us down to a neutral stance on CCC, citing the heavy valuation. The share price at the time was about £54.
With a slightly cheaper share price of about £50 today, and another earnings upgrade, I think it makes sense for us to get back onto a moderately positve stance here.
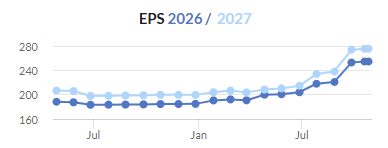
Today's PBT guidance is 10% higher than prior consensus.
If I naively increase the 2026 consensus EPS forecast by 10%, I get 280.5p, putting the shares on a current-year PE ratio of 18x.
This is still rather expensive for Computacenter. We need to be aware that any weakness in the AI/data`centre boom could feed through rather quickly, which would make the stock look significantly overvalued.
For now, however, there are few signs of the boom slowing down.
This is just the latest in a series of earnings upgrades at Computacenter. It can't last forever, but I wouldn't want to fight against this trend.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Computacenter (2)
Comments here are also visible in the Daily Stock Market Report
Morning Graham
I would be interested in your thoughts on Auction Technology (LON:ATG) where a board battle and activist shareholder is trying to stimulate more value recognition in the share price. As a holder I certainly would like to see an uplift but don't necessarily want to see it becoming another US listing.
Also any comment on Computacenter (LON:CCC) who appear to have up graded 2026 profits by nearly 20%. Hopefully the share-price will reflect a good deal of this!
In the last few weeks every positive announcement in my portfolio has seen a share price fall, so I am not getting too excited.
best wishes
Greyster
I am also a holder of Auction Technology (LON:ATG) and this is shaping up to be a major distraction for the new CEO who i have some faith in. Any views welcome. I will not be voting to support the Yankees