Conduit's growth slows down but earnings forecasts hold up well

Analyst’s view:
We've been moderately positive on this on the basis that it offers value against its tangible NAV, and I'm inclined to stick to that stance today. Although today's update may have disappointed some investors, I never want to penalise companies for focusing on their margins and profitability over their short-term revenues. That's true in every industry but I think it's particularly appropriate in insurance. Today's update can be viewed as a revenue warning, but it's no profit warning. Today's share price is equivalent to $5.65, so we still have a discount of about 25% against last-reported NAV, and the earnings multiple is in mid-single digit territory.
Down 4.5% at 425.5p (£658m) - Trading Update
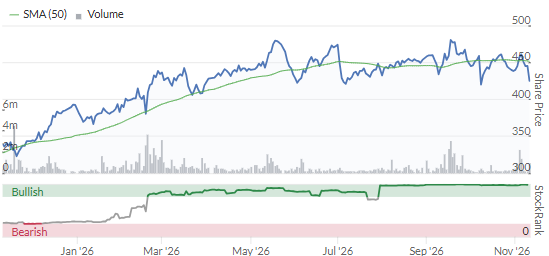
We were moderately positive on this reinsurer in February (article by Roland), and the stock has had a decent year so far:
EPS estimates: today's update has been accompanied by a 1% increase in the EPS forecast for FY26 at Panmure Liberum (from 88.6 US cents to 89.9 US cents). There are negligible changes to the forecasts for FY27 and FY28.
Highlights: although EPS forecasts are unchanged, thanks to a benign loss environment in the insurance industry, there has been a slowing of expected growth.
Gross written premiums are down by 4% year-to-date, and GWP forecasts have also been reduced by 4% at Panmure Liberum. GWP is seen gradually falling each year out to 2028.
Today's trading update explains the slightly muted growth outlook:
Gross premiums written have declined modestly as we continued to execute our underwriting strategy to rebalance the Property portfolio towards higher margin excess of loss business in a softening market, while Casualty premiums have increased 8.9% due to growth with preferred clients.
The transition towards higher margin business handily explains how lower GWP forecasts can be accompanied by unchanged (or even slightly higher) EPS forecasts.
I note the reference to a "softening" market - this is very consistent with what we've heard from others in the insurance space. Property and Specialty seem to be particularly weak.
The good news is that this is being balanced by an absence of very large claims:
The first nine months of 2026 was a relatively benign period for insured natural catastrophes but experienced elevated frequency of Specialty losses; additionally, our undiscounted ultimate loss estimates... for previously reported loss events remain stable.
Net investment return was minus 0.4% for Conduit's portfolio year-to-date. Perhaps that is no great surprise given the rise in interest rates; the company is carrying "unrealised losses related to a significant increase in treasury yields during 2026.".
Outlook: softening rates are expected to continue. Conduit will "manage our underwriting appetite and capital deployment carefully... focusing on preferred clients and classes with more stable conditions."
Graham's view
We've been moderately positive on this, on the basis that it offers value against its tangible NAV, and I'm inclined to stick to that stance today.
Although today's update may have disappointed some investors, I never want to penalise companies for focusing on their margins and profitability over their short-term revenues. That's true in every industry but I think it's particularly appropriate in insurance. Today's update can be viewed as a revenue warning, but it's no profit warning.
At the interim results, tangible NAV per share was $7.56.
Today's share price is equivalent to $5.65, so we still have a discount of about 25% against that.
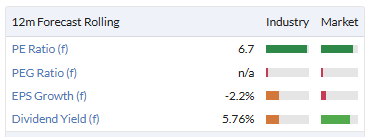
The earnings multiple is in mid-single digits:
With this degree of value on offer, I remain comfortable with our stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Conduit Holdings (1)
Comments here are also visible in the Daily Stock Market Report
Conduit Holdings (LON:CRE) 9 mth figures out today. Previously the rating has gone from AR to A to AG so is it still AG or does it drop back today ?