Daily Stock Market Report (Fri 13 Dec 2024) - DWHT/DWHA, IPX, PCGH, PMP, CARR, POLN

Good morning!
12:20pm: that's a wrap! Have a nice weekend.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet). Updated to 10/12/2024.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Boohoo (LON:BOO) (£485m) | Response to Frasers | BOO conditionally willing to offer Frasers one Board seat, but not to Ashley or his insolvency expert. | |
Polar Capital Global Healthcare Trust (LON:PCGH) (£438m) | Final results | Net assets up 14%. Trading at 5% premium to NAV. | AMBER/GREEN (Megan) |
Impax Asset Management (LON:IPX) (£434m) | Update on assets under management | Termination of mandate from SJP. Loss of £5.2bn AuM, £12.7m annual revenues. | BLACK - GREEN (Graham holds) |
Tullow Oil (LON:TLW) (£379m) | Possible offer | Preliminary discussions of all share offer by US group Kosmos Energy. No price given yet. | |
Chapel Down (LON:CDGP) (£60m) | CEO Appointment, Outlook | New CEO. CFO resigns. 2024 harvest in line with announced tonnage. Full year is in line. | |
Portmeirion (LON:PMP) (£28.7m) | Trading update | Profit warning. Supply delays mean PBT is now expected to be £1m | BLACK - AMBER/RED (Graham) |
2.40pm update: I (Graham) now have a long position in Impax, after buying shares in it this afternoon.
Summaries
Impax Asset Management (LON:IPX) - down 19% to 264.5p (£338m) - Update on assets under management - Graham holds - GREEN
Impax loses an important mandate that represented £5.2bn of AuM (14% of total) and £12.7m of revenue (7.5% of total). In response to major criticism of how it does business, St James’s Place has been moving some of its biggest mandates, and Impax is not the only victim of this. But with no more SJP mandates for Impax to lose, hopefully we will be spared any more announcements like this for some time.
Dewhurst (LON:DWHT) / Dewhurst (LON:DWHA)
A-Share down 3% to 550p - Final Results - Mark - AMBER/GREEN
Trading here is reasonable, although the outlook highlights the risk of weak trading in the UK following recent budget changes. The shares are very cheaply rated on a number of metrics, apart from the one that matters most for a mature business with a large unutilised cash pile: the dividend. A dividend cover of over 4 is daft, in my opinion, and takes the shine off an otherwise decent performance.
Portmeirion (LON:PMP) - down 18% to 169p (£24m) - Trading Update - Graham - AMBER/RED
A painful profit warning and the most worrying element of it for me is not the downgrade to 2024 forecasts, but the removal of 2025 forecasts. As there is no visibility and the company remains indebted, I’m taking a mildly negative stance.
Carr's (LON:CARR) - Down 4% to 117.9p (£111m) - Full Year Results (yesterday) - Graham - AMBER
A complicated situation here with the impending sale of a large division to an unknown bidder for an unknown price. Hopefully the disposal will go ahead, as I agree that there are no synergistic benefits between an Engineering Division and an Agriculture division. The current market cap looks like it could be fair but the wild card is the price ultimately paid for the Engineering division.
Short Sections
Polar Capital Global Healthcare Trust (LON:PCGH)
Unch. today at 361p (£438m) - Final Results - Megan - AMBER/GREEN
Following your feedback in our recent survey, Graham and I have decided that we’ll try and cover the odd investment trust or ETF when there is some interesting news. We both like this section of the market and we hope we can contribute something interesting to the conversation (I would also point anyone who hasn’t found it before in the direction of Charles Mitchell’s monthly investment trust thread).
This morning my attention has been captured by Polar Capital Global Healthcare Trust (LON:PCGH), which has reported a decent set of financial results, despite relative weakness in the market it benchmarks against (MSCI All Country World Daily Net Total Return Health Care Index).
Healthcare and pharma is a complex industry which does require a level of specialist knowledge and for that reason, this is a sector where I think trust exposure makes a lot of sense.
Polar Capital’s healthcare trust aims to invest mainly in global large and mega-caps. And its the exposure to the European healthcare market that has served it in especially well in the financial year under review. The trusts’ net asset value (NAV) rose 15% compared to the previous year to £479m, equivalent to a period-end NAV per share of 395p. That’s an 8.6% premium to the current share price.
The fund’s top performing asset in the year to September 2024 was the loss-making Danish group Zeland Pharma, which specialises in metabolic diseases and has this year been swept up in the hype surrounding the weight loss medicines made by its domestic peer, Novo Nordisk. Zealand’s own obesity drug started enrolling for its phase 2 clinical trial earlier this week and is therefore unlikely to hit the market for several years. And yet the company’s share price more than doubled in the year to September. The average weight of Zealand in the PCGH portfolio was 4.7% during the period.
There have been other strong performances from biopharma companies in Europe, including Sanofi, UCB and Swedish Orphan Biovitrum. The trust also built its position in Novo Nordisk - too late to have have impact in FY2024, but ready to benefit from the ongoing demand in the weight loss and diabetes market.
Megan’s view
Healthcare is an interesting investment proposition. There is huge scope for innovation both in medicine and technology to improve clinical outcomes worldwide in the coming years and this is something I find very exciting.
Donald Trump’s impending second term is causing some concern for the sector, which relies so heavily on the vast expenditure of the US healthcare system. But truly innovative companies should still be well placed for growth.
Examining the underlying assets of PCGH provides a stark contrast to GSK - the UK pharma company that I have looked at this week in response to a reader request (you can read that analysis here). My verdict on the latter is that it remains strictly an income opportunity, while the pharma companies held by PCGH look like they could be well placed for growth.
Pollen Street (LON:POLN)
739p (£455m) - Q3 Trading Update (yesterday) - Graham - AMBER
This is now both an asset manager (3rd party funds) and an investment company (own funds). The asset management side continues to grow:
Total AUM reached £5.0 billion as of 30 September 2024, up from £4.2 billion in Q3 2023 and fee-paying AUM stands at £3.5 billion as of 30 September 2024 as fundraising continued steadily across the platform but with most capital being raised in Q4.
Those final few words bode well for the full-year AUM result.
The focus is on credit and private equity, with expectations to hit a €1 billion private equity fundraising target by year-end 2024.
The interim results showed tangible balance sheet net assets of £348m, supporting most of the market cap. The investment company’s leveraged credit portfolio is the main event here.
Graham’s view - I like unusual situations where a company’s quality might be improving, and that may well be the case with POLN. I’m going to stay neutral for now until I have researched it in more detail; if it was trading at a discount to TNAV I could probably have gone AMBER/GREEN already.
Graham's Section
Impax Asset Management (LON:IPX)
Down 19% to 264.5p (£338m) - Update on assets under management - Graham - BLACK (profit warning) / GREEN
2.40pm: I (Graham) bought a few shares in Impax this afternoon, so as of writing I now have a long position in IPX.
This is very disappointing news and comes just two weeks after the annual results were published.
Impax has lost the mandate from St. James’s Place to manage the Sustainable & Responsible Equity Fund, subject to the approval of unitholders in January.
It represents £5.2bn of AuM and £12.7m of annual revenue.
For context, Impax’s total AuM of as of Sep 2024 was £37.2bn and total revenue was £170.1m.
If there is a bright spot, it’s that while the mandate represented 14% of AuM, it only represented 7.5% of revenue.
The reason given is:
The termination of the Mandate has been driven by SJP seeking to further diversify the fund across investment styles.
That may very well be true but I would take it with a pinch of salt, as it’s rare that we would ever be given a more controversial reason than this. Lagging the performance of funds in its sector is a more likely reason.
Impax has no further mandates with SJP, so at least there are no further SJP mandates to lose.
We already knew that SJP had allocated its Global Quality fund away from Impax a few months ago, leaving only the Sustainable & Responsible Equity Fund.
Graham’s view
I find this news very disappointing, as I thought Impax was going to keep this mandate. In October, after the loss of the Global Quality fund, they said:
Impax continues to manage the much larger portfolio, the Sustainable & Responsible Equity Fund, on a sole basis on behalf of SJP. St. James's Place concluded that the Sustainable & Responsible Equity Fund "delivered value overall" to clients in its recently published Annual Value Assessment statement.
On that basis, I thought there was a good chance that the mandate would be kept. I was wrong.
The loss of 7.5% of revenue is a real blow - given the nature of fund management (high scalability and high margins), I expect a large chunk of that revenue to be missing from bottom line profitability in the current year. Today’s near-20% fall in the share price does make some sense.
In the big picture it is just one mandate, and I think it’s driven primarily by the well-publicised problems at SJP rather than by the underperformance of Impax. Hopefully, this will be seen as a minor event when we look back on it in a few years.
I’ll leave my GREEN stance unchanged as I have little doubt that Impax remains profitable and enjoys the same long-term rebound prospects as it did before. But perhaps the dividend cut will need to be sooner and larger than anticipated.
We are now down by over 80% from the peak share price at £14.80. I turned GREEN on it at 710p (May 2023), which in hindsight was far too early, and I hold my hands up:
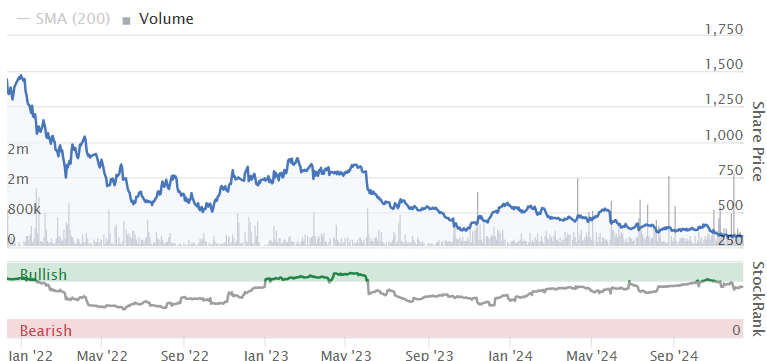
Two funds have been shorting Impax in size and increasing their bets since the summer, but one of them (at JP Morgan Asset Management) recently reduced its short interest for the first time. With this bad news out in the open now, perhaps it’s time for shorters to start closing their successful bets?

Portmeirion (LON:PMP)
Down 18% to 169p (£24m) - Trading Update - Graham - AMBER/RED
Portmeirion Group PLC, the owner, designer, manufacturer and omni-channel retailer of leading homeware brands in global markets, provides an update on its trading position ahead of its year end on 31 December 2024.
This is a severe profit warning and I note that it has landed with only about two weeks until the end of the year.
2024 revenue is now expected at £90m (previous forecast from Singers: £100m) with PBT at £1m (forecast: £4.5m).
The reasons given are:
Supply chain disruption from Asia, and shipping disruption into the US (port strikes).
South Korea: destocking and consumer confidence issues due to inflation, interest rates and a weak currency.
More generally, “challenging and unpredictable market conditions” with uncertainty around political events (US/UK).
South Korea: sales down 13% year-on-year in H2, with recovery taking longer than expected after a terrible H1.
Excluding South Korea, sales are down 6% in H2, or down 3% for the year as a whole.
Outlook: nothing too concrete here. US sales are expected to rebound in 2025, and they are also expecting an improvement in Korea. Various actions have been taken to fix the logistics problems of 2024 but I doubt that it’s enough to restore investor trust any time soon.
CEO comment: I agree with “Wolf of Small Street” in the comment thread below that this is unsatisfactory:
The impact of lower sales in South Korea and the resulting lower utilisation of our UK tableware factory has had an adverse impact on 2024 profitability, excluding which, overall Group net profitability would be significantly up on 2023.
It’s fair enough that only one country is responsible for the damage to profitability, but sales were still down even if we exclude South Korea. And PMP did overestimate the ability of Korea to rebound. We all make mistakes but there is no need to sugarcoat them like this.
At least the “Wax Lyrical” (scented candles and diffusers) division is doing well.
Graham’s view
I don’t have a very strong view on the fundamentals of this business - clearly it used to be a high-performer, but in recent years it hasn’t been.
The CEO was appointed in late 2019 and has presided over a difficult period:
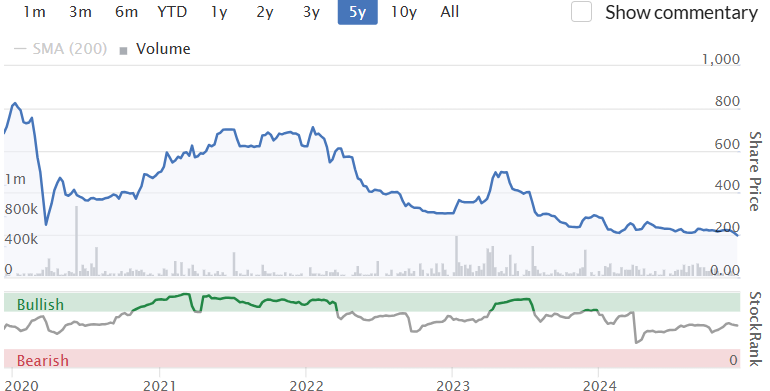
Checking the brokers today, I see that Shore Capital have left their 2025 and 2026 forecasts unchanged “at this stage” but they put them in italics to indicate that they will be updated at the next trading update in January.
Singers have been even more cautious and removed all forecasts beyond 2024, waiting for the January trading update “when management should be in a better position to guide”.
My interpretation of the above is that there is no visibility here, for anyone.
When a company is cash-rich and highly profitable I can live with very low visibility.
But when a company is in net debt (c. £15m) and barely profitable, I can’t combine that with zero visibility.
I’m therefore inclined to put this at AMBER/RED to reflect the lack of information and the potential for financial risk.
Carr's (LON:CARR)
Down 4% to 117.9p (£111m) - Full Year Results (yesterday) - Graham - AMBER
This has an Engineering Division and Agricultural Division, but the Engineering division is on the way out as management decided that it did not make sense to have two divisions without synergistic benefits.
The announcement of this strategic decision was made in April and the Engineering division is still here, but management say that the sale process “is ongoing and progressing positively”.
For the FY August 2024 results, I think it makes most sense to focus on Table 2 - continuing operations excluding the Engineering division, i.e. Agriculture division only.
These results show revenue down 7.5% (to £76m), adj. operating profit down 24% (to £2.2m), and £9m of adjusting items. So the actual operating loss was about £7m.
Strategy - specialist agriculture. CARR “will manufacture and sell research proven supplements for extensive grazing markets globally”.
This division is said to have had a difficult H1 but then saw trading improve in the seasonally lower volume H2.
Three underperforming subsidiaries have been closed since Dec 2023, so perhaps that’s a cause for optimism in the new financial year?
Adjusting items: £6m of “restructuring costs and historical pension liabilities”. I tend not to allow restructuring costs to be adjusted out in their entirety, as most businesses are nearly always restructuring to one extent or another. So I’d be unlikely to allow this entire £6m adjustment.
There’s also a £3m impairment charge.
Dividend: unchanged at 5.2p for the year, which I think costs about £700k. The company has net cash for continuing operations of £8m to help support this.
Outlook:
The immediate prospects for the Agriculture Division have been enhanced by the arrival of a new leadership team and remedial actions taken on under-performing businesses during FY24. The long-term outlook for the division remains attractive with our focus now on our range of existing products, further development of that portfolio and entrance into new geographies. Any benefit from reduced drought areas and the US beef cycle turning will further complement these opportunities.
Graham’s view
This is too complicated for me to take a view on, as I have no idea what the Engineering Division might fetch or if a sale will even go ahead. For FY24 it generated revenues of £60m (+19%) and an adj. operating profit of £7m, for an adj. operating margin of 12%.
Perhaps someone would pay £70m for this, or 10x adj. operating profit? I cannot judge. It makes “bespoke equipment, vessels, precision components and remote handling systems”, and operates under six different brands.
If someone did pay £70m for it, that would leave c. £40m of CARR’s market cap to be accounted for by the Agriculture division. Margins here seem to be very low, at least in the last few years. But hopefully it’s on the rebound now and could justify a £40m valuation. Forecasts from Cavendish (continuing operations only) suggest an adj. PBT of £3.6m in the new year.
I have to be neutral on this, as I’m unable to value it and the range of possible outcomes is too wide.
Mark's Section
Dewhurst (LON:DWHT) / Dewhurst (LON:DWHA) - A-Share down 3% to 550p - Final Results - Mark - AMBER/GREEN
This company has a rather strange dual share structure with a family-controlled ordinary share having all of the voting rights, but A shares are cheaper and more liquid (if that’s possible to say for such an illiquid share!) and economically identical. There is no reason for independent shareholders to consider owning the ordinary share, in my view. Here are the headlines:
I am delighted to report record sales and improved profits. Operating profit is up 5% and profit before tax is 7% higher. Group sales for the year to 30 September 2024 ('2024') increased 11% to £64.4 million (2023: £58.0 million). Operating profit was £8.1 million (2023: £7.8 million) and profit before tax was £8.6 million (2023: £8.1 million). Earnings per share were 66.58p (2023: 62.45p) up 7%.
The Chair must be easily pleased if a 7% EPS rise on an 11% sales growth brings delight. However, in a historical context, this is a reasonable, if not delightful, outcome:
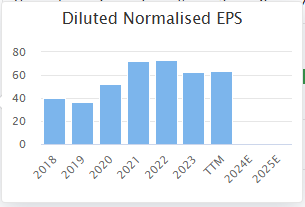
Like many companies at the moment, costs are rising ahead of sales, meaning there is no operational gearing. However, unlike many companies, rising debt costs are not a problem as they have net cash:
The Group started and ended the year without any bank borrowings. The cash balance at year end was £21.6 million, down £2.8 million from £24.4 million in 2023.
This means that they have positive net financing costs. Average interest works out to be 3%, so we can either conclude that they don’t have that level of average cash balance, or that their treasury function needs a major overhaul. Assuming the former, then the average cash balance is still a very reasonable £15m or so. Reported cash is down over the year, but this has gone to good use:
During the year, the Group spent £1.5 million to acquire the remaining 25% of the shares in P&R Liftcars, £1.8m on the purchase of own shares, and £0.9 million on the purchase of property, plant and equipment.
Any companies that claim that they can’t do a buyback due to illiquidity should be pointed towards Dewhurst, who have managed to buy £1.8m worth in the year despite being a very illiquid stock. (For example, the day before the results were published, around £5k was traded in the voting shares, and there were no trades in the A-Shares!)
There is a large pension fund which has been a drag on cash in recent years:
The Company paid a total of £3.9 million deficit reduction contributions into the pension scheme this year and I am pleased to report that the deficit decreased by £5.1m and is now in a surplus position of £3.0m (2023: £2.1 million deficit) on an IAS19 basis.
Being in surplus on an IAS19 basis doesn’t mean they won’t have to make further contributions. It seems that these may be getting close to ending, though, which should provide a boost. When the latest Annual Report is published, we should be able to see the details of any remaining agreed payments.
The problem is that we don’t really know if they are going to use that cash productively. They’ve previously talked about acquisitions, but none have been forthcoming. This has been the case for a number of years and they seem no closer to any acquisitions of scale or any other use of the cash. This time, they don’t even mention them. Hence, the dividend payout is far too low, in my opinion:
The Board is proposing a final dividend of 11.50p (2023: 11.00p). If approved, this would be paid on 26 February 2025 and would result in a total dividend for 2024 of 16.50p per share which is 4.8% up on 2023 and is covered 4.3 times by earnings.
4.3x cover is just daft, in my opinion, and it seems management likes to hang on to the cash out of a desire for extreme safety, rather than having a master plan, as yet unseen.
Net assets increased to £63.m, of which £3m is the pension surplus, which is not accessible (or perhaps real!), £9.5m is intangibles, the bulk of which is goodwill. Net tangible asset value is, therefore, £50.6m.
Calculating how this compares to a market cap is tricky. There are 3.3m ordinary shares, which trade at £11, and 4.4m A shares, which trade at £5.50. This works out to be around £57m. However, as a holder of the A shares, an investor has economic exposure to the proportion of A-shares in the capital structure x their percentage holding of the A-shares. The effect of this is to take the total share count of 7.85m and multiply by the A share price, which is just £43.2m effective market cap at £5.50.
I think it is fair to argue that a buyer of the A shares is buying at a discount to TBV at the moment, and the buyer of the Voting shares is not. Not that it matters unless those assets are productive, or the non-productive ones, such as cash, are returned to shareholders. Still, it helps gauge how cheap the shares are and the value difference between the A-Shares and Voting-Shares.
In terms of outlook, they say:
Group sales have started the year slightly up on last year and in line with our expectations.
But, like many companies, the UK budget fallout continues to weigh heavy:
The outlook for growth in the UK has worsened since the new Government's October budget with our customers' mood dented by the additional financial burden placed on companies. It remains to be seen whether this is a temporary setback or whether it will have longer-term effects. If tariffs are introduced on elevator products imported into the US from Canada and the UK this is likely to be detrimental to our business, but it is too early to assess the scale of the impact.
Mark’s view
Roland rated this GREEN when he looked at it in mid-2023. The results have been better since then. However, I think he may have been too enthusiastic about where this company is going. Many of the valuation metrics do look very cheap. However, a reluctance to pay out a dividend commensurate with their profitability means that investors have to trust that they have a long-term strategy for growth utilising that retained capital. Something that the company has no history of, nor a well-described strategy to achieve it. As such, it is AMBER/GREEN for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Polar Capital Technology Trust (LON:PCT) (I hold). From Citywire Polar Capital Technology (PCT) fund managers have jumped into power and network provider stocks as they look to exploit the rapid growth in US data centres as artificial intelligence takes off. https://citywire.com/investmen...
US company Equinix (NSQ:EQIX) is the largest REIT holding "digital architecture" , also Digital Realty Trust (NYQ:DLR) There is an ETF Pacer Data & Infrastructure RE (PCQ:SRVR) and WisdomTree Cloud Computing UCITS ETF USD Acc (LON:WCLD) for cloud computing. Bit of research to be done over the holiday period !
Impax Asset Management (LON:IPX) I bought these after the recent figures- assuming that these would be accurate re AUM. Things like this happen, and I will hold on. On reflection maybe specialist fund managers in one sector are likely to have these issues re performance. Taken to its logical conclusion IPX should probably be part of a larger fund management group , so one sector falling out of favour does not affect the managers so much.
Impax Asset Management (LON:IPX) have been seeing very hefty outflows even before today's announcement, while performance in their main funds isn't great. I am avoiding, as feels like interest in ESG investing will continue to fall and wouldn't be surprised to see further big outflows.
Let us see what the board do.
No sign of Santa yet
I think he's been with us since 6 November! You may not have recognised him because this year he's got a blond quiff and a MAGA hat rather than white beard and red trousers.
Indeed! 100 has risen 250-300 points in the last month, not sure how much upside there may be next couple of weeks. Hopefully i'm wrong!
Great to see some comments about investment trusts on here, especially Polar Capital Global Healthcare Trust (LON:PCGH) which I hold (albeit a relatively recent holder, so have been hit by the decline in the share price since Trump's RFK announcement). There was one interesting comment in today's results which I have copied below:
The Board has started considering the future of the Company in light of its fixed-life and has commenced work with its advisors on developing and potentially bringing forward proposals for a corporate reorganisation in 2025. This would be ahead of the requirement to propose liquidation at the first AGM to be held after 1 March 2025 which would ordinarily take place in early 2026.
It will be interesting to see what this "corporate reorganisation" looks like. I very much hope the Board and the Manager will bring forward a proposal which acknowledges the interests of small individual shareholders, not just the institutional holders.
I appreciate you comments on Investment Trusts . Are infrastructure not a tempting buy at the moment
Yes REITs and infrastructure funds looked incredibly oversold in my view, and there are a lot of good quality trusts on 20-30% discounts paying 8-10% (and growing) yields - if rates ever do come down you could see significant captial upside on top of those attractive income streams.
Thank you Megan for mentioning the Monthly Investment Trust thread. Many people contribute to it, I just start it afresh each month. I hold Polar Capital Global Healthcare Trust (LON:PCGH) and under the last Trump admin the sector did OK. Time will tell but it is, in my opinion, the best Trust in this sector.
Can i just say thank you to all the writers that have created so much output over the last week.
Much of this is done while many of the readers are still happily tucked up in bed.
Thanks for the write up on Dewhurst (LON:DWHA) . As you mention the shares are very illiquid - therefore it is worth doing some work on the stock before buying it.
I held one of the voting shares so that I could attend a recent AGM (in Feltham), after which the board was very open to questions and a tour of the plant. This was really useful for me and afterwards I decided not to invest.
The firm has many motivated and long-standing members of staff. However, I was struck (despite a few new machines) by the amount of manual labour necessary in the assembling process. One of the key attractions to the A share (in particular) is that it is trading at a discount to tangible book value. But my take away from the visit was that I felt that a discount to tangible book value was sadly appropriate as I questioned whether the business of assembling lift control systems had a long-term future in the UK against lower-wage competition.
There were a number of serious investors at that AGM and most of those I spoke to came to a different conclusion to me. So I would not suggest to anyone to follow my conclusion but I would recommend buying at least one of the voting shares to attend the AGM - as this gives you a really good idea of the business you are investing in.
As an ex-holder of Impax Asset Management (LON:IPX, my condolences go to those still holding which includes a couple of my younger family members. One thing I would point out to those still holding and by way of a soft counter to Graham’s continued Green stance, is that the US is their largest source of revenue. Personally I do not think ESG strategies will prosper under a Trump presidency but i hope that I’m wrong.
I'm no fan of either of these Coys and agree ESG has lost its attraction but it strikes me that if IMPAX was doing a good job they would not have lost this account . A quick Look on trustnet shows their funds are 4th quartile which maybe proves the point.
Industria de Diseno Textil SA (MCE:ITX)
Owner of Zara.
Not sure if this was covered the other day but there was a profit warning that will probably affect all retailers.
All the best
Industria de Diseno Textil SA (MCE:ITX)
Yiannos1 you are such a tease. Why not say something like "competition from Shein" or "adverse currency movements" rather than "All the best"?
Industria de Diseno Textil SA (MCE:ITX) and the recent strength of the dollar should actually give the company a boost!
Have a look at Jeffries US investment bank detailed new report (if you have access of course) and a spent a couple of hours reading it (exactly what I have done) than just throw a few meaningless sentences just because you see Yiannos1 has posted.
This forum needs a reliable source of information.
ALL THE BEST
Morning Graham and team - any chance of a quick review on CPPGroup (LON:CPP) following on from the Blink contract wins this week? It looks SO cheap (cash on balance), divested out of its non-core businesses and is now looking like a very interesting insure-tech business winning mandates with big insurance companies globally (AXA etc). Thank you
Thanks Jcry, this can go into the backlog for a potential review, I can't guarantee we'll cover it but cheers for the suggestion! G
Thanks. You might be pleasantly surprised! :)
London, 13 December 2024 - Impax Asset Management Group plc announces that it has received a notice from St. James's Place Unit Trust Group Limited ("SJP") of termination of Impax's mandate to manage the Sustainable & Responsible Equity Fund (the "SRE"), (the "Mandate").
The Mandate is the only mandate that Impax has with SJP and totalled c.£5.2bn of assets under management ("AUM"), as at 30 November 2024. The impact on Impax's revenue is expected to be circa £12.7m on an annualized basis.
Impax Asset Management (LON:IPX) down 19% in early trading!
Was rated green recently :(
A blessing in disguise, I feel, losing the SJP mandate.
Impax
Agree
Losing business I used to find in many cases turned out positive
And lets not lose any sleep over SJP an absolute shower of money grabbing gangsters in suits
My parents were/are still with them and despite my banging my head through their kitchen wall over the ludicrous annual charges my mum says
“But we dont mind shes really lively (the advisor) dont forget she got us those lovely electric blankets last year”
I guess thats the annual review meeting ticked off (ill just drop off your christmas present tactic)
Scumbag company pity they dont do something more useful like tarmac a drive .
If I had a drive, I'd love it tarmacked!
From my 'contacts', shall we say, SJP are in the process of reducing the number of asset managers they use across the board.. They intend to end up with a much reduced, concentrated set of managers. Good news if you happen to hold any of those, bad news if you hold some of the others, like Impax Asset Management (LON:IPX). It's linked to their cost reducing strategy reported by Citywire at the end of November (they are also making around 500 staff redundant).
Not sure if who runs mandates for SJP is public information, but might be worth looking into for anyone that holds fund manager shares, as there will most likely be more changes ahead.
Good morning, can anyone explain what is happening at Metals Exploration (LON:MTL) and the possible consequences? Thanks
Ref Metals Exploration (LON:MTL) in what way do you mean. They are planning to buy Condor Gold (LON:CNR) thus the never ending (and pointless RNS) and Nick Candy has sold all his shares to Nick Candy. Have I missed something else?
Perfect - thanks
Shareholders don’t get cash just loads of useless metal shares. Sold.
Me too
@Metals Exploration I think the real issue is that their Runruno mine in the Philipines only has a couple of years life left so they have to buy something to stay in business,
Portmeirion (LON:PMP) Got to admire Mike Rayboulds banter. If he's not using brokers to downgrade forecasts without having the guts to tell the market, he's inventing new realities. If my granny had wheels she'd be a bicycle
"The impact of lower sales in South Korea and the resulting lower utilisation of our UK tableware factory has had an adverse impact on 2024 profitability, excluding which, overall Group net profitability would be significantly up on 2023.
I remember Paul did an interview with him a few years ago. Came across as rather stand-offish so glad I swerved this one. The state of director buys is joke too. Nothing for 2.5 years. If they can’t get excited about PMP then we’re definitely not. Shame to see a British heritage brand so poorly run especially one from Stoke, a town that could do with decent growing employer.
Classic case of a CFO stepping up to CEO but without the skills. I listened to the same interview. All was going swimmingly until Paul asked him right at the end why he wasn't buying any shares in the company. He had no answer to that at all and we saw why he wasn't buying in the next set of results. It's been downhill ever since. Nice place poor company.
Filtronic (LON:FTC) was perky yesterday, possibly helped by a valuation of $350bn put on SpaceX, but the share price has been moving sideways over the last few months. Nice to have wealthy friends.
Great to have FTC ( I hold ) and alot easier than accessing SpaceX. Hard to buy (& value) according to Matthew Levine of Bloomsberg https://www.bloomberg.com/opin...
Well done on the very early analysis Mark and Graham, it makes for a good start to the day although I read Portmeirion's RNS and think I heard the sound of smashing crockery? We used to hold and still monitor them, perhaps you'll cover it today if you have time.