Daily Stock Market Report (Fri 20th February 2026) - CHRY, SWC, SBTX

Good morning! Let's see what Friday's news feed has for us.
There's nothing else where I feel I can add much value today, or where it's particularly interesting. So I'm going to call it there - see you next time! Cheers.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£237bn | SR79) | AstraZeneca's Calquence in combination with venetoclax has been approved in the US as the first all-oral, fixed-duration regimen for the treatment of adult patients with chronic lymphocytic leukaemia and small lymphocytic lymphoma. | ||
Anglo American (LON:AAL) (£42bn | SR55) | Underlying EBITDA of $6.4 billion (2024: $6.3 billion). $1.8 billion of run-rate cost savings delivered. Loss of $3.7 billion, including a pre-tax impairment of $2.3 billion relating to De Beers. | ||
SEGRO (LON:SGRO) (£10.8bn | SR77) | £99 million of new contracted rent commitments and 6.0 per cent growth in like-for-like net rental income. Estimated Rental Value +3.1 per cent in the UK. Occupancy increased 90 bps to 94.9%. Adjusted pre-tax profit +8.3% to £509m. | ||
TBC Bank (LON:TBCG) (£2.4bn | SR65) | FY 2025 profit of 1,420 million Georgian Lari, up by 9% YoY, with ROE at 24.2%. As outlined in the third quarter, group net profit for 2025 was below target. Total dividend per share for 2025 of GEL 8.87, an increase of 10% year-on-year. | ||
Chemring (LON:CHG) (£1.42bn | SR54) | FY26 outlook in line with the Board's expectations. H2 weighting slightly heavier than the prior year. | ||
Chrysalis Investments (LON:CHRY) (£464m | SR) | Proposed New Investment Policy, New Management Arrangements and Notice of EGM | The Board believes returning capital to shareholders on realisations is more appropriate than reinvesting in new investments. New investment policy is to effect an orderly realisation of its assets. | AMBER/GREEN ↓ (Graham) |
Tullow Oil (LON:TLW) (£155m | SR29) | Trading Statement & Ghana Petroleum Agreements Extended & Refinancing Transaction and Lock-Up Agreement & SPA to acquire TEN FPSO in Ghana | “2025 full year free cashflow was negatively impacted by the commodity price environment towards the end of the year and delays in receipt of Government of Ghana receivables and the second instalment of proceeds from the Kenya disposal.” Group working interest production in 2026 is expected to average 34-42 kboepd, including c.6 kboepd of gas. | |
Residential Secure Income (LON:RESI) (£103m | SR75) | Total EPRA return for the quarter of 0.5% (0.3p) to give EPRA NTA of 62.6p (£134.1mn) (last night’s share price: 55.4p). | ||
Smarter Web (LON:SWC) (market cap uncertain, SR23) | £225m raised, including £209m in equity capital. PBT £2.8m. Excluding one off gains and fair value adjustment, the result would have been a loss before tax of £1.5m. The operating business has continued to perform in line with expectations. At the year end, the Company held 2,660 Bitcoin, with a market value of approximately £220m. | AMBER/RED ↑ (Graham) I’ve been consistently RED on SWC as I viewed it as ludicrously overvalued. I no longer consider that to be the case. I still think it’s a very strange beast and I have zero temptation to get involved. But it seems to be worthy of an AMBER/RED today, on the basis that it might offer value at this level. Which is not something that I was able to say before. | |
Pulsar (LON:PULS) (£60m | SR41) | £7m of cost savings. ARR at year end increased to £64.5m, up £3.9m. Adjusted EBITDA +13% to c. £10.2m, in line with expectations. | ||
Rentguarantor Holdings (LON:RGG) (£41m | SR21) | Rob Rinder MBE will expand his role of brand ambassador to support the Company's mission. Issuing Mr Rinder with 348k warrants at exercise price of 33p (last night’s price 28.5p). | ||
Skinbiotherapeutics (LON:SBTX) (£15m | SR9) | NED is appointed to oversee the continuing investigation process on behalf of the Board. Existing external legal and professional advisers will support the process as necessary. | RED = (Graham) When the figures are in doubt, it is best to stay ultra-cautious. Investigations can be expensive, time-consuming and complicated. I’ll stay RED on this until we have more clarity. |
Graham's Section
Chrysalis Investments (LON:CHRY)
Unch. at 95.3p (£464m) - Proposed New Investment Policy, New Management Arrangements and Notice of EGM - Graham - AMBER/GREEN ↓
Perhaps naively I was GREEN on this fund in November when the NAV was 171.65p and the share price was 120p.
The share price is now only 95.3p (down 21%), and the last-reported NAV (December 2025) was 165.36p (down 4%).
So the discount to NAV has grown considerably wider: from 30% to 42%.
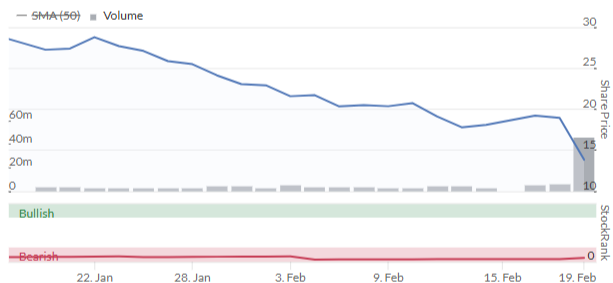
However, that’s based on their holding Klaria Pharma Holding AB (publ) (STO:KLAR)’s price at the end of December. Klarna has more than halved since then, and it just crashed 27% after a profit warning:
Chrysalis also has a massive exposure to Starling - and it’s not clear when the IPO of that business might happen.
Today’s announcement confirms that Chrysalis is going to wind down.
They start with the suggestion that their continued wide discount to NAV might partly reflect investor apprehension that they will make new investments:
The Company has returned over £100m of capital through share buybacks over the last two years in line with the Capital Allocation Policy ("CAP") adopted in March 2024. Whilst the discount to NAV has improved, it has not improved significantly. The Board believes that this persistent level of discount is a market driven issue but is also, in part, because of the perceived risk of reinvestment in the Chrysalis strategy.
They continue with the observation that the company has only returned 1.13x the value of the money it has raised since inception seven years ago. And that is measured in NAV.
At market value rather than official NAV, the shares trade at a 34% discount to the average price at which new money has been raised.
Conclusion:
Based on this historic performance, the Board believes returning capital to shareholders on realisations is more appropriate than reinvesting in new investments.
Turning to their current investment advisor, they say that it “has not developed its regulatory and operational capacity as envisaged” since March 2024.
They say they have sought to make changes to their agreement with the manager (“Chrysalis Investment Partners”, or CIP), but that their proposals have not been agreed to.
As a result, they have served notice on CIP. They might just manage the portfolio themselves after that:
Unless other arrangements can be reached with the Investment Adviser during its six month notice period, the Company's intention after the expiry of that notice period is to operate with a self-managed model in delivering the New Investment Policy…
CIP have published a response (not via RNS - I received it through PR channels). Among other things, it says that the self-managed option would have negative consequences for shareholders. I’ll publish their fears about the self-managed model in full, as I think it’s instructive and I don’t think it’s available via RNS.
Here are their objections (emphasis added):
The Board does not have the Adviser’s detailed knowledge of the assets, developed over many years, or the established relationships with portfolio company management teams to support an orderly and value-focused realisation process.
Nor does the Board, whose role it is to provide governance and oversight, have the expertise to run an investment mandate, even one in wind-down.
The Company is likely to permanently lose its board representation at Starling Bank, which accounts for more than half of the Company’s net asset value. The loss of influence at such a pivotal holding would materially weaken oversight and impair value realisation.
The Board’s proposed self-managed structure could ultimately increase annual costs for shareholders, given its stated intention to rely on external transactional services, such as accounting, legal or other advisory firms.
The Board is not incentivised to maximise value, whereas the Adviser is fully aligned with shareholders. A significant proportion of the investment team’s personal wealth is invested in the Company. Their interests are directly tied to maximising value for all shareholders over a reasonable period.
Graham’s view
I regret being fully GREEN on this in November, although I did at least acknowledge that their portfolio was heavily concentrated. It turns out that Klarna has hurt them more than their largest holding Starling in the short term.
At this point, I think it makes sense for me to downgrade to AMBER/GREEN. This recognises that there is still a wide discount - even wider than before - but also acknowledges the complexity involved.
It also acknowledges that the wind-down process could be problematic. If CIP’s warnings have merit, that would be bad news for shareholders here. On balance I’m inclined to think that CIP’s warnings do have merit, but that’s only based on an initial review. The Chrysalis board have hired a new NED with experience at Allied Minds (some of you will remember that one).
So I’m going to take my stance down by one notch. A big discount to NAV always gets me interested, but I have to acknowledge that shareholders here do face some big risks, most notably execution risk (will the wind-down be successfully managed?) and concentration risk.
An overview of the portfolio, to help you see the concentration:
Starling 53%
Smart Pension 15%
Klarna 11%
Wefox 7%
Brandtech 4%
No other position is larger than 3%.
I don’t know how quickly they can sell out of Klarna but that one in particular looks like it could be a massive drag on short-term performance.
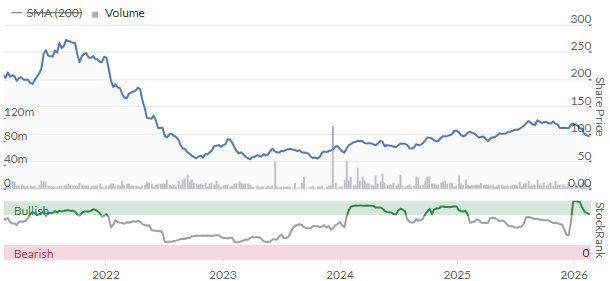
The long-term Chrysalis share price (5 years): it has done ok for anyone who bought after the post-Covid crash.
Smarter Web (LON:SWC)
Down 4% to 32.76p (market cap uncertain) - Full Year Results - Graham - AMBER/RED ↑
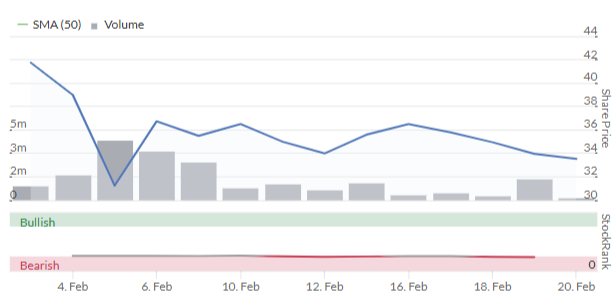
Stockopedia is treating this as a new listing. It moved directly to the Main Market from Aquis at the start of this month, bypassing AIM:
For those who might not be aware, it is the biggest “Bitcoin Treasury” company in the UK, and also has a small web development business attached.
The CEO announced grand ambitions as the shares started trading on the LSE:
We remain committed to building a British success story that contributes meaningfully to the UK economy, showcases the ambition of the UK's entrepreneurial spirit, and demonstrates the role that Bitcoin, as a form of digital capital, can play in supporting the growth of modern businesses."
My first task is to get a handle on the correct share count, as the company has been aggressively raising funds.
This has been entirely rational behaviour by the company, as far as I’m concerned. It’s what you should do when you’re overvalued!
The most recent subscription agreement, outlined on Christmas Eve, allows for the almost continuous sale of new shares by the company’s broker.
The announcement said that total voting rights would reach 350 million after the sale of 63.2 million new shares.
So it seems to me that the correct market cap to use is £115m, not the number shown on the StockReport.
However, I’m wondering if perhaps the company might be running out of new investors?
15th Jan 2026: £1.7m raised
26th Jan 2026: £0.5m raised
2nd Feb 2026: £0.1m raised
9th Feb 2026: £0.5m raised
16th Feb 2026: £0.2m raised
These numbers seem to be getting smaller. Less than £200k was raised in the most recent announcement.
And it would make sense to stop issuing new shares when the shares are much more keenly priced in the market.
The first of the raises mentioned above was at 51p, while the most recent was at 38p. And the share price now is less than 33p.
Let’s turn to today’s full-year results.
Key points:
Pre-tax loss of £1.5m before one-off gains and fair value adjustments
Pre-tax profit £4.3m after those gains and fair value adjustments
Finished the year with 2,600 bitcoin with market value of approx £220m.
2026 year-to-date, the bitcoin price is down 24% in GBP:
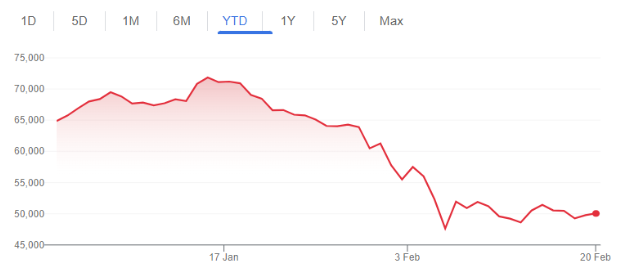
But SWC’s year end is October. Since then, the Bitcoin price is down by 40% in GBP.
So let’s apply a 40% haircut to SWC’s year-end BTC holdings. That gives a current value of £133m (before any purchases made since then).
Outlook:
Looking ahead, the Company remains focused on executing its strategy, strengthening the operating business, progressing its acquisition pipeline, and managing its Bitcoin treasury in a disciplined manner. The Board enters Financial Year 2026 with confidence, supported by a strengthened balance sheet, an expanding operating platform and a clear strategic roadmap for long-term value creation.
Graham’s view
I’m going to have to do some back-of-the-envelope calculations, and I apologise for any errors.
My assumptions:
The bitcoin they held at the end of October are now worth £133m.
Their unusual bitcoin-backed loan note is still a liability worth c. £11m (though it may have reduced).
Their operating business is breaking even (probably false but let’s just assume it).
This gives a current value of £121m, which is reassuringly close to the current market cap of £115m.
However, that market cap assumes 350 million shares outstanding. And that’s only true based on the company issuing lots of shares and raising lots of cash since the financial year-end in October, and into the future:
November: they raised £0.4m
December: nothing raised
Jan/February: £3m raised total
Over January and February, I count circa 6.3 million new shares issued.
Unless I’m mistaken, that still leaves 57 million new shares under the subscription agreement that have not yet been placed by their broker.
If the broker managed to get them away at 25p for example, that would raise an additional £14m (gross). But it's also possible that they might end up selling them at 10p - I don't know.
So if the true share count is 350 million, I think we should also add in about £17m to the NAV. This gives about £138m of value.
So in my eyes, SWC shares could genuinely be trading at a discount to fair value now.
That doesn’t make them a bargain.
In particular:
The operating business may have a negative value, not a neutral value as I assumed.
It’s not clear to me how desperate the company and its broker might be to sell the remaining 57 million new shares. They might keep selling all the way down, or they might stop diluting at some point.
Also, please bear in mind that my calculations are very rough and may be flawed.
I’ve been consistently RED on SWC as I viewed it as ludicrously overvalued. I no longer consider that to be the case. I still think it’s a very strange beast and I have zero temptation to get involved. But it seems to be worthy of an AMBER/RED today, on the basis that it might offer value at this level. Which is not something that I was able to say before.
Skinbiotherapeutics (LON:SBTX)
Down 4% to 5.5p (£15m) - Independent Investigation Appointment - Graham - RED =
Before getting into today’s update, I wanted to catch up on Monday’s announcement.
Here are some snippets from Monday’s announcement. Referring to their former CEO (emphasis added):
In addition to the initial concerns around his conduct, in light of the newly available information, the Board has reason to believe that the former CEO has misrepresented material information to the Board and senior management, the Company's auditors and advisors…
The Board currently expects that the FY25 Accrued Royalty Income, which amounted to £0.77m, will be removed from the FY25 accounts….
The Board is confident, however, in the underlying financial health of the business due to its robust cash position (£2.92m as at 13 February 2026).
FY25 total sales were £4.6m, so £0.77m is a very material figure for this company.
The pre-tax loss for the year was £0.7m.
Revenue and the loss will of course have to be restated, if the royalty income is invalid.
The Board said that they think the real FY25 operating loss will be £1.47m, and issued an official profit warning for FY26.
Today’s announcement: they have appointed a NED, the Chair of their Audit Committee, to oversee the investigation.
This NED only joined the Board in January and so cannot be accused of failing to spot the problem before it happened.
Graham’s view
I’m obviously staying RED on this. The profit warning is no surprise - when the CEO abruptly left, it made sense to presume that FY26 expectations would not be met.
Where I do slightly take issue with the company’s statement is when it refers to its confidence in its "underlying financial health” due to its “robust cash position”.
That £2.9m figure is indeed robust, but only if we presume that the company is soon going to stop running an annual operating loss of c. £1.5m.
Forecasts in the market suggested that SBTX would be around breakeven this year, and then maybe earn a small profit next year.
Based on recent developments, I would now presume that the company is going to make a meaningful loss in both of those years.
That doesn’t mean their £2.9m cash balance is insufficient. But when the figures are in doubt, it is best to stay ultra-cautious. Investigations can be expensive, time-consuming and complicated. I’ll stay RED on this until we have more clarity.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Looking on the Smarter Web Investor Relations site (equity snapshot) as well as the 350m shares in issue (as of 24 Dec 2025, there are also 96m pre-IPO warrants (2.5p exercise price, April 2028 maturity) outstanding. These are clearly deep in the money and can I think be viewed almost like shares (one should add £2.4m to the assets, reflecting the cash that will come in on the exercise of these warrants). Adding these to the shares already issued, gets to 446m shares and at 33p a share would get to an (adjusted) market cap of £147m - so still comfortably above the current market value of £121m that Graham gives for the Bitcoin.
Pretty interesting and well-informed discussion of Chrysalis here! My original GREEN stance was clearly too optimistic.
Graham- you might still be right. Klarna has been a surprise since the successful IPO. The board taking on self managing was never going to go down well with the manager, but I would argue Starling is beyond the size of needing help from the Manager sitting on the Board- and would argue that given they are winding the trust up, so not in a position to invest further should probably not have seats on the boards of holdings- it could curtail their ability to dispose of them. I hold and have no plans to sell at the moment.
Something has to be done about Stockopedia false data. Either warnings or something - we are paying for this service and investors can falsely think that say a company is trading at a certain market cap when it isn't! PYX resources has a market cap of £123.44m on Stockopedia when HL is only showing a market cap of £1.02 million???
And on AJ Bell it's 1.15 million. Why do you automatically assume that it is Stockopedia that has the wrong figure?
Pretty simple to check no of shares times price. I don't follow the share at all but using no of shares from B/S on Stocko 462m, and price which they have as 0.25p. I make that £1.15m ish. But I don't really understand why you are making such an issue of it. Great there is clearly a flea in the system. Tell them and they will put it right.
Something has to be done about Stockopedia false data. Either warnings or something - we are paying for this service and investors can falsely think that say a company is trading at a certain market cap when it isn't! PYX resources has a market cap of £123.44m on Stockopedia when HL is only showing a market cap of £1.02 million???
Both quotes are correct. The £1.1 million is the UK value, the £123 million is the NSX value, where the company has its primary listing. The UK listing is what is known as an "orphaned" secondary listing - it's too illiquid to be arbitraged back to the "correct" price.
Presumably the HL value is based on the UK listing, while the Stockopedia listing draws on international data.
timarr
Chrysalis Investments (LON:CHRY) has put through proposals to wind the company up. With a net asset value of 165.36p per share as at the 31st Dec 2025 and a share price of just over 95p, it certainly looks worth a look. Chrysalis only has 12 investments two of the largest of which are Starling Bank and State Pension. Chrysalis is optimistic about these two investments and Chrysalis will be keen to see these go Public. Four other investments are said to have not progressed as hoped but given the massive discount to the last reported net asset value there could still be a very useful gain to be made in the shares
Thanks, mbarnard. Can you advise where this news has been reported please?
RNS and Company website https://chrysalisinvestments.c...
Sorry to be picky, but it's SMART Pension not State.
Thanks for correcting that.
It was easy, my son works for SMART Pension!!!
It really depends if you believe the NAV. Klarna has fallen heavily this year and it appears their other smaller investments are also struggling. Starling bank is the big one and this makes up well over half the NAV - if I was going to invest in CHRY I would want to come up with my own valuation for Starling and would probably just ignore the official NAV.
Feeling seems to be that £4bn is the aim. But Jupiter sold some at a valuation of about £1.5bn in 2023. It is profitable. The Engine part of the business is key- if it can achieve the targeted sales growth then Starting will be in effect a global technology company. Engine's main advantage is that it has been thoroughly tested by being used by Starling- so is a working platform that is being marketed to other banks.
£4bn feels very punchy to me for a challenger bank. Of course a lot of the value is in their Engine software, but at the moment this isn't delivering much revenue so a lot of hope built into that valuation (and of course software mutiples have fallen sharply recently)
Ah, I missed this discussion and posted on the same subject in the Investment trusts topic .
Banking software is my wheelhouse and I've been dimly aware of "engine" (and some direct experience of other challengers in the same space like "10x"). I now have something to research today :)
The fall in the share price of Klarna was accounted for in the latest reported nav
No, the last repeorted NAV was end of Dec. Since then Klarna has fallen about 50% so the NAV will now be lower.
It does look attractive- I hold. Klarna has not been great since IPO. I suspect the board will sell it anyway even at the reduced price due to the need to demonstrate to shareholders they are serious about returning money. I do not like the compulsory tender mechanism at above market price and below NAV. What will that be. If only just above market price it will work like a share buy back and increase NAV for the remaining shares. Are they doing this because of concerns about the value of some holdings ? I have dealt in CHRY twice and lost money both times- I am hoping this time it will be different. Certainly the board seemed focussed, the firing of the manager will save cash so on balance I will hold for the moment. CHRY is often discussed on the monthly Investment Trust thread(under Discuss), though not so much recently.
I had a very quick look at this company. I would not touch it even with this apparent high discount - the concentration is simply ludicrous, 52% in unquoted Starling, 11% in Klarna (which implies around £250mn in one investment - good luck with selling that), and another 7% in wefox whatever that is. This is simply irresponsible asset management. I want to sleep at night with my portfolio.
I guess depends on your appetite for risk- the portfolio concentration has always been pretty clear.
That's what often happens with these venture portfolios - a small number of holdings do particularly well and end up dominating the portfolio. The are highly illiquid so they probably don't have the option to rebalance the portfolio. As I say, you need to really treat this as an investment in Starling, with a couple of other bits thrown in, not as a portfolio.
Do you think it could be acquired by another investment company, attracted to the discount?
Unlikely John if you mean an Investment Trust. A PE firm maybe.