Daily Stock Market Report (Fri 21 Mar 2025) - CRST, VLE, JDW, CWR, PFC, OPG, ASC

Good morning! We have a backlog section from Mark to kick us off today. And the Agenda is now complete.
1pm: all done for now, have a great weekend!
Edit to add: The Week Ahead has now been published with the economic calendar and next week's company announcements - see here.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
J D Wetherspoon (LON:JDW) (£681m) | Interim Results | H1 adj. PBT -8.6% to £33m. Wage costs to increase £60m. Outlook: “reasonable” outcome for FY25. | AMBER (Megan) However much I like Wetherspoons as a consumer and as a listed business, I am concerned that the challenges in the UK’s pub industry will continue to weigh on the performance for some time. |
| Asos (LON:ASC) (£304m) | Trading Update | SP +20% Expects significant improvement in profitability in H1. Stronger gross margin, lower markdown activity, cost discipline. H1 revenue inline, adj. EBITDA ahead of consensus (£34m). | AMBER/RED (Graham) [no section below] I'm going to leave this with a moderately negative view although I do very much approve of the company's strategy to focus on full-price sales and margins over empty revenues. However, at the top of my mind is the net debt position. This was last seen in region of £170m, excluding lease liabilities, after the sale of the Topman and Topshop brands last September. A moderately negative stance therefore seems to remain justified on the basis that this is A) a value trap according to the StockRanks, and B) is likely to still carry substantial debts. Hopefully it can turn into a true turnaround story but I'm not convinced that it's there yet. |
Ceres Power Holdings (LON:CWR) (£139m) | Final Results | Rev +132% (£52m). Adj. EBITDA loss £22m. Outlook: 2025 revenue broadly similar to 2024. | AMBER/RED (Graham) It's an exciting year for the company and I wish it well, but the financials as they stand do not yet inspire confidence. At least they appear to be moving in the right direction. |
National World (LON:NWOR) (£60m) | Final Results | Rev +9%, adj. PBT +16% (£11.1m). Guidance: to meet expectations. | PINK (takeover to be effective by 30th April if there is no further delay). |
Volvere (LON:VLE) (£40m) | Trading Update | NAV ps £17.19 (LY: £14.83). Net income £4.8m (LY: £2.7m). 2025: challenging due to labour costs. | AMBER/GREEN (Graham holds) |
Petrofac (LON:PFC) (£32m) | Financial Restructuring: Update | Defers publication of annual results. Shares to be temporarily suspended from 1st May. | RED (Graham) [no section below] Massive dilution incoming and hopefully the company will be on a more stable footing when that occurs. I stay RED until the procedure successfully completes. Existing shareholders to be left with 2.2% of the company. |
OPG Power Ventures (LON:OPG) (£18m) | Trading Update | SP +5%) | AMBER (Graham) [no section below] No firm view on this as I'm unfamiliar with it and it's involved in power generation in India. Company is bullish on macro with demand for power in India set to rise over the next 10 years. Claims to have net cash of £12.6m after paying down debt. Could be worth looking into but the usual health warnings re: foreign companies will apply. |
Backlog
Crest Nicholson Holdings (LON:CRST)
Up 8% to 164p - Trading Update - Mark - AMBER
Crest Nicholson has been the cheapest housebuilder on TBV for quite some time:
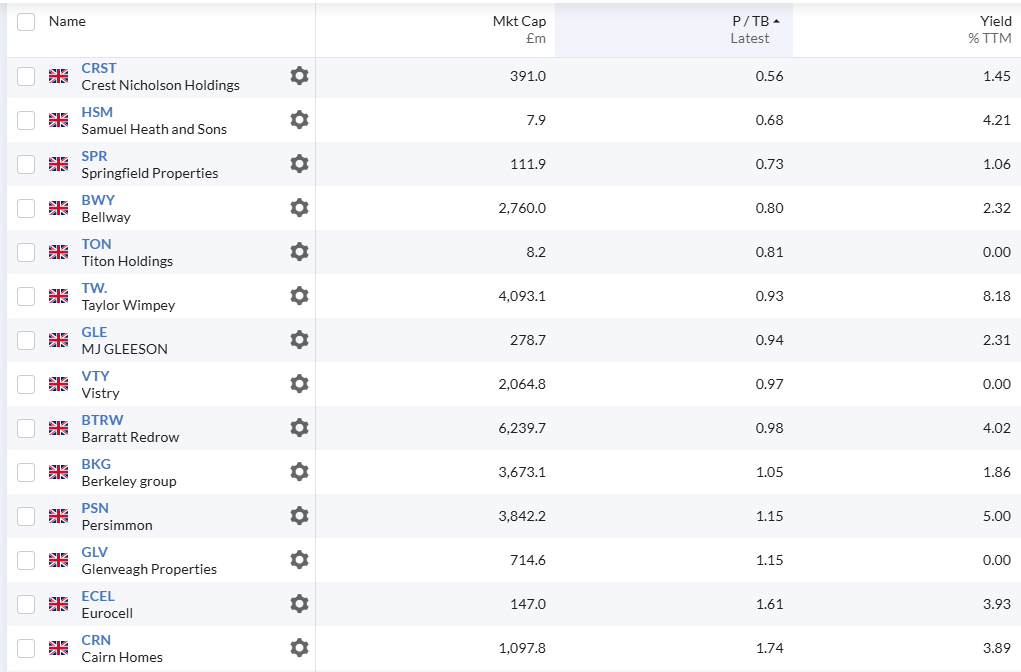
However, many investors will say justifiably so, given those assets have been unproductive for some time now.
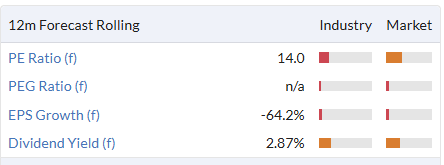
There is also the question of why they haven’t been acquired at this cheap level by someone who is operationally better. After all, there was interest last year that came to nothing. Do the industry experts know something about the company that we don’t? This may well be the large, and still not quite settled, amount the company has had to set aside for remediation of properties containing combustible materials (i.e. cladding.)
Putting that aside, today’s trading update shows that things might be about to turn for the company:
We have seen an encouraging start to the year. In the 10 week period to 14 March, the open market sales rate (excluding bulk) was 0.61 (FY24 0.50), supported by our self-help initiatives including ongoing training and upskilling of the sales team, revised incentive schemes and enhancing our product offering.
The Group has continued to drive higher levels of customer satisfaction achieving a score of 95.0% for the 2024 survey year (2023: 87.3%).
We remain on track to deliver results in line with guidance in the current financial year, with our cash performance tracking better than expected in the first four months.
It is not earth-shattering, but it is certainly good news for a company whose earnings consensus trend looks like this:
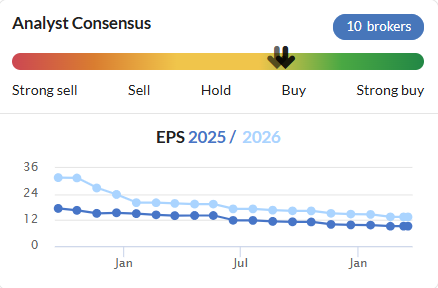
The market liked this update, with the shares rising about 8%. However, they would have to rise a further 40% to be on the P/TBV of the next cheapest housebuilder on this metric.
Mark’s view
The shares look too cheap on a P/TBV of around 0.5, assuming that is now a fair reflection of the fundamentals. If they can achieve the rating of cheapest housebuilder on this metric, then the shares rise around 40%. This trading update gives some hope that momentum may be reversing and that re-rating is on the cards, having looked doubtful for some time. However, the question of why the industry hasn’t closed the gap via corporate action remains. Graham rated this AMBER/RED following recent results due to the large and still variable provisions taken for cladding remediation. However, I think there is enough in today’s statement to consider a tentative upgrade to AMBER.
Graham's Section
Volvere (LON:VLE)
Up 7% to £19.30 (£43m) - Trading Update - Graham - AMBER/GREEN
(At the time of publication, Graham has a long position in VLE.)
This share is 30% of my single-stock portfolio, easily my largest holding, and so I should be considered biased. I’ve owned it since 2016.
Today’s update reads very positively, but most of us Volvere investors already had the impression that Shire Foods has been trading well.
The highlights:
Net assets per share, excluding the minority interest held by staff at Shire Foods: £17.19. This is an increase of 16% year-on-year. NAV had already increased by nearly 7% in H1.
Group net assets increased from £37.5m to £41.8m. The minority interest on the balance sheet is worth £3m+ so shareholder net assets are more like £38m.
Cash and available for sale investments increased from £23.7m to £27.8m.
Buyback analysis
Please note that the above progress was achieved in the context of the company spending £1.5m on share buybacks during the year.
Buybacks reduce net assets and they reduce cash.
However, they do increase net assets per share, when they occur at a discount to NAV.
In 2024, Volvere bought back its own shares at prices of £11.60, £14.50, £14.75, £14.80 (twice), £14.85 and £14.99.
It started the year with NAV per share (excluding minorities) of £14.83, and this had increased to £15.85 by the midpoint of the year. So it has been buying back below NAV.
Financial performance
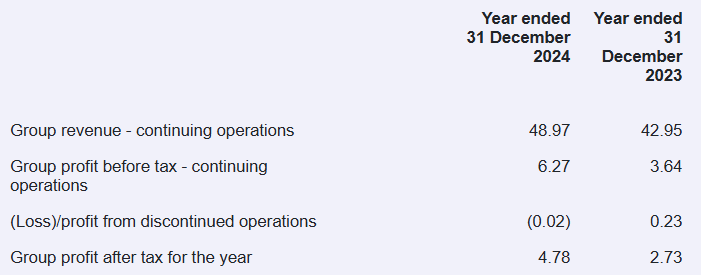
Here’s the table:
Volvere only has one operating subsidiary, Leamington Spa-based Shire Foods.
They have been in the media twice this month. Firstly:
Warwickshire pie supplier celebrates growing Alid partnership (Warwickshire World)
Extract:
Shire Foods, based in Leamington Spa, is working with Britain’s fourth-largest supermarket to bring a brand-new range of Crestwood pies to Aldi shoppers this year.
The new pies, which include an exciting American-inspired flavour, will be available to buy in stores across the UK from May.
Shire Foods has partnered with Aldi since 2008 and is the supplier of its full range of Crestwood Frozen Pies, as well as popular baked items such as its Bacon and Cheese Wraps.
And secondly:
A humble pie with a unique filling and a taste loved by football fans across the West Midlands (Express & Star)
Extract:
The Balti pie is a creation which has become a staple of matchdays for so many football fans across the Black Country and across the country in general, with its warming taste helping many fans to battle the cold during games.
With the Black Country being an area with a high concentration of Indian restaurants, it would be tempting to suggest that the pie was created here.
However, its origins actually lie outside the Black Country in Warwickshire, where Shire Foods in Leamington Spa can lay claim to be the creators of the much-loved pie.
Shire has been on a very pleasing upward trajectory over the years:
2020 revenue £27.2m, adj. PBT £1.8m
2021 revenue £30.6m, adj. PBT £2.1m
2022 revenue £38m, adj. PBT £2.8m
2023 revenue £43m, adj. PBT £3.9m
2024 revenue £49m, adj. PBT to be confirmed.
We don’t yet know Shire’s adj. PBT for 2024, but we do know that Group PBT has increased from £3.6m to £6.3m, and that after-tax profit has increased from £2.7m to £4.8m.
Group PBT, in addition to the Shire result, include items such as:
interest earned on cash
investment gains and losses
administrative expenses including the cost of Group management.
These items, excluding Shire Foods, are grouped together in a segment called “Investing and management services”. This segment was operating around breakeven in H1, whereas it previously operated at a loss when interest rates were lower.
So we’ll have to wait and see how exactly Group PBT of £6.3m was achieved. But nearly all of it should relate to Shire, as I expect that the result for the Investing and management services segment is likely to be around zero for the year.
Commentary
Nick Lander, brother of the late Jonathan Lander, says:
I am delighted with the performance for the year as a whole, which was underpinned by strong trading at Shire Foods and good returns on our treasury deposits. This is reflected in our increasing cash reserves, notwithstanding the significant treasury share purchases in the period.
He goes on to remind us that:
…there are industry-wide challenges in the form of increasing labour costs in 2025 because of the increase in the minimum wage, further compounded by the increase in employer's national insurance. The effect on Shire will be both internal and external, the latter from rising supply chain costs such as raw materials, packaging and transportation.
Despite the challenging environment, he does expect “a creditable performance” this year, and they continue to invest in additional capacity for future years.
On the acquisition front, he says that “we remain committed and poised” to invest if the right proposition is identified. But it has been a very long time since Volvere made a meaningful acquisition.
Graham’s view
The gains here have helped to bring my portfolio to life over the past year:
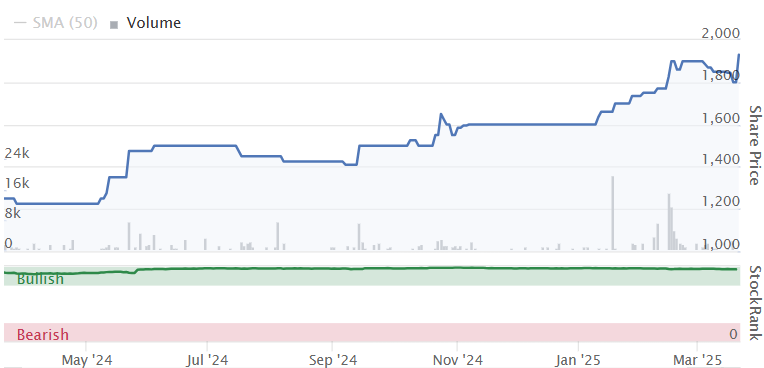
Looking forward, I have mixed feelings about continuing to hold this one.
On the one hand, we have the question of valuation. Cash and available for sale investments cover nearly two-thirds of Volvere's market cap. Unless or until this cash is invested, it backstops much of the value.
Net assets per share also support the valuation, with NAV per share (fully tangible) covering nearly 90% of the market cap.
The wildcard is what could be achieved if Shire Foods was sold.
In a sale, Shire Foods should not be sold for its NAV but instead (hopefully!) for a reasonable multiple of earnings.
Let’s take a £6m profit figure for example, which would be a trailing figure - hopefully 2025 might see some additional progress.
After tax that’s c. £4.5m.
An 80% ownership interest would leave £3.6m.
Is it crazy to think that someone might pay an earnings multiple of 10x to acquire this? Perhaps that’s far too optimistic, but what about 6x?
It’s not exactly the same sector but bakery group Finsbury Foods was acquired for £143m in 2023, on the back of PBT of £16m. That was equivalent to an after-tax earnings multiple of nearly 12x!
If Shire achieved a lowly multiple of only 6x trailing earnings, that would create a £22m valuation, which would see Volvere’s net worth shoot up to £50m. But I very much doubt that Volvere would be willing to sell at that price.
So on valuation, I don’t how see the Group as it currently exists after today’s numbers could be worth any less than £50m in terms of break-up value (that’s £22.70 per share). Given the trajectory of Shire, and the ability of other food manufacturers to achieve decent earnings multiples, I think a significantly higher number makes more sense in terms of fair value.
But (there is always a but!) my main doubt that I have around Volvere is that I can’t actually say that I support its continuation. If there was a vote tomorrow to change its strategy, to enable it to begin a wind-down process, I would support that.
For me, the point of this investment was to back the team (Nick and Jonathan). I’m very glad I did. They did a brilliant job. And I always approached this investment with a lot of patience, because I had faith in that team.
However, with Jonathan having very sadly passed away in 2023, my personal view is that Volvere is in need of a new strategy. My most preferred strategy would be for the company to very gracefully and very calmly call it a day. They don’t need to be in any rush to sell Shire Foods, in the same way that I have not been in a rush to sell my Volvere shares. But they could start the process of looking for an appropriate buyer. Perhaps the recent media articles are a way of discreetly attracting interest. We shall see.
Ceres Power Holdings (LON:CWR)
Down 7% to 66.3p (£128m) - Final Results - Graham - AMBER/RED
Horsham, UK: Ceres Power Holdings plc ("Ceres", the "Company") (CWR.L), a leading developer of clean energy technology, announces its audited results for the year ended 31 December 2024.
This collapsed nearly 40% in February when it announced the loss of its partnership with Bosch.
I took a moderately negative view, as the company’s enormous losses can at least be funded by its cash position (£102.5m as of Dec 2024).
Today we have full-year results, with the following highlights:
Record order intake £113m
Revenue more than doubles to £52m
Loss of £28m (2023: loss of £54m)
The cash outflow was £37.5m.
Outlook:
We end 2024 with a strong financial position and are well placed for significant growth in the future from existing licensees and future partnership prospects in both the SOFC and SOEC (solid oxide fuel cell and solid oxide electrolyser cell) markets. We continue to invest across the business to build a sustainable competitive advantage in highly differentiated solid oxide technology, which offers our partners the potential to industrialise and commercialise stacks and systems with superior efficiencies, reliability and economics for the low-carbon power generation and green hydrogen markets.
The CEO predicts that the first Ceres-based products will be available by the end of this year from Korean conglomerate Doosan.
Balance sheet has equity of £154m, with c. £134m of this being tangible.
Graham’s view
I wish this company well and I do think it’s an exciting moment for them with products hitting the market this year. It’s also undeniable that there has been some financial progress as the full-year loss has very meaningfully reduced. This is due to increased revenues from “technology transfers, development licences, engineering services and the provision of technology hardware”.
However, I do approach early-stage energy stocks with quite a lot of scepticism, as it seems that most of them don’t work out. Most early-stage companies don’t work out, but in many other sectors I find that the prospects of success are more amenable to analysis, at least for me.
For those of us who are unable to evaluate Ceres’ fuel cell/electrolyser technology, what we are left with are the company's financials. While these financials are on an improving trend, they are still deeply in the red. The cash balance, while impressive, will not last forever.
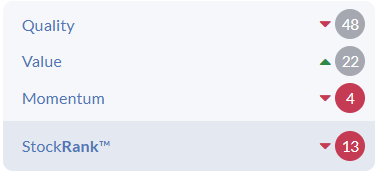
Therefore, I’m still AMBER/RED on this one. That’s consistent with the StockRanks - indeed, the StockRanks are even more cautious than I am.
Megan's Section
J D Wetherspoon (LON:JDW)
Down 9% to 541p (£727m) - Interim Results - Megan - AMBER
There aren't any massive surprises in this morning’s announcement from JD Wetherspoon, the owner and operator of just under 800 pubs in the UK. But the interim results have caused another big judder in the company’s share price.
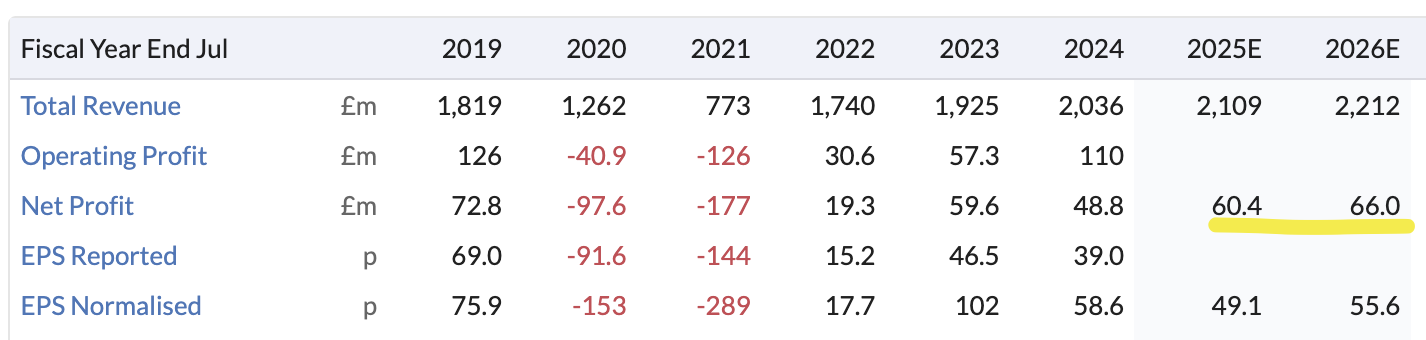
The main concern is a further fall in pre-tax profits to £32.9m (from £36m in the first half of last year). The reason this is concerning is because this decline comes before the impact of higher national insurance contributions, which management has said will add £60m of additional costs per year.
In FY2024, the company only made £60m in pre-tax profits. The year to July 2025 will include four months worth of higher NI contributions (roughly £20m) which means current profit forecasts are probably a bit generous. More concerning is the outlook for the 2026 financial year, which will be the first to include a whole year’s worth of higher NI payments - which currently look meaningful enough to wipe out all of the company’s net profits.
Wage bills have already weighed on the company’s operating costs in the first half of the year, as has an increase in utility bills. Wetherspoons’ founder and chairman, Tim Martin, also points to the increasingly onerous tax burden facing companies in the sector as a reason for disappointing profits.
Mr Martin never shies away from an opportunity to take a pop at the VAT rates paid by pubs which, unlike supermarkets, have to pay VAT on food. And in these numbers he’s once again laid out the contribution his company (and his industry) makes to the public purse. VAT in the first half was £199m, alcohol duty £82m and corporation tax £11m (the latter is already more than the corporation tax in the entirety of FY2024).
Bigger property footprint means higher leverage
It’s a tax burden which Mr Martin says holds a big responsibility for the decline in the UK’s pub industry. A decline which Wetherspoons has attempted to take advantage of by expanding its own estate of pubs and buying up premises which it previously leased. Since 2010, the company has invested almost £500m in acquiring the freehold of pubs where it was previously the tenant. Just under three quarters of the pubs in the estate are now freehold, compared to 41% in 2010. The total value of the company's property, plant and equipment is £1.4bn.
But in doing so, Wetherspoons’ leverage has ratcheted up in recent years. Net debt (excluding lease liabilities) at the period end was £702m, slightly higher than the expected year-end net debt position and materially up from the £660m of net debt on the balance sheet at the end of FY2024. Net gearing, excluding the continuing lease agreements is 270%.
Cash flow troubles
These numbers also include an interesting comment on the company’s free cash flow conversion, which is expected to fall to about 100% of net profits. Management points to the fact that depreciation has and will continue to decrease because some of the older leaseholds have been fully depreciated. At the same time, reinvestment in existing pubs is likely to increase to an average of 3.7% of sales, from 3.1% historically.
These small tweaks are a bit of a moot point in these numbers, as the company reported a free cash outflow after investing £35m in the existing pub estate, £6m in IT services and reporting negative working capital.
Megan’s view
I am never that impressed when company management continues to point to external factors as the reason for underperformance, rather than addressing issues within their own control. But when it comes to Wetherspoons, I do have a spot of sympathy for Tim Martin.
The environment in the UK for owners and operators of pubs is not particularly friendly. Wetherspoons is not the only chain to be struggling and Mr Martin is using his position within the industry to argue the case for more support.
I also like Wetherspoons as a consumer. Mainly because you know what you’re getting - a cheap and cheerful pub, usually in a location that is exactly where you want a pub to be. But it is partly because of that strong identity that the costs of the NI rise are likely to hit the company quite hard. Passing on these additional costs to customers goes against what Wetherspoons stands for.
I do think that in the long-term there could be opportunities for the company to keep expanding as more and more peers go out of business. But there is too much of a storm to weather for now so I am going to stick on the sidelines. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Regarding J D Wetherspoon (LON:JDW) , I'm not a holder, and no expert in the sector, but as a consumer I feel they have plenty of scope to increase prices. There is such a price differential between them and most other pubs (at least in the south east), they could add 10p or 20p to a pint without it materially affecting trade to boost their bottom line.
Evening all could anyone recommend an S&P 500 ETF (not equal weighted version) thats sterling denominated so you don't have to worry about dollar currency fluctuations ?
Regards
Andy
Check Invesco and WisdomTree ETF’s
If not suitable for you, easily can be hedged with a future contract (best 3 months away) on CABLE. Each contract worths £62,500 hedged; best way to hedge and so cheap that makes no difference on your portfolio.
All the best
Thanks Yiannos
iShares do a GBP hedged version if thats what you mean (Ticker GSPX). You could also look on justetf.com
Appreciated Magic
The shares are all based in US$ so you will still get currency fluctuations?
Seems to be the case Rusty I've been looking at Eurostox50 ETF's also seems again they are primarily priced in Euro's.
Join us for MelloMonday on Monday 24th March 2025, at 5:00pm.
We will be joined by Stockopedia's very own Ed Croft who will be presenting on some recent research Stockopedia has done on trading statements and the impact of "ahead" / "below" of expectations announcements, as well as the significance of price jumps.
The programme for the evening is as follows (subject to change):
5:00pm Ed Croft, Founder and CEO of Stockopedia
5:35pm Company Presentation from Shepherd Neame (OFEX:SHEP)
6:15pm Educational Presentation
6:30pm Company Introduction from Nudea (Full Presentation on Tuesday 25th March 2025)
6:45pm BASH (Buy, Avoid, Sell, Hold) Panel featuring Kevin Taylor & Mark Simpson
For more information, click here: https://www.melloevents.com/mm...
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50.
I agree with Rhomboid1: What an excellent and unbiased analysis on Volvere . I know Shire Foods as a competent competitor having spent 20 odd years supplying the UK and European supermarkets.
With reference to Volvere (LON:VLE), their product mix would add to category dominance for Cranswick (LON:CWK) and might find a place with Premier Foods (LON:PFD) . I can't believe Cranswick have not had a chat if Shire Foods is in play. (I hold both but have no holding in Volvere).
Volvere (LON:VLE) what a thoughtful & thought provoking commentary Graham….and as a long term holder I totally agree…so much so that today I took advantage of the liquidity to slice a chunk off my position to redeploy elsewhere where the growth trajectory is less dependent on one factory/product.
This may be a mistake on my part but as they say feed the ducks when they’re quacking
Thank you for the compliments as always Mr. Rhomboid!
The latest Stockopedia feature is very useful , allowing users to filter their news feed to only show folio companies, for example. well done team!
Am I going crazy? Didn't it always do this - at least on the app main screen? That was the first thing I checked every morning, to see the RNS for my folios.
I'm finding it a bit annoying that now it defaults to "My Markets" and I have to click on "My Folio". The in depth filtering is great for further research, just irritating that the app does not default to "My Folio" like it used to.
Yes it did have a split between market and folios.
Seems a few updates are now getting missed by the DSMR team, Asos (LON:ASC) today and 3i (LON:III) yesterday.
ASOS is in there now Rusty, just a brief update from me but it's there for completeness.
OK, thanks, Graham.
yes, I agree . It would be far better if it defaulted , as before, to companies in our folio lists.
Yes it did always do this, and I agree, it's a bit frustrating to have to click each time to see the news I am primarily interested in. Other than that, the other new features are very good.
Seconded! I like most of the features, but I really want it to default to My Folio, as I now have a compulsory extra keystroke every morning....
Agree prefer default to My Folios if possible. Very good development, just a few teething troubles. Thanks team.
I just want to do away with the endless RNS about daily buybacks. What's the best way to filter those out??
Try deselecting "Transaction in own shares"
oh....should have been able to manage that without posting....haha, thanks Rusty
I agree nckthrn.
IG group (LON:IGG) will scrap fees on UK trades wef 1st April, it will also pay 4.5% interest on cash balances, but forex fees increase from 0.5% to 0.7%.
Yes I got that email as a customer - I've got an ISA and Share Dealing acct with them (also a Spread Betting acct which I don't touch anymore as I lose money every time I go near it). I hold IG group (LON:IGG) shares.
They're obviously trying to increase market share with these changes, but what will it do to their profit margin? The 4.5% interest on cash balances is very generous.
I have a share ISA with IG and hold shares. I did wonder about the profit margins, seems quite an aggressive move. I will be moving more cash to them as 4.5% is higher than Hargreaves Lansdown (LON:HL.) or in easy access cash ISAs.
Their hand has probably been forced by t212 offering 4.6% on uninvested cash
They will widen the spread!
All their best
Didn't think of that....
They may do, l will check against other platforms.
I didn't think the platform decided on the spread. I thought that was up to the marketmakers. Am I missing something?
Unfortunately they will.
27.1p to buy to a 27.2p on a 50,000 quote will make more money for them.
This is exactly what they will do and the £3 commission will be suddenly £50.
But of course there will be no commission.
Will be exactly like the old times asking for a quote on a 1M CABLE and then being marked 5 pips up or down depending on your position (commission free of course!).
All the best
Asos (LON:ASC) trading update today, sounds quite good.
Volvere (LON:VLE) has done really well for me over last year, now third largest holding. Still seems under-valued in spite of recent rises, and today's results confirm that.
I like the simplicity of the well run food business and the treasury deposits (to balance the risk of the food industry). I don't think they need to or should start paying a dividend, I'm happy with this balance. The frozen cakes purchase, which was prior to Shire Foods, was a bit of a disaster and I'm sure they will have learnt from that in terms of any future acquisition.
Could it be valued as follows?
£27.8m of cash & short-term investments
£6.3m of Shire Foods profit before tax (and intra group charges). 6x multiple, of which they own 80%. Circa another £30.2m.
£58m of value, or £26 per share (with 2.21m shares in issue), vast majority of which is cash? Less a little bit of debt.
Volvere (LON:VLE)
Along with NAV considerations I would have said that the current enviroment may well throw up some good value acquisitions to get a greater return on some of the cash pile.
A.
Would welcome thoughts on J D Wetherspoon (LON:JDW)
with all the upcoming national insurance / business rate changes I can see lots of smaller independent pubs / bars closing. Wetherspoons will be in a real strong position long term surely
Volvere views today? Looks like serious asset backing....
Volvere (LON:VLE) Market cap £40m. Net Assets £42m! Cash and readily saleable assets £28m. Annual profit after tax £4.8m! Absolutely ludicrous valuation and evidence of a totally dysfunctional UK small cap market. Is there a bigger bargain around? I'm going to to buy this today unless anyone can tell me im missing any obvious howlers!
Interesting RNS from Volvere. Seems most income is from Shire Foods (pies/sausage rolls like Greggs (LON:GRG) . They warn of incoming NI impacts across the sector with internal and external impacts which may dampen revenues like everyone else. I'm keen but will watch with interest.
Are they definitely a supplier to Greggs (LON:GRG) ?
No, they sell to supermarkets.
Profitablity in Volvere (LON:VLE) is much improved to what it was 2 years ago when you could have bought the dip Richard, the share price has risen by 800 pence but still no dividend payable. I don't hold now.
Excellent nos and major tick for Nick after a tough time. Caution into this year I think is temper enthusiasm for similar progress again. Lot of value left and great defensive asset.