Daily Stock Market Report (Fri 22 Nov 2024) - NWOR, GAW, CMCX, MBH, BOY

Good morning!
I'm hoping for a quiet news day today, so that I might cover some backlog stories from yesterday (or from even earlier in the week, if there are any stories you'd like to suggest).
The discussion Megan and I had last night on "Stock Market Sector Trends for 2025" is available here, covering two UK themes (National Insurance and the Strategic Defence Review) and two US themes (Trump's trade policies/protectionism and deregulation).
Now let's see what the RNS has in store for us today.
All done for now (12.45pm). Have a nice weekend everyone.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
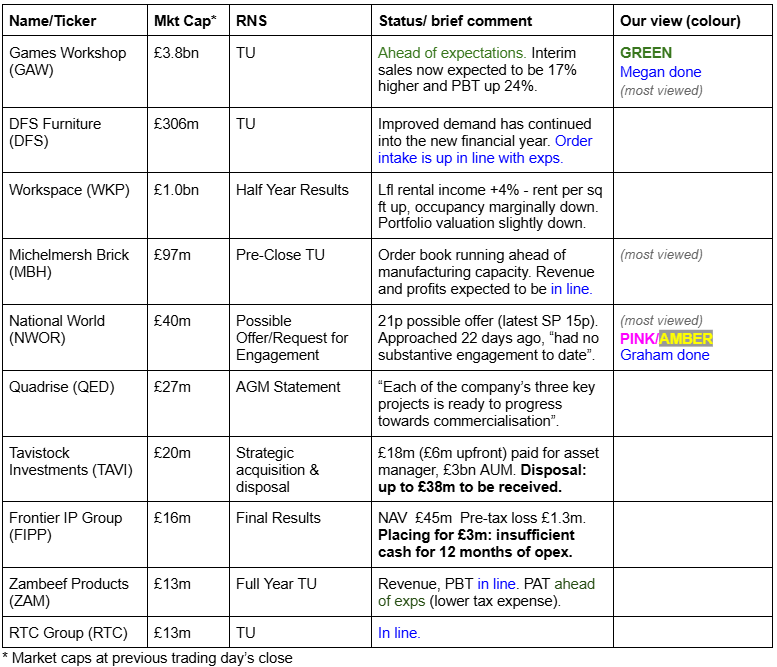
Summaries
National World (LON:NWOR) - up 22% to 18.25p (£49m) - Request for engagement from National World board - Graham - PINK (AMBER/GREEN)
NWOR’s largest shareholder is interested to buy the rest of the company for 21p, and asks the NWOR Board for substantive engagement. At first glance it might seem that it’s an opportunistic bid, but this sector does tend to trade very cheaply.
Games Workshop (LON:GAW) - up 12% to 13,010p (£4.33bn) - Trading Update - Megan - GREEN
GAW has announced it is trading ahead of relatively uninspiring consensus expectations. Revenue is now expected to be 17% higher than the first half of FY2024 and pre tax profits up 20%. No word yet on any TV series from its licensing agreement with Amazon, but there is exciting potential from other licensing agreements. Licensing revenue is forecast to more than double in the first half.
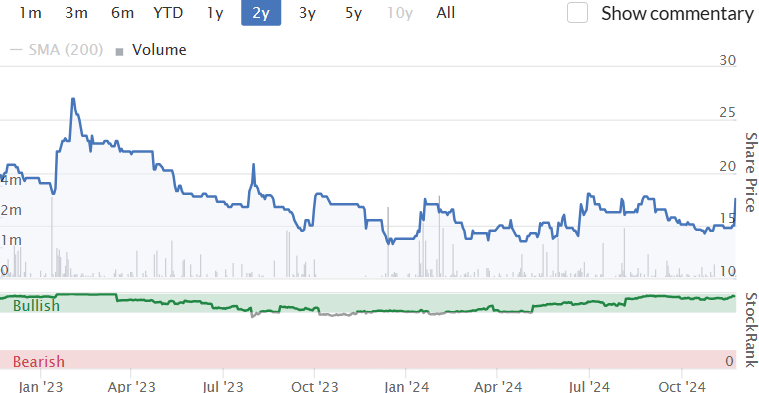
CMC Markets (LON:CMCX) - down 4% today to 276.75p (£782m) -Interim Results (yesterday) - Graham - GREEN
As this one is still attracting a lot of interest, I thought I’d do a follow-up section mentioning and responding to some reader comments, and providing further conclusions.
Short Sections
Michelmersh Brick Holdings (LON:MBH)
Up 2% to 105.9p (£99m) - Pre-Close Trading Update - Graham - AMBER/GREEN
We’ve been reasonably positive on this premium brick maker - see Paul’s coverage in September when it issued a profit warning that didn’t seem to affect the share price very much. It’s up by 9% since then.
Today’s trading update is in line with expectations.
Q4 performance has continued to be “resilient”:
Our order intake continues to run ahead of manufacturing capacity as we have focused on growing a well-balanced forward order book with appropriate pricing to support demand. While the inflection point in activity levels within the construction sector remains uncertain, we are working closely with our customers on the expected timing of despatches…
Estimates: thanks to Canaccord for an adj. PBT estimate of £9.7m this year, rising to £13m next year. They suggest that the company may seek to offset c. £0.5m of higher NI costs through “cost and productivity efficiencies”.
Graham’s view: not much to talk about here and I leave AMBER/GREEN unchanged.
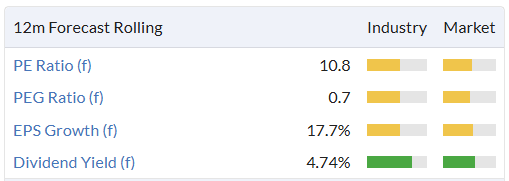
It passes 3 bullish screens, including Ben Graham’s Deep Value Screen.
Bodycote (LON:BOY)
Unch. today at 610.5p (£1.1bn) - Trading Statement (Tuesday) - Graham - AMBER/GREEN
Tuesday saw a trading update from Bodycote, “the world’s leading provider of heat treatment and specialist thermal processing services”. The update covered the four months from July to October (year end is December).
The main takeaway is that adj. operating profit this year is expected to be in line with consensus, at £127.9m (last year: £127.6m).
Organic revenue growth is very limited: 1% year-to-date, and lower than that (0.2%) in the last four months.
There is wide divergence across market sectors:
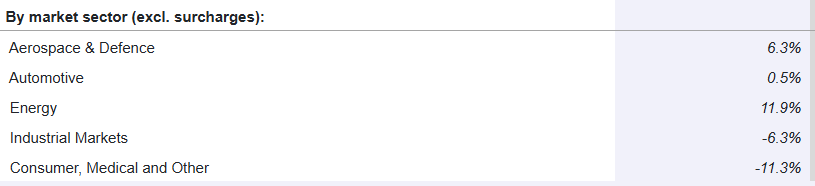
Bodycote refer to “the low level of global industrial activity” as hampering heat treatment revenues, and also to ongoing softness in the medical market.
Buyback: a £60m buyback is underway with £46m bought so far. Net debt at the end of October was little changed over the period at £68m despite £20m spent on the buyback during that time.
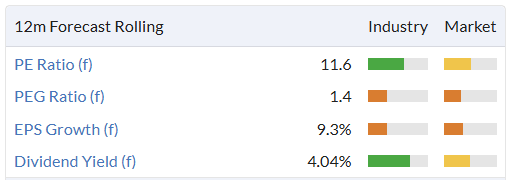
Graham’s view: I have a generally positive view of Bodycote, which is now 101 years old and has an excellent, consistent track record of profitability. I’ll leave the AMBER/GREEN stance unchanged at this moderate valuation.
Graham's Section
National World (LON:NWOR)
Up 22% to 18.25p (£49m) - Request for engagement from National World board - Graham - PINK (AMBER)
NWOR is arguably another “melting ice cube” type of legacy media stock, along with Reach (LON:RCH) (in fact, NWOR and RCH are advertising partners). It’s a consolidator of small newspapers and magazines.
We learn today that it has been approached by its largest shareholder, Media Concierge.
Media Concierge already owns 25.5% of NWOR. Along with those acting in concert with it, nearly 28% of NWOR’s shares are spoken for.
It has a Possible Offer at 21p per share in cash.
That’s a 40% percent premium to last night’s closing price (15p).
Strangely, Media Concierge says that it submitted its proposal 22 days ago and “has made every effort to engage privately with National World and its advisers, but has had no substantive engagement to date.”
I don’t know about you, but I would have thought that a company should be very responsive to a shareholder who owns a 28% stake and has an offer to buy the entire thing.
Perhaps the NWOR board did respond - and simply said No? Now that Media Concierge has gone public, I guess that will provoke a public response from NWOR.
Valuation - according to Media Concierge, the 21p offer represents a multiple of 7.2x trailing EBITDA and 3.8x adjusted trailing EBITDA.
Graham’s view - the latest interim results at NWOR showed good financial progress with net cash of £13m, adj. PBT of £4.8m, and actual PBT of £2.3m.
According to Dowgate’s analysis on the back of those results, the company was forecast to produce adj. EPS of 3p this year.
This suggests to me that the 21p offer represents a cash-adjusted PER of only about 5.4x (using adjusted EPS).
21p market cap
Minus 5p per share in cash = 16p enterprise value
Divide by 3p EPS forecast = 5.4x adj. PER.
However, I can’t say that I fully trust the adjusted earnings numbers, as the amortisation of intangibles strikes me as a real, ongoing cost in this case (the company spends internally on “digital intangible assets” and then strips out the amortisation of this spending from adjusted earnings).
Profits are unfortunately a matter of opinion and it seems to me that NWOR’s real EPS this year is more likely to be in the region of 2p-2.5p.
This increases the PER that I calculate Media Concierge are offering to more like 6.5x-8x. This sector does trade cheaply.
Perhaps RCH would consider a counter-offer?
As I’m fully GREEN on RCH (see here), I think I can reach to AMBER/GREEN on NWOR.
CMC Markets (LON:CMCX)
Down 4% today to 276.75p (£782m) -Interim Results (yesterday) - Graham - GREEN
This one is still causing controversy so I thought I’d mention a couple of things that didn’t make it into yesterday’s report. This might be a little dense in terms of numbers but that seems unavoidable as we try to figure out the reason for the share price weakness and where the full-year result might be heading.
Net Operating Income
Readers have helpfully brought up some of the following points - thank you.
In the H1 update in October, CMC said that H1 NOI was c. £180m.
H1 NOI has actually turned out at £177m, slightly below what the H1 update said.
Additionally, in the Q1 update back in July, they guided for full-year NOI within a range of £320-£360m.
Yesterday, they guided that the full-year result would be “in line with” the consensus forecast of £333m, which is below the midpoint of the original range.
So yesterday’s NOI result and forecast could be seen as disappointing A) from the point of view that the full-year forecast is below the midpoint of the original range, and B) that the actual H1 result was below the approximation given in the recent H1 update.
From my point of view, as I expressed yesterday, the biggest disappointment is that they did not simply upgrade the NOI forecast, as they already achieved 53% of the full-year forecast in H1 and we are already well into H2.
PBT/PAT
In the H1 update, they said they expected H1 PBT of c. £51m.
The actual H1 result was less than this, only £49.6m. So another disappointment there.
For the full-year result, let’s consider profit after tax (PAT). The consensus forecast on the StockReport is £58m. I think we might be able to touch that up by a few million pounds. But CMC itself didn’t give us any sense of an upgrade here either, or any guidance, despite generating an actual PAT of £35m in H1, which seems to be well over half of any full-year forecast.
They did say that full-year operating cost guidance (before bonuses and non-recurring charges) was unchanged at £225m.
If they achieve NOI of £333m this year and operating costs are only £225m, that leaves a massive £108m of potential operating profit (before bonuses, non-recurring charges, finance costs and taxes).
As pointed out in the comments, the H1 performance was sequentially much lower than the H2 performance of the previous financial year (PAT £35m vs £49m, NOI £177m vs NOI £210m). So perhaps this is the beginning of a downslope.
Graham’s view
I posted in yesterday’s comments section that in reality I don’t think the consensus forecasts are really worth focusing on, because nobody seems to have any idea what NOI is going to be, and CMC's guidance hasn't been accurate in the past. Look at what happened last year:
In August 2023, the company itself put out a forecast for full-year NOI of £250-£280m for FY March 2024.
At last year's interims, they reiterated this guidance. It was mid-November 2023, almost exactly a year ago. They again said NOI would be £250-£280m. There were only 4.5 months left in the financial year.
They did not upgrade until January, when they said it would be £290-£310m.
It turned out to be £333m.
In conclusion: NOI is too volatile to make sensible predictions, and CMC themselves don’t seem too concerned with trying to make accurate predictions or with keeping City consensus forecasts accurate. So I wouldn’t read too much into any of this.
The bottom line for me is that the company is performing well and the long-term outlook remains positive and arguably quite exciting (for example the partnership with Revolut).
With a large chunk of the market cap (now less than £800m) still backed up by c. £400m of balance sheet strength, and with a cash-adjusted PER that’s probably quite cheap (e.g. if net income is around £60m this year), I have no reason to change my GREEN stance on this.
Megan's Section
Games Workshop (LON:GAW)
Up 12% to 13,010p (£4.33bn) - Trading Update - Megan - GREEN
This is the second trading update Games Workshop (LON:GAW) has announced since its annual results in July. Management tends not to give its own guidance during its results, but at the time of the results, analysts were forecasting FY May 2025 earnings of 466p falling to 456p in FY2026. Both figures are down from the 478p reported in the 2024 financial year.
I don’t fully understand where those relatively gloomy forecasts came from - Games Workshop has reported an increase in its annual earnings in every one of the last 10 years and management remains committed to global, profitable growth. Thus, it was a little disappointing in September when the first of the company’s trading updates came in “in line”.
Not so this morning. Trading update number two confirms that revenue and profits for the first half of FY2025 are expected to be ahead of current forecasts. Sales from the core retail business are now expected to be not less than £260m (from £235m in the first half of FY2024) and licensing revenue is forecast to more than double to £30m (just shy of the £31m the company made in the whole of last year).
Pre-tax profits are forecast to rise more than 20% to £120m.
Interestingly, there is no mention of the rise in National Insurance or the national living wage which is set to increase from £11.44 to £12.21 from April 2025. Games Workshop employs over 3,500 staff globally although not many of them fall into the bracket most likely to be impacted by the NI changes (part-time, low wage staff). The company operates 134 stores in the UK, 83 of which are single staff stores and boasts very high staff retention rates.
Investors have very little reason to be concerned about any rise in staff costs. Operating margins have averaged 37% over the last five years. And with net profit margins widening over time, the company’s bottom line is growing at a faster rate than its top line. Net profits have risen at a compound annual rate of 18% over the last five years.
Where can the growth come from next?
With a forecast price to earnings multiple of 24x it is right to question if the company can continue to grow at pace. Margins can’t widen forever and there are some concerns that the market for fantasy figurines could be barrelling towards saturation.
On the latter point, I don’t believe there is any reason for concern. Games Workshop’s fantasy worlds continue to grow, sustaining demand from customers who have followed the brand for years. The company’s presence online is also helping it reach broader audiences than ever before. And the company can satisfy those audiences with the use of its trading partners and its online store - which is undergoing a major investment project.
And then there is the IP licensing. Last December, the company announced it had signed a multi-year agreement with Amazon to potentially launch a film or TV series based on the company’s IP. This deal is contingent on the company reaching an agreement about the nature and tone of the potential series, which the two companies have been working on this year. Management says it will update us when there is some news.
The potential for a film series based on the Warhammer IP could be a major new source of revenue for the group, even if the company can’t come to an agreement with Amazon. There is clearly appetite for films and series in this genre. In 2022, the US giant spent $465m on a TV series based on the Lord of the Rings - a budget that included the cost of buying the rights to the book. At the time it was reported that both Netflix and HBO were also interested in the series, but were out-priced by Amazon.
For now, all of the company’s licensing sales come from video games, the majority of which are sold in the US. Video games also have the potential to be turned into major TV franchises. Netflix spent $317m on two seasons of The Witcher. HBO’s budget for just one season of The Last of Us was $100m.
Megan’s view
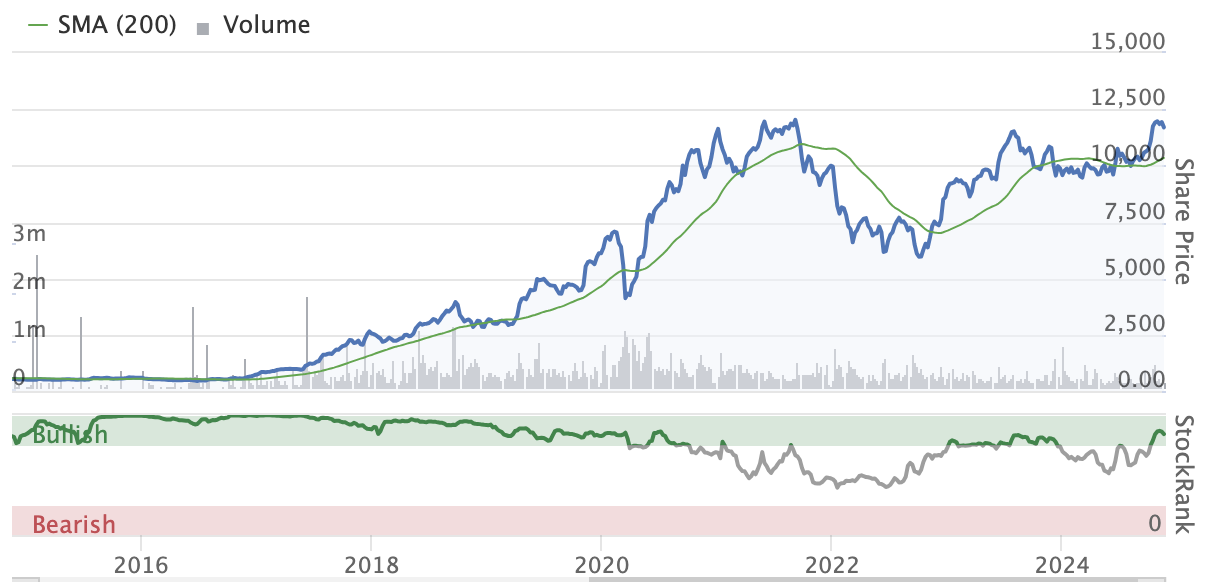
Games Workshop has delivered spectacular results for its investors in the last few years. Since 2017, the share price has risen 12-fold.
This is a wonderful company with an impressive management team who put the company’s substantial cash generation to great use.
I am excited about the potential of further licensing deals, which could provide further growth stimulus (a TV series would also likely boost retail sales as well - what better marketing than a TV series on Amazon?) But from a factor perspective (the bread and butter of Stockopedia’s investment mantra), there are also reasons to be optimistic. The company’s StockRank has just climbed into the top 20%. Historically our ranks have been a pretty good predictor of Games Workshop outperformance. GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

123 comments
Rumours circulating around a possible takeover bid for itv. Be interesting to see how the market reacts tomorrow
I would say they already started reacting on Friday Bob
Re Plus500/CMC. I’m not sure analysts look at the return of these companies in the right way. Certainly of the two Plus has a great return on capital employed, earned in cash, and is a determined buyer of its own stock. Arguably provided profits ,margins and regulation remain broadly consistent it needs to do nothing more-ever- to generate remarkable shareholder value - as it has done since 2014. All the time observers spend worrying about growth opportunities and new markets may be superfluous, even of concern if growth into new areas diminishes return on capital……The trend in book value per share says it all.
Plus500/CMC
I know its marmite but my 50% of my pf is Tesla (NSQ:TSLA) I bought last year
My small caps are up 10% this year due to a lucky offer on Keywords Studios (LON:KWS^J24) M
My Tesla is up 40% this year 100% to date. Glad I diversified
Games Workshop (LON:GAW) this interesting via BrilliantLeader on X
https://www.warhammer-communit...
I wrote to Cohort yesterday with some questions regarding the acquisition of EM Solutions.
The RNS, which I had embarrassingly missed, can be found here:
Acquisition of EM Solutions | Cohort PLC
Full marks to Cohort for a very quick response.
,
A general query. Does anyone remember the poster here who on several occasions has provided a really good analysis of his Investment Trust holdings, and ed specially a review of their outstanding dividends. I am considering at least a partial change of strategy as a result of a change in my family priorities.
I would love to have an update, as well as a pointer so that I can re-read his earlier postings.
Thank you.
You probably mean this: https://www.stockopedia.com/co...
Does anyone remember the poster here who on several occasions has provided a really good analysis of his Investment Trust holdings
Ken and Charles do their stuff here:
https://www.stockopedia.com/co...
Follow the links at the head of the article for previous months.
timarr
Stocko's answer to Phil and Grant of Eastenders fame
Phoenix- I went to a restaurant on Kefalonia 16 months ago to be greeted by "Eastenders" -Ken was not with me! I never watched the show- though had to wean my wife off it when we first met- restaurants and wine bars in the 80's did the trick !
Brilliant Charles and thanks again for the heavy lifting yourself and Ken both do on the monthly investment trust threads.
It is hopefully of interest- Trusts are a much maligned sector. Saw that in the 1980's when I sold them to institutions! Though we did quite well at it- the WoodMac team-I was a part of. Lucky to work with Robin Angus and Hamish Buchan- the experts. The late Robin Angus was a mentor to me in my early days and recognised as a true expert on the sector, miss his annual review. Never invested in Personal Assets Trust (LON:PNL) but he was involved in the formation of that to create a vehicle that did not rip off private investors.
Thanks to both timarr and Rusty2, and I think you both came up with the same comprehensive 'go to' links.
Unfortunately, I was referring to a contributor here who outlined his investments in ITs and outlined the impressive divis, then followed up some months later with an updated version of the original. Frustratingly, I can visualize the pages on this site but cant remember the name and didn't take a copy of the lists.
Jog anyone else's memory please? All I can remember in addition was that it was most impressive and helpful.
Note to self - always copy and file at the time!
Thanks Timarr- try to just do a monthly post about the sector- the best stuff comes from the people who comment and Trusts can make money-even short term . Would not advocate trading them , but some monthly movements -up and down are sharp.
Bloomsbury Publishing (LON:BMY) and Spotify Technology SA (NYQ:SPOT) have announced a partnership to distribute BMY audiobooks on SPOT. It has come in the newswire so nothing related to numbers have been announced but I guess it will add at least some pennies to BMY profits
Michelmersh Brick Holdings (LON:MBH) I take this update to be quite positive. Running the factories at full capacity is more efficient and lowers the unit cost of manufacture. It also suggests that there is some room to increase selling prices. Needing additional manufacturing capacity is actually quite a good problem to have!
Anyone heard anything on Card Factory (LON:CARD) I got stopped out a couple of weeks back but noticed signs of life last couple of days and volume today is double the norm, looks cheap and I've been musing a gamble on maybe santa rally might turn up and give it a life next 4-5 weeks but wouldn't want to hold to long due to possible nic issues and fact a lot of smart people think could be a profit warning in next update.
Card Factory (LON:CARD) I went in one earlier today and it was heaving, I had to say "excuse me please" about four times just to get round the shop!
I have visited Hostmore (LON:MORE^I24) many times had to queue……..
Not negative on Card Factory (LON:CARD)
AMBER
All the best
I just wanted to add my thanks to Graham, Megan and Roland for the quality and depth of the new format DSMR. I'm really enjoying the wider coverage of larger cap stocks and look forward to Megan's analysis of GSK (LON:GSK) whenever they next report.
It was nice to see analysis today of Games Workshop (LON:GAW) and similarly to some other posters today, I've learnt to ignore the negative sentiment that often fills the long gaps between updates from the perennially taciturn management.
I've held since 2019, selling and buying back along the way as waves of fear and optimism have swayed me but I eventually realised just how uniquely special this company is and decided to stop tinkering. The dividends have been a welcome addition too.
My biggest fear was always about the size of the opportunity and where the future growth would come from or as Megan references "..concerns that the market for fantasy figurines could be barrelling towards saturation."
The answer I believe is that the growth is coming from international expansion (particularly North America) with no realistic limit in the medium term to the size of the opportunity. It appears that the expansion of the independent outlets has been driving this growth. In 2018/19 they had 4,700 independent retailers in 69 countries whereas by 2023/24 they had 7,200 independent retailers in 71 countries. These independents represented 43% of sales in 2018 and by 2024 their importance had grown to 58% of sales.
In addition, GW operate their own stores but their relative contribution has declined from 37% of sales in 2018 to just 24% in 2024. Growth of these stores has been outpaced by the independents but the obvious exception has been North America where they had 134 stores as of June 2018, and by June 2024 this number had grown to 153. For Continental Europe the numbers were 148 (June 2018) growing to 154 (June 2024). Asia and Australia store numbers were barely unchanged over the same period.
Online sales contribution has actually declined as a percentage of sales from 20% in 2018 to 18% in 2024 which I believe indicates the extent to which the hobby is a community based endeavour where hobbyists prefer to meet up in stores to share tips and to game in person. It may also indicate a further growth opportunity for GW when they finally get to grips with their unwieldy IT systems which they have been struggling to overhaul for many years now.
The stated strategy is to grow the business through geographic spread, growing all of the three complementary channels and I believe that even if they were able to saturate their current markets, they would simply change focus towards some of their other markets. The importance of the independent retail outlets is explicit: "Independent retailers are an integral part of our business model helping us to sell our products around the world and importantly in areas where we don’t have our own stores." Indeed, the latest report also stated that "...we expect the majority of our incremental growth to be through sales to independents."
The independents and the online presence provide a beachhead for new markets which should provide enough opportunities to go after for many years to come. If the protracted negotiations with Amazon do eventually produce some blockbuster content, then it would only serve to broaden the appeal and the range of markets they could expand into. To my mind the long term bull case remains that this incredibly special company with decades of lore and IP could perhaps become something akin to Marvel.
Thank you for your analysis here. The store growth and use of independent retailers especially in the US, is so helpful to demonstrate the growth opportunities.
I completely agree with you, this is such a special company and there is plenty more to come.
Thanks for the CMC Markets (LON:CMCX) follow up Graham, it's been very helpful to find the bits I've missed yesterday. Have a great weekend
Altona Rare Earths (LON:REE)
Some very interesting companies and clever investors are buying this one. Bought a few as well at current levels-very small to take a proper position -it will go much higher though.
Probably my last post on this thread as well.
All the best to all and special thanks to the ones that contributed with their knowledge and experience.
Best wishes Yiannos…excited to hear that you’ve become Paul’s Scott’s writing partner on his substack*
*possibly joking
Jesus Christ NO!
Sorry to see you leave, I enjoyed your contributions
Must be a strong piece of info for you yiannos regarding Altona Rare Earths (LON:REE. I remember when Mark reviewed Goldplat (LON:GDP) you said you weren’t interested in “sub £10m small caps”. All the best on your venture
Not exactly what I have said about Goldplat (LON:GDP) who has been around and done nothing in a bullish gold environment.
All the best to you Dog with your ventures.
Hey Yiannos - good luck and stay in touch
I enjoyed our exchanges : we don’t agree on everything but the venn diagram in the middle has performed pretty well so a shame not to continue sharing ideas/thoughts. Will be some valuable contributions lost.
Best
David
Thanks David
You were perhaps ONE OF THE FEW that ALWAYS backed your opinions with numbers along with your future predictions and estimates.
All the best
Ah @davidjhill you live!! We had wondered where you had gone!!
Thanks yiannos1 for all your posts, like everyone else has said have a good one in the US!
Is there a particular catalyst for REE your looking at, is it the expected mining license and outcome of scoping study into the short term development of Muambe?
Is it the same company as Altona, which i was invested in a long time ago!
Altona Rare Earths (LON:REE)
There is no way one can value this as there are no revenues at the moment. If assays are good (my feeling they will be) this will probably double.
People buying this lately are on the right side of things most of the time.
I took a small punt (for my Christmas presents!).
Not sure if it’s the same one you were invested before-new management now that stated they will change the current name.
DYOR
All the best
An interesting parting gift for us Yiannos!! A sucker stock with no revenue....
Never mind a 10% swing on Altona Rare Earths (LON:REE) , Phoenix Copper (LON:PXC) is up 42% today!
Altona Rare Earths (LON:REE)
It’s my money on the table Wolfie and not yours. You haven’t studied this company properly.
I am on the right side of things as proven several times.
I wonder what does your friend Weinstein... says about the graph.
All the best
Best wishes Yiannos, I'm sorry to see you go. I always found your posts thought provoking and extremely useful.
Baby, please don't go! I have (nearly) always enjoyed and benefited from your comments!
Leaving us with more of a conundrum in Altona Rare Earths (LON:REE) than anything else, yiannos, the potential dilution is terrifying to one who has been bitten more than once and seen my stakes evaporate. I have enjoyed your contributions to the SCVR so sorry to see you go.
Not sure what’s going on at Volex (LON:VLX) and TT electronics (LON:TTG) . It appears that Volex has been buying shares in the latter, possibly as a prelude to a future bid. I assume that is the cause of continuing weakness in Volex shares. Any thoughts or views from more informed members of the community welcome.
I have a full size position in Volex.
Jonno - don't know where you get info that Volex is buying TT shares - and anyway - Mkt on both still appears unsteady
Your right bohenie, misread the RNS!
Hi Megan
Thanks for covering Games Workshop (LON:GAW) today which also happens to be my largest individual holding and, if it can hold today’s gains, is within touching distance of FTSE 100 entry. If this happens it will be the first time I have held a share through 250 entry all the way into the 100. One thing you mentioned in your analysis was…
I don’t fully understand where those relatively gloomy forecasts came from - Games Workshop has reported an increase in its annual earnings in every one of the last 10 years and management remains committed to global, profitable growth.
Throughout my whole holding period (my first purchase was in 2017), analyst forecasts have been too conservative. Analysts also struggle with the irregularity of dividend payments which tend to work out more or less quarterly but with variable amounts and sometimes 5 dividends in a year. People also struggle with scuttlebut because their shops are often empty.
I have trained myself not to over think it. Firstly, I ignore analyst forecasts and verify my thesis based on the company’s actual results and then I just do nothing until it reaches 10% of my portfolio when I top slice by about 20% (this is how I manage my own personal tolerance for risk). It is the best company I have ever owned, although I am dreading the day when the current CEO retires (in post since 2015 iirc) because that will present me with a difficult decision.
Cheers
Simon
Yes it’s always difficult when the CEO is top-sliced!
Jet2 (LON:JET2) Have added a few this morning. The company is in my view the pick of the UK airplane stocks. There is always something to worry about, but yesterday’s results were excellent as is the company’s custumer service. Within reason people will pay for quality and as Howard Marks would say buy quality when it’s cheap and the shares are just that.
RM (LON:RM.) Richard Staveley and Harwood don’t always get it right but they do so more often that not and Chris Mills and the team at Harwood are in my view the best UK small cap investors by some distance. I sold RM (LON:RM.) at 80p more or less break even, but notice that sharepad have upped next year’s earnings to 8.1p. The erudite Richard Staveley is confident, albeit there are no givens that the company will effect a sale of one its three divisions to reduce debt. On this basis I have bought back in this morning at 74p. Rockwood Strategic (LON:RKW) would not be holding 10.6% of NAV in the company if it didn’t have confidence in its investment thesis
Games Workshop (LON:GAW)
Thank you Megan for your coverage today. I don't hold but did just want to pick up on your comment that '....Games Workshop employs over 3,500 staff globally although not many of them fall into the bracket most likely to be impacted by the NI changes (part-time, low wage staff)....'
I agree that the impact of NI changes for Games Workshop (LON:GAW) will be low (high proportion of non UK staff) and that the company should be easily able to absorb any impact within their high gross margins.
However when considering the impact of employer NI changes for all companies it is important to remember that the lions share of the impact is not the 1.2% headline rate increase to 15% but the lowering of the starting threshold from £9100 to £5000 which results in an added cost of £615pa (£4100 x 15%) for every UK employee, not just the part time / low wage staff.
Snazzy
Hi Graham would be great if you got time to do a bit of a ramble on Bodycote (LON:BOY) it came up on my Garp screen just over 4% covered yield, decent stock ranks, rising (not massive increases) dividends every year, double digit operating margin and profits to market cap are good, downsides debt has doubled over the last few years.
Its been range bound last five years but currently near bottom of the 5 year chart and turning up again never going to shoot the lights out but maybe 20-25% upside over next twelve months with the yield on top.
Regards
Andy
Belluscura (LON:BELL) has jumped on news of an invoice discounting deal. Seems misplaced - without the money to make the product there aren't any invoices to discount.
National. World (again)
Have read Grahams analysis
One thing just occurred to me
I wonder if the end game here will be no bid but a major board and management shakeout .
Given bidder has a good holding in the bag, and think Rockwood are no fans of David. Montgomery who seems to think NWor is his plaything
I think the end result will be no bid but Montgomery takes a jump in order to satisfy dis satisfied holders
You read it here first
Good riddance to bad rubbish
Hmm Planetx - be careful what you wish for. There is an argument that Montgomery is a good publisher who knows how to make a profitable business and a shake up may not generate the returns we all hope for!
The problem is that many of us think he has acted too greedily. Personally I would welcome an outcome where he doesn’t jump but is reined in and gets rewarded on the outcome for all shareholders.
I am disinclined to engage in a bid at 21p personally. Yes, it is technically a declining business but the cash flow will be strong for years, if not decades.
Around 30p I’d be happier to take the bid but this business is capable of much more if it is run for shareholders.
David
Its not an argument I buy into
Any director that self serves to tbe extent he does at the expense of all shareholders just has no place.
Totally unacceptable
I feel his come uppance is looming .
What is a 'Pre-Close TU'? (MBH)
The close period, in accounting, is the time span covering the completion of a company's finances and the subsequent release of those financials to the public. During the close period, insiders are prohibited from trading company shares or making any relevant information public before it is officially announced.
To think I bought and posted about Games Workshop (LON:GAW) at £4.60 only 8 years ago, but sold for a modest profit not long after. Today the share price is up over £13 today alone and that’s and 3 times that buy price then. And it’s a massive multi bagger since then too.
I did the same also around 8 years ago with Anglo American (LON:AAL) buying at the very bottom at £2.20 and again selling for a modest profit soon after. The share rocketed to £20 in a few months.
These mistakes were a useful lesson. Ever since I’ve continued with that successful tactic of buying quality on big dips, but now run the winners and top slice them so that no one share is too high a proportion of the portfolio.
Guess there are many here who have done very well with Games Workshop (LON:GAW). It’s gone up 26 fold in just 8 years.
Run our winners is a basic obvious.
Run our winners is a basic obvious.
It is but it isn't always that easy - CMC Markets (LON:CMCX) yesterday is an example, In the time I've been investing in it, it's gone from about 80p to over 500p, back down to under a pound and then up to 300p before yesterday's debacle. In the midst of that topslicing when the price had risen significantly and then buying back when it fell would have been a good strategy (I did the latter, but sadly not the former).
I also sold Games Workshop (LON:GAW) when it had risen part way to its current level at about £30. I did finally convince myself to buy again when the price fell to about £70 a couple of years ago.
All of which says, I think, that it's easy to have a rule but not always easy to follow it because these damn shares simply will not play ball!
timarr
Tim, Games Workshop (LON:GAW) think you mean £130 not £30?
Some of my big winners have come a cropper, such as Burford Capital (LON:BUR), it does not always pay to run them, should have sold out sooner, went from £20 to £3, now back up to £10.
Shopify (NYQ:SHOP) also went down a huge amount, this run your winners logic, can be costly,tend to hold onto shares when falling.
Agree timarr . That just “ run our winners” is too simplistic. I now run them in the way explained in my post unless there is disappointing news. Then I sell the lot. BUT there have been occasional iffier updates from Games Workshop (LON:GAW) since that 2016 £4.60 low so I would have sold on that “rule.” Just not anywhere near as soon and it would have been for a far better profit.
8 years ago I was still selling winning shares like Games Workshop (LON:GAW) for no good reason or just to pay for an alternative….that often went on to do far worse than the share I ditched! I don’t do that now and the result is far more big winners in our portfolios. Now the tactics are simple. Run the winners as just explained.. And the sell on bad news rule means there are no longer any big losers in the portfolio.
Hi Ken, can I ask what your yearly returns have been in the last 8 years since you changed tactic?
I can’t give my yearly returns as I only use ii and H/L for our portfolios and unwisely don’t take advantage of the portfolio facilities here, but also because I take substantial amounts out of our portfolios from time to time as money is for spending as well as accumulating.
Also a serious sepsis health scare (hopefully now solved after an emergency operation) woke me up to the need to have (as far as is possible) worry free portfolios that would run themselves in the event of my demise.
So I sold a lot of our holdings and switched to quality big dividend paying shares and Investment Trusts. These provide regular and substantial income (a lot are paying at least 10% a year at my buy prices) but it is at the cost of reduced capital gain potential. So I’ve now got far less in growth shares, and higher risk choices.
No problem Ken, don't worry about it. Hope I didn't come across as nosey or a pain in the arse, just find other peoples tactics/results really interesting.
Also no problem at all Wolf. I would willingly have answered your question if able to.
I've held Games Workshop (LON:GAW) for 8 years and genuinely can't recall an iffy trading update in that holding period. There's been a couple that investors have mistakenly interpreted negatively but apart from the factory closure during covid it's been pretty much plain sailing with outstanding operational success, no PW's and loads of upgrades.
If CMC Markets (LON:CMCX) went from over 500p to under a pound, a 15 or 20% stop loss would have got you out.
Probably taken you out well before 500p though. Check your big winners, see if you would have been stopped out, if you used stop losses, you need to check the actual lows on the day, not the closing prices.
If CMC Markets (LON:CMCX) went from over 500p to under a pound, a 15 or 20% stop loss would have got you out.
At what cost? All of my multibagging stocks have fallen over 20% from their peak at some point, even Apple (NSQ:AAPL) and Alphabet (NSQ:GOOGL). I would be significantly poorer if I'd implemented stop losses.
As a general observation, stop losses are only useful when people don't have confidence in their stock selections or can't tolerate seeing red ink in their portfolio. It's called myopic loss aversion.
CMC Markets (LON:CMCX) is interesting in that's it's almost predictably cyclical. Quite why the market marks it as low as is does or as high is a mystery to me. As Graham says in his commentary today, there's no forward visibility. However, it throws off enormous amounts of cash through the cycle - over 50% of my starting cost has already been paid out - and there's the ever present possibility of a sale, which will only happen when Peter Cruddas decides the price is right or dies. I'm very happy to ride the rollercoaster.
timarr
There's nothing to stop you buying back into a stock that you have sold. Once a stock is down 20% it quite often carries on to a loss of 40% or more.
My Warpaint London (LON:W7L) shares are up around 200% from the price at which I bought my first tranche - for this share I have decided on a 25% stop loss, which was recently very nearly breached. If I had sold then I would almost certainly have repurchased once they started to rise again.
My Legal & General (LON:LGEN) shares have in fact breached the 20% rolling stop loss that I set for them, even though they are above the price at which I bought. But the yield is currently almost 10% - I am happy to hold for that yield.
Yes you can buy back in but then you have lost 20% or more each time.
l don't agree most stocks that drop 20% will fall further. Depends on the reason. Pan African Resources (LON:PAF) dropped over 20%, l could have sold at 30p, now it is 38p, to get back in is not always easy. After having suffered a loss would you buy back at 25-30% higher, l find that difficult.
Rusty, there is so much wrong in what you say.
'Yes you can buy back in but then you have lost 20% or more each time'
I'm sorry, if you sell a share and then it immediately starts to rise again you will only have lost 20% in the unlikely event that it goes up by 19% or so in a single day. Dealing charges are £10 or so and stamp duty on purchase is 0.5%.
'l don't agree most stocks that drop 20% will fall further'
I'm not going to niggle about not having claimed that most will fall further, I will just point out that in the past few years I have lost substantial amounts on shares that did continue falling after I foolishly did not act on the triggering of my stop loss.
There will always be shares that do rise again after falling, but in my experience they are the minority. Tim says that CMC Markets (LON:CMCX) fell from £5 to less than 1£. He could have sold at £4 and repurchased at £1.50.
So you buy back immediately it starts to back up? Sounds highly risky. What if it starts to go down again, do you wait for it to fall another 20%?
There will always be shares that do rise again after falling, but in my experience they are the minority. Tim says that CMC Markets (LON:CMCX) fell from £5 to less than 1£. He could have sold at £4 and repurchased at £1.50.
Hindsight is a terrific thing, isn't it?
I have, on a few occasions, tried to do what you're suggesting. In every single case it's not worked because the stock has completely failed to do what I expected it to do and after mulling it over for a while has flown off into the stratosphere. Games Workshop (LON:GAW) is the perfect example of that. London Stock Exchange (LON:LSEG) is another, Bioventix (LON:BVXP) too.I recognise that what you're suggesting may well work for you, but it's important to recognise it won't work for everyone. I'm currently running 21 stocks that have more than doubled, a number have gone up ten times. That cohort of shares dominates my returns, and are the reason I've managed to outperform the index over the last decade. Why would I want to change a method that works for me because I've had the odd catastrophe? I've lost far more by selling good shares than I have by holding on to the occasional bad 'un.
And, in any case, my total return on CMC Markets (LON:CMCX) is well over 100% if I include dividends. It's not exactly been a disaster. That said, it's important to recognise the difference between serial compounders and cyclical stocks. I should have topsliced CMC over £4 - I even wrote on here that the price was too high. But if that's the downside of my masterly inactivity I can live with it.
Investing is a very personal thing. It's not for me to tell you what to do - if it works for you then great. But it doesn't work for me, and it won't work for everyone. That's partly why investing is so interesting, it's as much about psychology as it is about the numbers.
timarr
I note on your Bio that you don't include 'sleep' in your extensive list of activities? Is this one of the secrets of your long terms, consistent investing success!!!! Lol
As ever wise words Tim - I have been suffering the same 'problem' with CMCX, RNO, BMY, XYZ etc etc.....!!
Hi N'n'G
You are not alone.
In forty odd years investing I think this is one of the most frustrating periods I can remember. On any rational criteria loads of UK companies are clearly undervalued, but have been so for quite a while now. The occasional takeover comes along, usually at a ridiculously low price but otherwise it's just a wasteland populated by sad tattered figures like myself, mournfully turning over the accounts of some stock or other that's been battered by the woeful decline of the UK's capital markets.
Meanwhile any kind of profit miss, even an illusory one brought on by analysts hallucinating (really, can AI be any worse?), causes a mass panic and a price collapse accompanied by endless wailing and gnashing of teeth by confused private investors.
I find it helps to look at my small (well, not so small any more) US portfolio and otherwise just lie back and keep taking the dividends. But boy, it is depressing.
timarr
Thanks for your reply Tim. I have been at it for 5 years, exclusively in UK small caps and so I bow down to your 40 years experience. I have to say that I am seriously thinking of switching some funds into US stocks now for the exact reasons you have given.
Hello Norfolk, I can say that investing in some US equities has been fruitful, no advice intended!
UK markets are truly awful.
I did switch some funds, to US stocks (MAG7 & Berkshire Hathaway (NYQ:BRK.B) + the S&P etf and it’s been a very pleasant experience so far.
Regards
Michael
I have to say that I am seriously thinking of switching some funds into US stocks now for the exact reasons you have given
The time to switch to the US was October 22 when it was relatively cheap. After a huge run up I’ve rarely seen it so expensive since 1999 - except at the peak of the 2021 madness perhaps. That doesn’t mean there’s a crash imminent. Earnings might continue to grow in the world’s leading economy. But it leaves little headroom for multiple expansion. Tread carefully.
I have to say that I am seriously thinking of switching some funds into US stocks now for the exact reasons you have given.
Having just pontificated about how investing is a personal thing it'd be remiss of me to try and give you advice ... but the US looks expensive and UK mid and small caps look very cheap. You've been horribly unlucky with your timing, but nothing provides an education in investing like growing up in tough times.
Stockmarkets are never guaranteed, but mean reversion is about the closest thing to a law we ever see. The UK can't stay cheap relative to other markets for ever.
timarr
I do wonder if it is worth all the time and effort when you can't beat a S&P 500 index tracker. I can't see the UK economy flourishing under this Govt. Hopefully l'm wrong. Yes the US is highly valued, best time to buy would be after a correction.
The UK can't stay cheap relative to other markets for ever.
While I’ve earlier posted a similar warning regarding high valuations in the US, I simply don’t agree with this statement. Since Brexit the trend is clear - and that’s not a political point. Capital is mobile and international investors have plenty of cheap alternatives with faster growing economies, while UK flows cross our borders in search of world class companies in which we conspicuously lack.
Hi BnB
Agree with your detailed points, but not with the headline. It's human nature to extrapolate today's conditions indefinitely into the future, but it's highly unlikely that the UK economy can remain moribund forever. Remember that in the last 30 years proportionately more UK stocks have gone up 30 times than US ones.
Of course, any rerating may not come in our lifetimes ...
timarr
Are you talking about stocks that are 30 years old or any stocks within the last 30 years. Do you have a link to this information, please?
https://www.schroders.com/en-u...
Thanks but the USA had 236 v UK 59, so l find your statement misleading. Proportionally yes the uk is slightly higher. The UK list includes investment companies.
Maybe because so many UK have disappeared?
This study seems to exclude more recent companies such as NVIDIA (NSQ:NVDA) ?
Deleted, fat fingers
I'd assumed it'd be obvious it was proportional given the relative size of the markets. A higher chance of a 30 bagger from a smaller pool sounds like better odds to me.
A lot of these companies are still around - Rotork (LON:ROR) Renishaw (LON:RSW) Spirax (LON:SPX) Cranswick (LON:CWK) JD Sports Fashion (LON:JD.) Jet2 (LON:JET2) - and many are on sale at the moment.
timarr
Not obvious at all, to me.
Edited ... Wouldn't want anyone getting confused and missing the important point ...
timarr
Hi timarr,
Thanks for your posts which are always interesting. Although I sometimes worry that we are so likeminded I only enjoy them because my in- built biases like their ego being tweaked, I’ll miss them one I’m gone - not dead, just unable to read them when my sub expires in 3 weeks :)
All the best, Si
Thanks for your posts which are always interesting. Although I sometimes worry that we are so likeminded I only enjoy them because my in- built biases like their ego being tweaked, I’ll miss them one I’m gone - not dead, just unable to read them when my sub expires in 3 weeks :)
Hi Si
Then I won't massage your ego by telling you that you've frequently made me pause and reconsider some deeply held opinion ...Wherever you go and whatever you do make sure you enjoy the profits!
timarr
Thanks for taking the time to reply again, Tim. We have definitely all been in tough times investing wise. Think I'll stay in the UK for a while longer.....
I think Games Workshop (LON:GAW) has gone up 26x not 260x in 8 years. And current price is about £130 not £13. But otherwise agree and interesting post.
Thanks MetalMaid for pointing out that the Games Workshop (LON:GAW) is 26 times and not 260. Don’t know where that extra 0 came from.I’ve edited my post to the correct figure. But that £13 figure was not the share price. It was the gain today.
“Only eight years”. Only people of a certain age could use that phrase! No insult intended. I’m one of them.
Given that it's 29 bagged in ' only 8 years ', we can probably forgive Ken this time :)... if anyone can point out a 29 bagger in the next 8 years, we'll all back up the truck :)
Games Workshop (LON:GAW) had to do a double take across the portfolios this morning. My isa, original investment in GAW £3,133 dwarfed by this morning’s gain of £20,776! Also, dividends received since purchase at £30,051 are 10x the original investment!
I find it really hard to sell stocks as I am too optimistic and have been wiped out in several shares over the years clinging on because I think they can do better -but this one more than makes up for all the screamers.
Wow! What a story and a real lesson in holding onto great companies that continue to deliver.
Congratulations
Great work Neils
Amazing success story there, I really want to find the next Games Workshop (LON:GAW) with 13 years till retirement, time is a ticking!
Time is ticking Newinvestor but don't fret, you have plenty left. I've been retired this 20 years.
I remember someone who was really into Games Workshop as a kid at prep school and then at secondary school always used to walk past a rather downtrodden looking shop.25-30 years ago now.Who would have guessed where they'd eventually end up.?However the last publicly listed decade or so has definitely given a distinct clue.Sitting on your hands, and not being shaken out by worries about potentially losing larger gains on occassional profit/ volatility blips, and just holding can definitely be the hardest part though!Games Workshop (LON:GAW) is one of those like Warpaint London (LON:W7L) , knowledge of what's popular and cool with a certain demographic definitely helps, especially if the share is a quality share too.I've been playing around with Google Trends a bit to try get a bit more insight there.
Run your winners yes but it is important to remember that trees do not grow to the sky.
Interestingly on a 10 year view Games Workshop (LON:GAW) is the best performing share in the FTSE All-Share at a 40.3% CAGR. The next being 3i (LON:III) group with a CAGR of 24.9%. Seven shares in the US beat this (including NVIDIA (NSQ:NVDA) and Advanced Micro Devices (NSQ:AMD) ) so is in rarefied company.
I am glad to have been them in since January 2018 though unfortunately with a hiatus in March 2020, for reasons I won't bore people with again. It has generated a profit equivalent to 18.2% of my current portfolio value.
To address Megan's comment "With a forecast price to earnings multiple of 24x it is right to question if the company can continue to grow at pace." With a company with this record I would say this rating PE(f) of 24.7 is not that punchy. That said I am probably going to top slice (I need some cash anyway) as it is now 19% of my portfolio.
Regards
Michael
Run your winners yes but it is important to remember that trees do not grow to the sky.
It's a challenge for active stock pickers, because beating returns on passive investments is not easy and you need to pick the stocks that multi-bag to do that.
Over the last three decades about 5.4% of UK stocks grew by 30 times (that's actually a higher percentage than in the US). That gives us about a 1 in 20 chance of finding one. Not easy, especially if you run a concentrated portfolio. Even harder to hang on through the hard times, but necessary if you want to beat passive funds, which will always hold them.
In the decade from 2011 to 2021 nearly 7% of UK stocks over £150m ten-bagged (also better than the US). There are an eclectic range of companies in there - JD Sports Fashion (LON:JD.) , Ocado (LON:OCDO), Diploma (LON:DPLM), Rentokil Initial (LON:RTO), Ashtead (LON:AHT) , Halma (LON:HLMA), Jet2 (LON:JET2), Cranswick (LON:CWK) and YouGov (LON:YOU). Most of those are having a tough time right now - but in there will be some of those future 30-baggers. Buying them now when they're struggling may well prove to be the best approach.
Interestingly all of these prioritise internal investment over dividends. Expanding profit margins is the main thing they have in common. A lot made good acquisitions.
Turns out active investing is hard. Who'd have guessed?
timarr
Correction 13.4% of portfolio
Morning Graham, If you get a chance could you take a look at XPS Pensions, thanks
Centamin (LON:CEY) trading suspended at request of company! Anyone have any idea why? Company & Exchange has not said anything . Worrying I hold.
Hi Revs8 - re Centamin (LON:CEY) Whole string of Form 8.3's issued yesterday afternoon - Company is in a Takeover situation
You should have received notification from your broker with pages and pages of info but short cut is that you will now receive part cash and part AshantiAngloGold shares in coming days. As I understand, the shares you will be given are not the NY listed version but a London listed derivative or whatever the correct term is!
National World (LON:NWOR) - Media Concierge goes public with a 21p bid.
National World
What a shit offer by media concierge
National World do right to totally ignore them and they just loom ridiculous writing their own RNS to the market .
Cant see them getting anywhere near to it unless north of 30p and they stop wasting everyones time with this nonsense .
National World will have earned its market cap in 4 years .
And David Montgomery and cronies wont want to let their gravy trainset get taken away
Cant see rockwood being interested
Clowns should go back to their media circus and drink a strong cup of coffee and make a grown up offer .
Steady as you go from Michelmersh Brick Holdings (LON:MBH) . I'm quite surprised at how well they are hanging in there.
But the Michelmersh Brick Holdings (LON:MBH) forecasts have been reduced recently. So not really surprising.
I'll settle for steady as you go on MBH GreyInvestor in these tough times for builders. They are one of our top long term holdings, I'm expecting their fortunes to improve along with builders over the next year or two.
Might be worth a look at Workspace (LON:WKP). Quick glance suggests it's steady as you go - trading profit up 5%, NTAV down a little. Profit figure here is illusory, as it's dominated by property valuation moves. Their flexible workspace offering still seems to be attracting business, downside looks like a few customers outgrew them.
Meanwhile Games Workshop (LON:GAW) continues to do what they continue to do - licencing revenue more than doubled and PBT expected to be up over 20%.
Obviously they'll both fall 20%+ today ... :-/
timarr
CMC Markets (LON:CMCX) still reeling a bit from yesterday's extreme reaction to "in line" results from CMC Markets (LON:CMCX). Hoping to see a bounce today from more rational investors !!
I've caught the falling knife. Hopefully it doesnt reach my toes
CMC Markets (LON:CMCX) It did bounce but it maybe called a dead cat bounce. Now down 3%.
As I noted yesterday, CMC showed a marked slowdown versus H2 24 (obscured by the very strong growth v H1 24). Guidance also seems to be slipping compared to what they said in June. Therefore the very strong momentum they showed earlier the year seems to have gone, and after such a strong run not surprised it has fallen back a bit. I'm staying on the sidelines for now.
I thought they were simply being conservative with overall estimates for the year, setting themselves up for a potential beat in 2025. I'd be interested for clarification from Graham after all yesterday's comments. Along with lots of us on here, I hold!!
Bouden, thanks for the comments on CMC, I have now provided an updated analysis so that the points raised by you and others get a mention in the main report. Cheers.
Thanks so much for this Graham. Much appreciated!
Agreed but the market knew it had 'only' done 170m vs the 210m in h2 via the TU and the SP was steady/rised so maybe something else spooked the market (I.e. not raising FY guidance)