Daily Stock Market Report (Fri 22nd August 2025) - ARB, REVB, APTA

Good morning!
Today's Agenda is complete.
11.15am: with the long weekend looming, I'm going to hang up my pen there for the day. I'll see you all refreshed next week!
I wrote a fun little article yesterday about a serious topic - Eating the sundae: the continued exodus from the LSE.
Spreadsheet accompanying this report: link (last updated to: 1st August).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Serica Energy (LON:SQZ) (£664m) | Triton production of 20k boepd net to Serica over the last two weeks. Overall guidance for the year unchanged at 33-35k boepd. | ||
Aptamer (LON:APTA) (£17m) | SP +16% 3 licences. Licence 2 is being discussed and APTA’s tech is yet to be evaluated for Licence 3. | RED (Graham) [no section below] My negative stance here is not a comment on the value of Aptamer's technologies. Rather, it's just my interpretation of the risks and probabilities involved here. Of the three licences described in today's announcement, I don't think any of them are actually signed yet. Licence 1 is at "an advanced stage of negotiation", and is forecast to cover 15% of Aptamer's annual overheads over the next three years. So that sounds positive. Licence 2 - Aptamer "continues to advance licensing discussions". Licence 3 - the potential partner still needs to evaluate the technology. So I wish the company well, but it looks and sounds to me as if it's a startup. As noted by Mark recently, the full-year trading update made no reference to profits (or losses). Revenues did at least increase 41% to £1.2m, and the company finished with cash of £1.06m, subsequently raised £1.83m. So let's call that a cash balance of £3m. The pre-tax loss in the previous financial year happened to be £3m. So I don't know how long the cash runway is, but it sounds like it might need another extension before the company achieves takeoff. | |
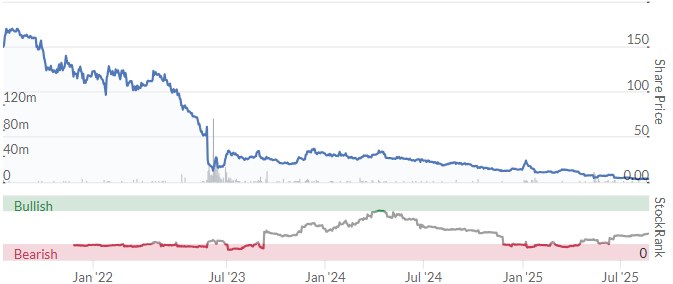
Argo Blockchain (LON:ARB) (£13m) | SP -19% Loan negotiations ongoing. Growler to own ≥ 80% of ARB. Bondholders will also get equity. | RED (Graham) [no section below] Massive dilution incoming. Existing shareholders will be left with scraps, and that's the best-case scenario. We called this one. I'm not going to go into this in further detail: the main point is that the extent of the potential dilution is still unknown, as it depends on the outcome of ongoing negotiations. Existing shares could be left with 10%, 1% or 0.1% of the company, after the recapitalisation. ARB says "there is general recognition that any agreement will include the provision of continuing value to shareholders in the form of their existing shares and, potentially, other forms of equity" but this doesn't provide any real guarantee. The only benefit of this plan (compared to REVB for example) is that it should at least wipe out the company's outstanding debts for good. | |
Revolution Beauty (LON:REVB) (£11m) | £15m fundraise today. FY 2025 rev -25%, pre-tax loss £16.8m. Co-founder returns as CEO. | RED (Graham) Massive dilution incoming. Even £15m of new equity will only allow partial repayment of £26m of net debt. We called this one. And after reading the details of the plan, I'm surprised how little of the fundraise will be applied to debt reduction. It turns out that the company has many other cash needs (and I'm guessing that some of these have been neglected while the company's cash position has been "tight"). Leverage will therefore remain high, even after the placing and subscription. |
Graham's Section
Revolution Beauty (LON:REVB)
Up 6% to 3.7p (£12m) - Preliminary Results - Graham - RED
It’s a busy day at Revolution Beauty; they’ve issued five announcements already.
Let’s get the results out of the way first (FY February 2025).
Revenue -25% (£142.6m)
Gross margin 38% (last year: 46%)
Adj. pre-tax loss: £5.5m
Actual pre-tax loss: £16.8m
Net debt closes at £26m, excluding leases. The £32m RCF was fully drawn.
Former management left this business in a mess, and that includes a £9m liability that is still on the balance sheet - this is a leftover from REVB’s acquisition of its manufacturing business (purchased from its own former Exec Chairman/co-founder).
It has suffered from various accounting issues over the years, and undisclosed loans, and today’s results include some further restatements.
Management changes: the former Chairman, who sold the company its manufacturing business, is returning as CEO.
The former CEO, who admitted no liability after the loan scandal, is also returning, as a consultant. At least one positive is that he has a decent stake in the company (15% before the fundraise).
Current trading and outlook
Q1 sales fell 29%, and Q2 is thought to be down c. 25%.
Action has been taken to address the declines in revenues by: resurrecting profitable stock keeping units that have been discontinued; re-launching the Relove value brand with new retail distribution partners; and establishing a profitable discount outlet channel. The pipeline on new product development has been enhanced, with more digital first product launches planned. Commercial discipline has been improved, to focus on more profitable product lines, customers and channels… the Company expects year-on-year revenue decline rates to reduce significantly in the second half of the year.
The returning co-founders seem primarily focused on cost-cutting:
At the heart of this plan is a return to Revolution Beauty's original formula for success - fast, trend-driven innovation combined with a product-led strategy. A key element of the plan will be reducing the Company's cost base, which will provide financial stability in the near term and will also encourage operational alignment across all business functions. In addition to cost savings already realised, the Founders estimate that an additional £7.5m of annual staff cost savings can be realised by FY27 as a result of a material reduction of headcount across the Group's geographies and business functions….
New guidance for FY26:
Revenues £110-120m
Adjusted EBITDA of low single digit millions will be achieved after staff costing measures have been implemented.
Annual adjusted EBITDA run-rate of £8-10m by the end of FY26.
Use of proceeds
I’m surprised to see how little of the £15m gross proceeds will be applied to debt reduction. There are many other cash needs:
£4m to repay debt
£2.5m capex
£2.5m working capital
£2m set aside as a working capital contingency (let’s call it an emergency fund)
£1.9m restructuring costs
£2.1m transaction costs
HSBC and NatWest have extended the company's RCF to July 2028 and agreed a covenant “holiday” until May 2026, but they have also reduced the size of the facility by £4m (to £28m) and adjusted the interest rate, so that it now varies with the company’s EBITDA performance.
Risk warnings: these risks may seem obvious, but I’d like to highlight them (emphasis added).
…there is no certainty that the additional capital will be sufficient to meet future requirements or to respond to unforeseen events or business needs… As such, the Company is currently not in a position to determine how much additional capital may be required (if it is required at all) or when it might be required;
Furthermore:
…even with a lower level of net debt following the Fundraise, the Company currently maintains a relatively high level of debt with its two lenders. While the Founders anticipate that the measures they intend to implement to drive growth and profitability will enhance Revolution Beauty's long term value, the high debt levels still pose a substantial risk to the ongoing solvency of Revolution Beauty. In the event of a material deterioration in financial conditions, there is a consequential risk that the Company breaches the covenants contained in Revolution Beauty's banking facilities, which could accelerate repayment.
Dilution: there is a placing for 345m shares, and a subscription for 155m shares, so I make that 500 million new shares, plus whatever the Retail Offer raises.
The existing share count is 319m. So existing shares will only own about 37% of the company after the fundraise, with further dilution from the Retail Offer.
Graham’s view
I’m staying RED on this for a number of reasons. Firstly, I don’t think the previous management team covered themselves in glory, so I don’t see their return as a reason to change my negative stance.
Secondly, the fundraise is only going to partially resolve the company’s financial problems. It will remain heavily indebted.
At the current share price of 3.7p, I think the implied market cap based on the new share count is £30m. We could add on £28m of outstanding debt to make for an enterprise value of £58m. If the corporate makeover is successful and the company hits its £10m run-rate EBITDA target next year, that makes for an EBITDA multiple of about 6x. Is that cheap? Maybe, maybe not. Its leverage multiple (net debt/EBITDA) could still be pretty high, and I’d see it as a risky bet.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
I've heard of Argo Blockchain (LON:ARB) but did not realise it was MC 13m.
Anything under 100m of no interest, especially LSE and that is way generous in my view.
I want to make money - in this century - not the next - and for sure most of the small value report stuff wont be around or gobbled up.
Revolution Beauty (LON:REVB) very popular here - but seriously - one for the JISA?
Take a look in the mirror.
We all loved Paul Scott and his character, musings and putting insights into the otherwise boring metrics. And if want to follow then the podcast is still there.
My love for small caps has waned - but it is home town so always open.
I did not follow like a lamb, like I don't follow Southbank, Seeking Alpha, Shares magazine or Moneyweek but like most people with a brain use them for information, ideas and then the uncatchy DYOR.
I think what's better (? subjective) about the daily report is the less emotional aspect of it. Back in the day there were a few, let's call them, childish tantrums from the main players which lowered the tone of the place, and by association called into question the insights offered.
I miss certain aspects of the PS days, but overall think the current setup is more professional.
WH Smith (LON:SMWH) decent bounce on this one today. May not like the prices they charge when their the only option in some travel hubs but feel air travel is booming at the moment and this company should do well from that in the short term/ medium term - profit overstating / profits warning and selling their high street shops for not a lot …… aside
I thought about buying but I feel to many unanswered questions. The board should have commented on dividend future etc. I suspect the CFO will take the hit, get blamed and dividend cut. Buyers at the moment are flying blind . If the board had more information surely they would have put out a more positive statement on the advice of their advisers. Probably not another Pat Val, but there could be more coming out about profitability in the USA over past years.
SQZ looks good after ITH also North Sea oil hit the roof this week
What companies should be covered in DSMR
I think the team should be praised for the brilliant work they do everyday. They have got the mix of companies for discussion spot on. I have no interest in micro caps and highly speculative companies. But I know some in this group do follow such entities.
Large caps and occasional us stock discussions are great.
I really like the early morning list of the companies published after 7 am.
I also appreciate very much the fact they now cover the resources companies, gold and oil in particular.
Well done and thank you very much.
There has been a lot of discussion recently on which companies the DSMR should focus on. Previously during Paul Scott's reign it was specifically for small companies only.
Personally i think the expansion to cover large cap was a good move because there are certainly a lot of strong investment prospects there, e.g. Rolls Royce. They also give a steer on the macro situation, e.g. Tesco etc.
Time / resources are however limited, so some need to be ignored. I suggest there is little point analysing the fortunes or misfortunes of very low rank companies like Argo Blockchain. If you are interested in this type of dog, then you are better off looking at the bulletin boards where all the crazies meet.
Perhaps a cut off where the DSMR does nor report on anything with a stock rank below 35 would separate the wheat from the chaff.
I think reviewing what has gone wrong at some companies can be educational and instructive on things to be wary of.
The update from Revolution Beauty (LON:REVB) and reappointment of former executives who were in place when the company had some previous challenges reminds me of the "channel stuffing" issues that surfaced a few years back. That, along with the issues reported by WH Smith (LON:SMWH) yesterday highlight the risks of earnings manipulating (deliberate or inadvertently) which is useful to be aware of.
Sometimes the lowest ranked companies can provide useful lessons.
I agree with this.
When I started investing I spent about 3 years chasing exploration company story stocks and lost money (not gigantic sums luckily) before an investing friend gave me some books on value investing. Literally since then my CAGR is 11%. Most of the companies I invested in during my "formative years" I suspect would have had a stockrank below 10! I wish I'd found Stockopedia sooner.
out of interest what were the books?
Always on the look out for new books in investing.
Peter Lynch's classic Beating the Street was one of them! If I remember the other I'll reply back again.
Epitychia
I for one am also happy with the current mix and willing to leave company selection to the authors. I don’t agree with arbitrary cut offs based on Stockranks which are largely based on old facts and accounts. If a low SR co issues an update which announces a new set of large orders I don’t want to potentially miss the boat waiting for the SR to catch up.
Think its a combination of Stock Rank and Mct Cap so don't think should set hard and fast rules but from my perspective not interested in the mini cap coys
I think the daily report is good and welcome the broadened focus. Most of the UK market is small cap globally these days, so I welcome inclusion of FTSE-100 and FTSE-250 companies where there is more quality. Keep up the good work.
I think it’s spot on. Varied enough to cover a reasonable range and provide good depth of analysis of results. Combined with the other blogs they write, which pick up some of the others big or small, it gives a very good overall coverage for me. I’ve yet to find insufficient coverage of any stock where I’ve done a dive into the discussion archive. So I vote keep it as is.
I really enjoy the mix of company reporting here- showing the depth and breadth of opportunities. Fundamental structures and narratives change across all sectors. The lore is that 'Elephants don't gallop' (buffet) but if the MAG 7 were a country measured in GDP they would be third behind the USA and China (!) If valuation is where the story meets the numbers then I think focussing on interesting companies with both is the key.
For example - It's interesting to me that Revolution Beauty (LON:REVB) turns over more than Warpaint London (LON:W7L) but seems to have tiny margins and a very different story.
All great coverage. Thanks.
Re: "...'Elephants don't gallop' (buffet)..."
Point of Oder: That was Jim 'Zulu Principle' Slater, actually - presumably he'd never seen a bull elephant in musk protecting his harem from rivals - I have, but only on the telly.
They do in the US markets. Yes it was Jim Slater.
Rudyard Kipling !
Argo blockchain could be a good investment if the price of canadian hydroelectric goes to zero, the price of BTC goes to $1M, BTC replaces gold as a store of value and the dollar as the global hegemonic currency and El salvador invades the US and crowns Michael Saylor King.. In that case I'm all in. Otherwise I'll stand on the side lines and watch new investors with awe.
Serica Energy (LON:SQZ) still looking good. I hold.
Yes, the 20,000 boepd mentioned in the table is just from Triton. Total production has been 50,000 boepd net to Serica. This will drop temporarily with Bruce maintenance but the guidance looks very achievable and it will be interesting to see what guidance is for next year with less downtime.